
Credited to Debtors Account Debited to Fixed Asset Account Shown in Branch Account Not shown in Branch Account


Sometimes a business may earn an income by delivering the goods/services within the stipulated time. But the business may not have issued an invoice to the customer. Such a scenario is what is called unbilled revenue. Note that as per the accrual concept of accounting, sales are recognized on the daRead more
Sometimes a business may earn an income by delivering the goods/services within the stipulated time. But the business may not have issued an invoice to the customer. Such a scenario is what is called unbilled revenue.
Note that as per the accrual concept of accounting, sales are recognized on the day it was made, irrespective of whether the business receives cash or not.
The business records unbilled revenue by passing the following journal entry:
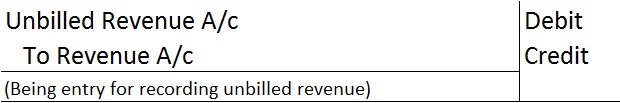
Unbilled Revenue is treated as an asset because it is yet to be fully recognized as an income. Therefore it is debited. Revenue A/c is credited as there is an increase in income.
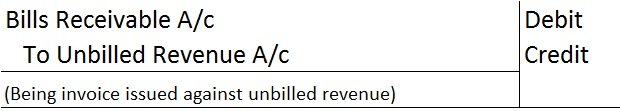
Once the bill/invoice has been issued to the customer, the following entry is passed to close the Unbilled Revenue A/c.
Let me explain this concept with an example,
Luca Traders, a business dealing in stationery and office supplies receives an order on August 5th for 1,000 pens worth 10 each. On August 8th they deliver the pens but they are yet to issue an invoice to the customer. They issue the invoice only on August 13th.
So the sales revenue of 10,000 (1,000*10) will be treated as an unbilled revenue for the period of August 8th – August 12th. On August 8th the following entry is made to record unbilled revenue.
| Unbilled Revenue A/c | 10,000 |
| To Revenue A/c | 10,000 |
| (Being entry for recording unbilled revenue worth 10,000) |
When the invoice is sent to the customer on August 13th, the following journal entry is posted to close the unbilled revenue A/c.
| Bills Receivable A/c | 10,000 |
| To Unbilled Revenue A/c | 10,000 |
| (Being invoice issued against unbilled revenue) |




The correct answer is 4. Not shown in Branch Account. The value of depreciation of fixed assets will be not shown in the branch accounting because the opening value of the asset is recorded at the start of the period on the debit side and the closing value of the asset is shown on the credit side atRead more
The correct answer is 4. Not shown in Branch Account.
The value of depreciation of fixed assets will be not shown in the branch accounting because the opening value of the asset is recorded at the start of the period on the debit side and the closing value of the asset is shown on the credit side at the end of the period.
The difference between the opening and closing values of the asset is the value of depreciation which is automatically charged. In this case, if depreciation is also shown it will be counted twice.
Example:
XYZ Ltd purchased furniture for one of its branches on 1st January. Following are the details of the purchase:
Depreciation is provided on furniture at @10% per annum on the straight-line method.
As additional furniture was purchased after 6 months, depreciation will be charged on that and the total depreciation of 3,250 will be charged on the furniture of $35,000 ($30,000+$5,000) and the difference will be the closing balance which will be shown in the branch account on the credit side.
The depreciation amount will not be shown in the Branch Account as the difference between the opening and closing values of the furniture reflects the value of depreciation. If depreciation is shown in the account it will be counted twice.
See less