

To ascertain the debtors and creditors of the business To ascertain the financial position of the business To ascertain the profit or loss of the business To ascertain the collective effect of all ...


Depreciation is an accounting process of allocating the value of an asset over its estimated useful life. When a company purchases an asset, depreciation will be calculated at the end of every financial year on the asset. The company records the amount of depreciation in a separate ledger, i.e., AccRead more
Depreciation is an accounting process of allocating the value of an asset over its estimated useful life.
When a company purchases an asset, depreciation will be calculated at the end of every financial year on the asset. The company records the amount of depreciation in a separate ledger, i.e., Accumulated Depreciation. This expense will be debited instead of depreciation in the Asset ledger.
Accumulated Depreciation
Accumulated depreciation is the accumulated reduction in the cost of an asset over time.
Depreciation is the reduction in the value of an asset over a specific timeframe, whereas accumulated depreciation is the sum of total depreciation on an asset since we bought it.
we will understand this concept with a simple example.
suppose machinery depreciates as follows
Year 1 – Depreciation is 5,000
Year 2 – Depreciation is 5,000
Year 3 – Depreciation is 5,000
Accumulated Depreciation in Year 3 = 5,000 + 5,000 + 5,000
Therefore, overall 3 years of depreciation are accumulated at the last year-end.
Journal entry for accumulated depreciation
Example: Excellence Co. has purchased a new motor vehicle which costs $8,000 for their cab business. The motor vehicle is depreciated at @20% per annum. At the end of the year, Excellence Co. will record this accumulated depreciation journal entry.
Year 1
Depreciation A/c Dr. – $1600
To Accumulated depreciation A/c – $1600
Year 2
Depreciation A/c Dr. – $1600
To Accumulated Depreciation A/c – $1600
Therefore, the Accumulated depreciation for the 2nd year end is $3200.
At the time of the sale of the motor vehicle, the amount of accumulated depreciation will be reduced from the total value of the asset.
Provision for depreciation
Provision for depreciation is very similar to accumulated depreciation. Instead of reducing the amount of depreciation from the value of an asset, a separate provision A/C will be created, and the depreciation amount will be credited to the provision account, i.e., Provision for Depreciation account every year, and the asset will be shown the same value without reducing the depreciation from it.
Journal entry for provision for depreciation
Example: Yesman Co. purchased Machinery worth $40000 at the beginning of the current year for their production. The machinery will be depreciated at @10% per annum. At the end of the year, Yesman Co. will record this provision for depreciation journal entry.
Year 1
Depreciation A/c Dr. – $4000
To Provision for Depreciation A/c – $4,000
Year 2
Depreciation A/c Dr. – $4000
To Provision for Depreciation A/c – $4000
Therefore, the Provision for depreciation balance will be $8000 at the 2nd year-end.
At the time of sale of the machinery, the amount of provision for depreciation created till the date will be reduced from the asset’s value.
Conclusion
Provision for depreciation and accumulated depreciation refers to the amount of depreciation accumulated over the useful life of an asset.
The terms accumulated depreciation and provision for depreciation are different in hearing, but these are similar from the financial perspective.
See less



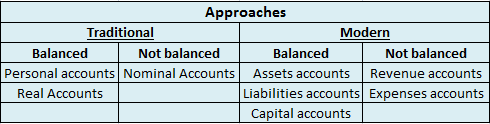
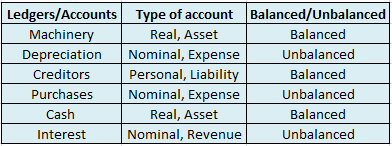
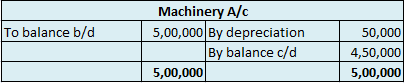
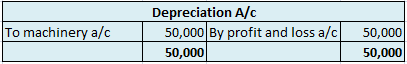
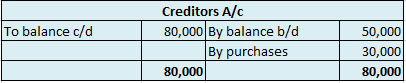
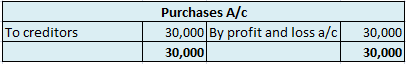
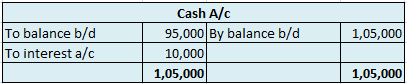
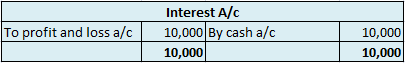


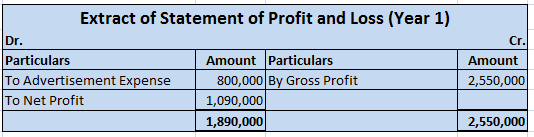
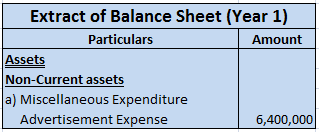


The correct answer is 4. To ascertain the collective effect of all transactions pertaining to a particular account. The reason being is that in the ledger account all the effects are recorded for example, how much money is spent on a particular type of expense or how much money is receivable from aRead more
The correct answer is 4. To ascertain the collective effect of all transactions pertaining to a particular account. The reason being is that in the ledger account all the effects are recorded for example, how much money is spent on a particular type of expense or how much money is receivable from a debtor. In ledger accounts, information can be obtained about a particular account.
Ledger is the Principal book of accounts and also called the book of final entry. It summarises all types of accounts whether it is an Asset A/c, Liability A/c, Income A/c, or Expense A/c. The transactions recorded in the Journal/Subsidiary books are transferred to the respective ledger accounts opened.
Importance of preparing ledger accounts:
- Ledger accounts get the ready results i.e. helps in identifying the amount payable or receivable.
- It is necessary for the preparation of the Trial Balance.
- The financial position of the business is easily available with the help of Assets A/c and Liabilities A/c.
- It helps in preparing various types of income statements on the basis of balances shown in ledger accounts.
- It can be used as a control tool as it shows balances of various accounts.
- It is useful for the management to forecast or plan for the future.
See less