


Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders. Therefore the cost of retained earnings is similar to theRead more
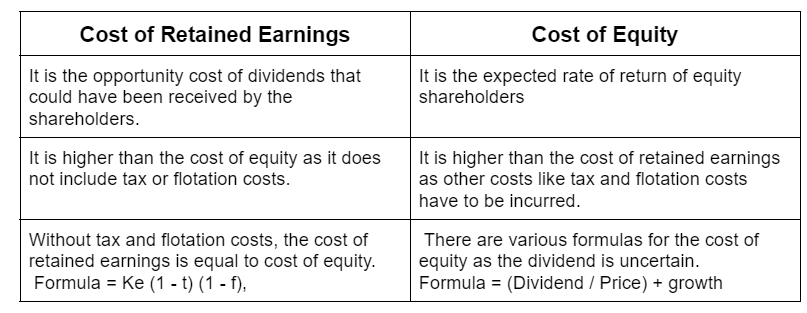
Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders.
Therefore the cost of retained earnings is similar to the cost of equity without tax and flotation cost. Hence, it can be calculated as
Kr = Ke (1 – t) (1 – f),
Kr = Cost of retained earnings
Ke = Cost of equity
t = tax rate
f = flotation cost
Here, flotation cost means the cost of issuing shares.
EXAMPLE
If cost of equity of a company was 10%, tax rate was 30% and flotation cost was 5%, then
cost of retained earnings = 10% x (1 – 0.30)(1 – 0.05) = 6.65%.
From the above example and formula, it is clear that the cost of retained earnings would always be less than or equal to the cost of equity since retained earnings do not involve flotation costs or tax.
A company usually acquires funds from various sources of finance rather than a single source. Therefore the cost of capital of the company will be the weighted average cost of capital (WACC) of each individual source of finance. The cost of retained earnings is thus an important factor in calculating the overall cost of capital.
Another important factor of WACC is the cost of equity. The cost of equity is sometimes interchanged with the cost of retained earnings. However, they are not the same.
See less






As per the companies act 2013, the rate of depreciation for cars/vehicles and their useful life is mentioned below They are categorized by the companies act as follows: when these car/ motor vehicles are owned with no intention to sell within the accounting period and are generally used to generateRead more
As per the companies act 2013, the rate of depreciation for cars/vehicles and their useful life is mentioned below
They are categorized by the companies act as follows:
Car/motor vehicles are considered as fixed tangible assets. Treatment of these cars/ motor vehicles is similar to those of other fixed assets. The depreciation will be shown as an expense in the profit and loss account and also the value of these assets will be adjusted in the balance sheet.
Explaining with a simple example: Mars.Ltd purchased a car for Rs 10,00,000, and use it for its official purpose. Its useful life as per act is taken as 6 years and the rate of depreciation as 31.23% as per the WDV method.
Therefore depreciation as per WDV is calculated as follows
Cost of car = Rs 10,00,000
Residual value = NIL
Rate of depreciation = 31.23%
depreciation for first-year = Rs (10,00,000 – NIL)*31.23%
= Rs 3,12,300
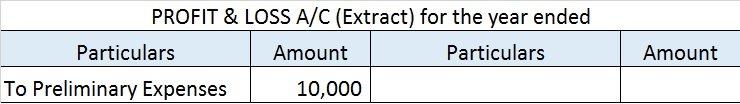
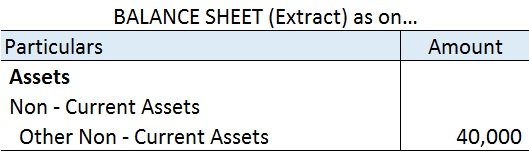
Calculated depreciation on this car will be shown in the profit and loss account as an expense and the same will be treated under the balance sheet every year. Here is the extract of profit and loss and the balance sheet for the above example.


See less