Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

How is accounting income different from taxable income?

  • 0 Answers
  • 0 Followers
Answer
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

A ledger account is prepared from?

A. Events B. Transactions C. Journals D. None of These

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 14, 2021 at 5:38 pm
    This answer was edited.

    The correct option is Option C: Journal Entries. Journal entries are the primary entries in the books of accounts and they are passed when any transaction or event takes place. Every journal entry has a dual effect i.e. two or more accounts are affected. For example, When cash is introduced in the bRead more

    The correct option is Option C: Journal Entries.

    Journal entries are the primary entries in the books of accounts and they are passed when any transaction or event takes place. Every journal entry has a dual effect i.e. two or more accounts are affected.

    For example, When cash is introduced in the business, the journal entry passed is:

    Cash A/c    Dr.      ₹10,000

    To Capital A/c  ₹10,000

    The accounts affected here are Cash A/c and Capital A/c.

    Cash A/c gets debited by ₹10,000,

    and Capital A/c get credited by ₹10,000.

    All the processes of accounting are conducted in an ordered manner known as the accounting cycle.

    The first step in an accounting cycle is to identify the transactions and events which are monetary in nature.

    The second step is to record the identified transactions in form of journal entries.

    And the third step is to make postings in the general ledger accounts as per the journal entries.

    Hence, the preparation of the ledger is the third step in the accounting cycle and is prepared from the journal entries.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Miscellaneous

What is internal reconstruction?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on March 26, 2022 at 10:09 am

    Introduction Internal reconstruction refers to the process of restructuring a sick company’s balance sheet by certain methods to turn it financially healthy, thus saving it from potential liquidation. Explanation When a company has been making losses for many years, it has a huge amount of accumulatRead more

    Introduction

    Internal reconstruction refers to the process of restructuring a sick company’s balance sheet by certain methods to turn it financially healthy, thus saving it from potential liquidation.

    Explanation

    When a company has been making losses for many years, it has a huge amount of accumulated losses due to which the reserve and surplus appear at a very low or negative amount in the balance sheet.

    Also, such a company is said to be overcapitalised as it is not able to generate enough returns to its capital.

    As the company is overcapitalised, the assets are also overvalued. The balance sheet also contains many fictitious assets and unrepresented intangible assets.

    The balance sheet of such a ‘sick’ company looks like the following:
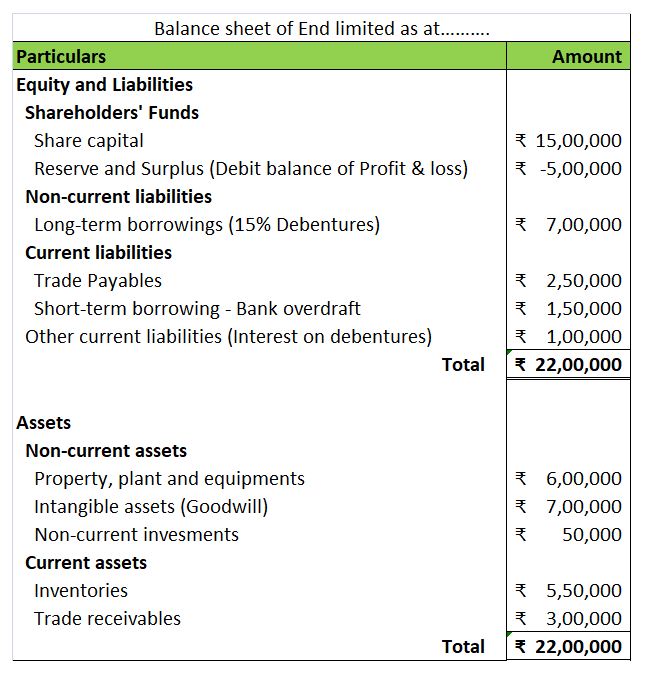
    Hence, to save the company from liquidation,

    • its assets and liabilities are revalued and reassessed,
    • its capital is reduced by paying off part of paid-up capital to shareholders or cancelling the paid-up capital.
    • the right of shareholders related to preference dividends is altered,
    • agreements are made with creditors to reduce their claims and
    • fictitious assets and accumulated losses are written off.

    In this way, its balance sheet gets rid of all undesirable elements and the company gets a new life without being liquidated.  This process is known as internal reconstruction.

    Legal compliance

    The internal reconstruction of a company is governed by the provisions of the Companies Act, 2013.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Vijay
VijayCurious
In: 1. Financial Accounting > Miscellaneous

What are outstanding expenses?

  • 1 Answer
  • 0 Followers
Answer
  1. Radha M.Com, NET
    Added an answer on August 17, 2021 at 4:51 pm
    This answer was edited.

    Outstanding expenses are those expenses that have been incurred during the accounting period but are yet to be paid. Basically, any expense which has become due for payment but is not paid will be called an outstanding expense. Outstanding expenses are treated as a liability as the business is yet tRead more

    Outstanding expenses are those expenses that have been incurred during the accounting period but are yet to be paid. Basically, any expense which has become due for payment but is not paid will be called an outstanding expense.

    Outstanding expenses are treated as a liability as the business is yet to make payment against them. Examples of outstanding expenses include outstanding rent, salary, wages, etc.

    At the end of the accounting year, outstanding expenses have to be accounted for in the book of accounts so that the financial statements reflect the accurate profit/loss of the business.

    Journal entry for recording outstanding expenses:

    Expense A/c Debit
       To Outstanding Expenses A/c Credit
    (Being expenses outstanding at the end of the year)

    The concerned expense A/c is debited as there is an increase in expenses. Outstanding expenses are a liability, hence they are credited.

    Let me give you a simple example,

    Max, a sole proprietor pays 1,00,000 as salary for his employees at the end of every month. Due to the Covid-19 lockdown, he could not pay his employees’ salaries for March month. So the salary for March (1,00,000) will be treated as an outstanding expense. The following entry is made to record outstanding salaries for the year.

    Salary A/c   1,00,000
       To Outstanding Salaries A/c   1,00,000
    (Being salaries outstanding at the end of the year)

    At the end of the year, outstanding salary will be adjusted in the P&L A/c and it will be shown as a Current Liability in the Balance Sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Accounting Terms & Basics

What is accumulated profit meaning?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on November 20, 2021 at 8:43 pm

    Accumulated profit is the amount of profit left after the payment of dividends to the shareholders. It is also known as retained earnings. It is the profit that is not distributed as dividends to shareholders, hence called retained earnings. This accumulated profit is an important source of internalRead more

    Accumulated profit is the amount of profit left after the payment of dividends to the shareholders. It is also known as retained earnings. It is the profit that is not distributed as dividends to shareholders, hence called retained earnings. This accumulated profit is an important source of internal finance for a company. Accumulated profit or retained earnings can be ascertained using the following formula:

    Accumulated profit = Opening balance of accumulated profit + Net Profit/Loss (loss being in the negative figure) – Dividend paid

    Accumulated profit can be put to the following uses:

    • To reinvest into the business in form of capital assets or working capital.
    • To repay the debt of the company.
    • To pay dividends in future.
    • To set off the net loss made by the company.

    Accumulated profit and reserves are often considered the same. But in substance, they are not. The reserves are actually part of the accumulated profit, but the converse is not true. They are created by transferring amounts from the accumulated profit. While reserves are created for purpose of strengthening the financial foundation of a firm, the accumulated profit’s main purpose is to make reinvest in the business to increase its growth.

    The amount of accumulated profits depends upon the retention ratio and dividend payout ratio of a company.  The retention ratio is the opposite of the dividend payout ratio.

    The formula of dividend pay-out ratio = Dividend payable/Net Income

    And retention ratio = 1 – (Dividend payable/Net Income)

    If the retention ratio is more than the dividend payout ratio, the accumulated profit remains positive.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

Can you show a revaluation account example?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 2, 2021 at 8:05 am
    This answer was edited.

    Yes, sure! But lets us first understand what a revaluation account is. A revaluation account is prepared to recognise the change in the book value of assets and liabilities of an entity. These changes happen when assets and liabilities are revalued to present their fair value. It is a nominal accounRead more

    Yes, sure! But lets us first understand what a revaluation account is.

    A revaluation account is prepared to recognise the change in the book value of assets and liabilities of an entity. These changes happen when assets and liabilities are revalued to present their fair value.

    It is a nominal account because it represents gain or loss in value of assets and liabilities. However such gain or loss is unrealised because the assets and liabilities are not sold or discharged.

    After revaluation of assets and liabilities, the balance of the revaluation account can be debit or credit. The debit balance means ‘loss on revaluation’ and credit balance means ‘gain on revaluation’.

    The balance of revaluation is transferred to the capital account.

    Journal Entries related to Revaluation Account

     1. Increase in value of an asset upon revaluation:

    Asset A/c Dr. Amt
    To Revaluation A/c Cr. Amt
    (Being asset value increased upon revaluation)

    2. Decrease in value of an asset upon revaluation:

    Revaluation A/c Dr. Amt
    To Asset A/c Cr. Amt
    (Being asset value decreased upon revaluation)

    3. Increase in value of liabilities upon revaluation:

    Revaluation A/c Dr. Amt
    To Liabilities A/c Cr. Amt
    (Being liabilities value increased upon revaluation)

    4. Decrease in value of liabilities upon revaluation:

    Liabilities A/c Dr. Amt
    To Revaluation A/c Cr. Amt
    (Being liabilities value decreased upon revaluation)

    5. Transfer or distribution of the balance of revaluation account

    Revaluation A/c Dr. Amt
    To Capital/ Partners’ capital  A/c Cr. Amt
    (Being profit on revaluation transferred to capital account.

    or

    Capital/ Partners’ capital  A/c Dr. Amt
    To Revaluation A/c Cr. Amt
    (Being loss on revaluation transferred to capital account.

    Numerical example

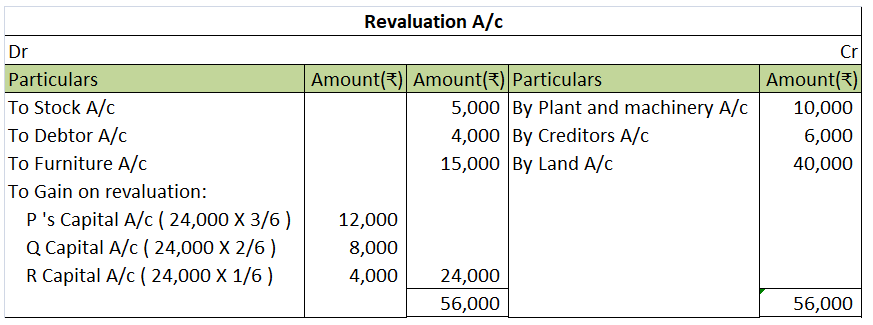
    P, Q and R are partners of the firm ‘PQR Trading’. They share profits and losses in the ratio 3:2:1. On 1st May 20X1, they decided to admit S for 1/6th share in profits and losses of the firm. Upon the revaluation:

    • Plant and machinery increased from Rs 1,20,000 to Rs. 1,30,000
    • The stock decreased by Rs 5000
    • Debtors and creditors both decreased by Rs 4,000 and Rs 6,000 respectively.
    • Furniture decreased from Rs 25,000 to Rs 10,000
    • Land increased by Rs 40,000.

    Let’s prepare the revaluation account.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Pooja_Parikh
Pooja_Parikh
In: 1. Financial Accounting > Depreciation & Amortization

What is furniture depreciation rate?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 17, 2021 at 8:51 pm
    This answer was edited.

    Depreciation is an accounting method that is used to write off the cost of an asset. The company must record depreciation in the profit and loss account. It is done so that the cost of an asset can be realised over the years rather than one single year. Furniture is an important asset for a businessRead more

    Depreciation is an accounting method that is used to write off the cost of an asset. The company must record depreciation in the profit and loss account. It is done so that the cost of an asset can be realised over the years rather than one single year.

    Furniture is an important asset for a business. As per the Income Tax Act, the rate of depreciation for furniture and fittings is 10%. However, for accounting purposes, the company is free to set its own rate.

    JOURNAL ENTRY

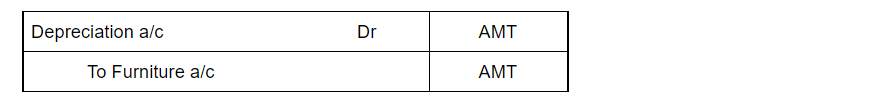
    Journal entry for depreciation of furniture is:

    Here, depreciation is debited since it is an expense and as per the rules of accounting, “increase in expenses are debited”. Furniture is credited because a “ decrease in assets is credited”, and the value of furniture is reducing.

    TYPES OF DEPRECIATION

    Furniture can be depreciated in any of the following ways:

    • Straight-Line Method – It is calculated by finding the difference between the cost of the asset and its expected salvage value, and the result is divided by the number of years the asset is expected to be used.
    • Diminishing Value Method – It is calculated by charging a fixed percentage on the book value of the asset. Since the book value keeps on reducing, it is called the diminishing value method.
    • Units of Production

    For accounting purposes, the two many methods used for depreciating furniture is the straight-line method and the diminishing value method. However, for tax purposes, they are combined into a block of furniture, where the purchase of new furniture is added and the sale of furniture is subtracted and the resulting amount is depreciated by 10% based on the written downvalue method.

    EXAMPLE

    If a company buys furniture worth Rs 30,000 and charges depreciation of 10%, then by straight-line method, Rs 3,000 would be depreciated every year for 10 years.

    Now if the company decided to use the diminishing value method (or written down value method), then Rs 3,000 (30,000 x 10%) would be depreciated in the first year, and in the second year, the book value of the furniture would be Rs 27,000 (30,000-3,000). Hence depreciation for the second year would be Rs 2,700 (27,000 x 10%) and so on.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.