Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What is zero working capital?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 30, 2021 at 7:47 pm

    Working capital is defined as the difference between current assets and current liabilities of a business. Current assets include cash, debtors and stock whereas current liabilities include creditors and short term loans etc. FORMULA Current Assets - Current Liabilities = Working Capital Zero workinRead more

    Working capital is defined as the difference between current assets and current liabilities of a business. Current assets include cash, debtors and stock whereas current liabilities include creditors and short term loans etc.

    FORMULA

    Current Assets – Current Liabilities = Working Capital

    Zero working capital is when a company has the exact same amount of current assets and current liabilities. When both are equal, the difference becomes zero and hence the name, Zero working capital. Working Capital may be positive or negative. When current assets exceed current liabilities, it shows positive working capital and when current liabilities exceed current assets, it shows negative working capital.

    Zero working capital can be operated by adopting demand-based production. In this method, the business only produces units as and when they are ordered by the customers. Through this method, all stocks of finished goods will be eliminated. Also, raw material is only ordered based on the amount of demand.

    This reduces the investment in working capital and thus the investment in long term assets can increase. The company can also use the funds for other purposes like growth or new opportunities.

    EXAMPLE

    Suppose a company has Inventory worth Rs 3,000, Debtors worth Rs 4,000 and cash worth Rs 2,000. The creditors of the company are Rs 6,000 and short term borrowings are Rs 3,000.

    Now, total assets = Rs 9,000 ( 3,000 + 4,000 + 2,000)
    And total liabilities = Rs 9,000 ( 6,000 + 3,000)
    Therefore, working capital = 9,000 – 9,000 = 0

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Miscellaneous

Are brands intangible assets?

  • 1 Answer
  • 0 Followers
Answer
  1. Saurav
    Added an answer on November 22, 2023 at 7:33 am

    Brands can be considered as an Intangible asset as they are a long-term investment done by the company and it gives benefit to an entity in future periods. Like any other intangible asset, brands require long-term investment and will pay over time. Like any other asset, these brands can be bought anRead more

    Brands can be considered as an Intangible asset as they are a long-term investment done by the company and it gives benefit to an entity in future periods.

    Like any other intangible asset, brands require long-term investment and will pay over time. Like any other asset, these brands can be bought and sold. Brands are best used when they serve the vision and mission of the company.

    So, we can definitely consider an organization brand as an intangible as it is expected to increase sales volume in the future period.

    Further, we can understand both terms to get a deep understanding-


    BRAND

    Brand means a product, or service which has a unique identification and can be distinct from other products in the market. Branding is a process by which expenditure is incurred by an entity to create awareness towards the product in the customer’s eyes.

    For example- Maggie, Coca-Cola, BMW

    Brands can be created through these elements-

    • Design
    • Packaging
    • Advertisement


    INTANGIBLE ASSETS

    Intangible asset are assets that can’t be seen or touched but the benefit of it occur in future periods for the entity. Even though intangible assets have no physical form but their benefits will accrue in future years. Businesses commonly hold intangible assets. Intangible assets can be further bifurcated in

    Definite– Intangible assets that stay and give benefit for a limited or specific period of time covered under this

    For example- An agreement is entered with an entity to patent a product for 5 years so this will stay for a definite period only

    Indefinite– Intangible assets that stay and  give benefit for an unlimited  period of time covered under this

    For example- A brand which is made by an entity will stay for an indefinite period

    Intangible assets can be in various forms these are the following –

    Trademark– A trademark is a sign, design, and expression that distinguish the company’s product or services from other company. Trademark is considered an Intellectual Property Right.

    Goodwill– Goodwill refers to the value of the company that the company gets from its brand, customer base, and brand Reputation associated with its intellectual property.

    Patents– A patent refers to a right reserved for a product exclusively by a person or entity. Under this the right of such making of the product gets reserved by the company and other person or entity can’t make this product.

    Copyright– Copyright refers to an intellectual property right that protects the work of the original owner from being copied by some other person.

    Brand– Brand means a product, or service that has a unique identification and can be distinct from other products in market

    So, we can definitely consider that brand is a subpart of an intangible asset and can be considered as an intangible asset as it also can’t be touched or seen. Still, its benefit will accrue till future time. These both help an entity to grow its business till the future

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of “Contra” in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 25, 2021 at 4:25 pm
    This answer was edited.

    The term ‘contra’ means opposite or against. In financial accounting, we encounter the term ‘contra’ in: Contra accounts Contra entries The meaning of contra in the above mention terms is also the same as their general meaning. Contra accounts mean the account which is opposite of the account it corRead more

    The term ‘contra’ means opposite or against. In financial accounting, we encounter the term ‘contra’ in:

    • Contra accounts
    • Contra entries

    The meaning of contra in the above mention terms is also the same as their general meaning. Contra accounts mean the account which is opposite of the account it corresponds to.

    Contra entries are entries of the debit and credit aspects related to the same parent account.  Let’s discuss them in detail.

    Contra accounts

    Any account which is created with the purpose of reducing or offsetting the balance of another account is known as a contra account.

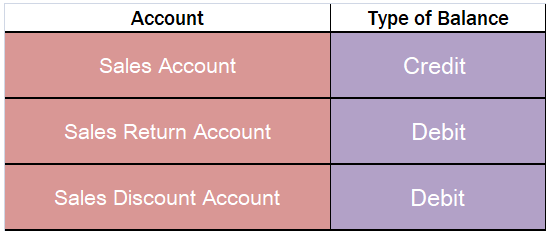
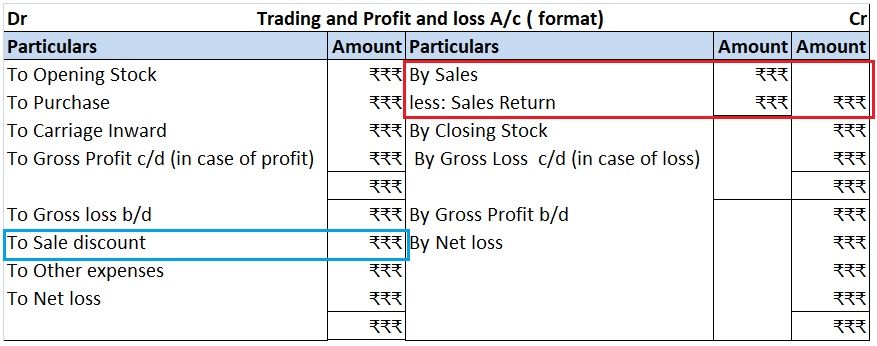
    A contra account is just the opposite of the account to which it relates. The most common examples are the sales discount account and sales return account which is the contra account of the sales account.  They are just the opposite of the sales accounts.

    Contra Entries

    Contra entries refer to the entries which show the movement of the amount within the same parent account. Here, the debit and credit entry is posted on the debit and credit side respectively of a single parent account.  Mainly, contra entries are the entries involving cash and bank accounts.

    The following transactions are recorded as contra entries:

    • Cash to Bank transactions: Deposit of cash into the bank account by the entity.
    • Bank to Cash transactions: Withdrawal of cash from the bank.
    • Cash to cash transactions: Transfer of cash to the petty cash account.
    • Bank to Bank transactions: Transfer of amounts from one bank account to other bank accounts of the same entity.

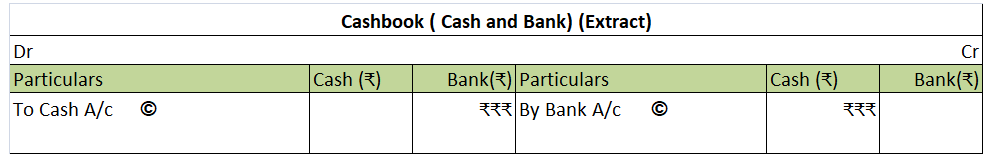
    Contra entries are marked by the letter ‘C’ beside the postings in the ledger. Deposit of cash in to bank will be posted in cashbook as below:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Journal Entries

What is the journal entry for asset purchase?

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on August 4, 2021 at 4:31 pm
    This answer was edited.

    The journal entry for asset purchase is- Particulars Amount Amount Asset A/c                                                             Dr $$$      To  Bank A/c $$$ According to the Modern Approach for Assets Account: When there is an increase in the Asset, it is ‘Debited’. When there is a decreaseRead more

    The journal entry for asset purchase is-

    Particulars Amount Amount
    Asset A/c                                                             Dr $$$
         To  Bank A/c $$$

    According to the Modern Approach for Assets Account:

    • When there is an increase in the Asset, it is ‘Debited’.
    • When there is a decrease in the Asset, it is ‘Credited’.


    So the journal entry here is about the purchase of an asset and since there is an increase in Asset, the assets account will be debited as per the modern rule and due to the decrease of cash in the bank account, it will be credited.

    For Example, Richard purchased furniture worth Rs 6,000 for his business.

    I will try to explain it with the help of steps.

    Step 1: To identify the account heads.

    In this transaction, two accounts are involved, i.e. Furniture A/c and Bank A/c as Richard has acquired the furniture paying a certain amount.

    Step 2: To Classify the account heads.

    According to the modern approach: Furniture A/c is an Asset account and Bank A/c is also an Asset account.

    According to the traditional approach: Furniture A/c is a Real account and Bank A/c is also a Real account.

    Step 3: Application of Rules for Debit and Credit:

    According to the modern approach: As asset increases because Furniture has been bought, ‘Furniture A/c’ will be debited. (Rule – increase in Asset is debited).

    Bank account is also an Asset account. As the asset is in the form of cash decreases because the amount has been paid by cash or cheque, Bank account will be credited. (Rule – decrease in Asset is credited).

    According to the traditional approach: Furniture A/c is a Real account and Bank is also a Real account, for which the rule to be applied is ‘Debit what comes in and Credit what goes out’. Furniture being asset comes in the business, so Furniture A/c will be debited and as cash goes out Bank A/c will be credited.

    So from the above explanation, the Journal Entry will be-

    Particulars Amount Amount
    Furniture A/c                                                      Dr 6,000
         To  Bank A/c 6,000


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Journal Entries

What are 10 examples of journal entries?

  • 1 Answer
  • 0 Followers
Answer
  1. A_Team (MBA - Finance Student) ISB College
    Added an answer on December 13, 2022 at 5:05 am
    This answer was edited.

    Here are 10 examples of accounting entries: A company purchases $500 worth of office supplies on credit from a supplier. Office supplies expense account would be debited Accounts payable would be credited   A firm receives $1,000 in cash from a customer for services rendered. In this case, CashRead more

    Here are 10 examples of accounting entries:

    • A company purchases $500 worth of office supplies on credit from a supplier.
      • Office supplies expense account would be debited
      • Accounts payable would be credited


    • A firm receives $1,000 in cash from a customer for services rendered. In this case,
      • Cash account would be debited
      • Service revenue account would be credited


    • A business pays $250 in salaries to its employees.
      • A debit would be made to the salaries expense account
      • A credit would be made to the cash account


    • A business borrows $5,000 from a bank and receives the funds as a loan. The entry would be,
      • A debit to the bank account
      • A credit to the loan payable account


    • A company sells $800 worth of inventory to a customer for cash.
      • The entry would be a debit to the cash account
      • A credit to the sales revenue account


    • A firm purchases $3,000 worth of equipment on credit from a supplier.
      • The entry would be a debit to the equipment account
      • A credit to the supplier’s account


    • A company incurs $500 in advertising expenses for a new marketing campaign (cash).
      • The entry would be a debit to the advertising expense account
      • A credit to the cash account


    • A firm collects $1,200 from a customer. The entry would be,
      • A debit to the cash account
      • A credit to the customer’s account


    • A business pays $700 in rent for its office space. The entry would be,
      • A debit to the rent expense account
      • A credit to the cash account


    • An organization pays off a $2,000 loan to the bank. The entry would be,
      • A debit to the loan payable account
      • A credit the cash account


    I also found a long list of example journal entries and a free PDF to download here.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is a contra revenue account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 7, 2021 at 7:55 pm
    This answer was edited.

    The term ‘contra’ means  'opposite'. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance. The purpose of the contra revenue account is to ascertain the actuaRead more

    The term ‘contra’ means  ‘opposite’. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance.

    The purpose of the contra revenue account is to ascertain the actual amount of sales and record the items which have reduced the sales.

    These are the contra revenue accounts commonly seen in businesses:

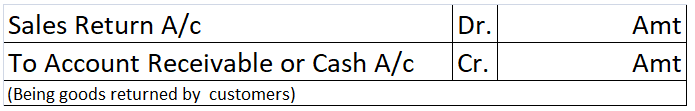
    • Sales return account: This account records the amount of goods sold returned by customers. The journal entry for recording sale return is as follow:

    The total sales return is deducted from the sales in the balance sheet. Though being opposite of the sales account, the sale return account is not an expense account. It is considered an indirect loss as it reduces sales.

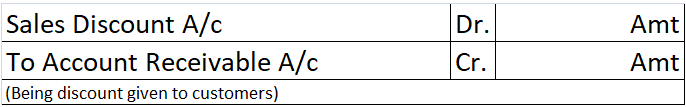
    • Sale Discount account: This account records the amount of discount allowed to customers. The journal entry for recording sale discounts is as follows:

    Sales discount is an expense hence it is debited to the profit and loss account.

    Sales returns and sales discounts are shown in the trading and profit and loss account in the following manner:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Miscellaneous

What are some examples of revenue receipts and capital receipts?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 3, 2021 at 2:41 pm
    This answer was edited.

    Firstly, let’s understand the meaning of both terms. Revenue receipts:  The term 'revenue' suggests these are the amounts received by a business due to its operating activities. These receipts arise in a recurring manner in a business. Such receipts don’t affect the balance sheet. They are shown inRead more

    Firstly, let’s understand the meaning of both terms.

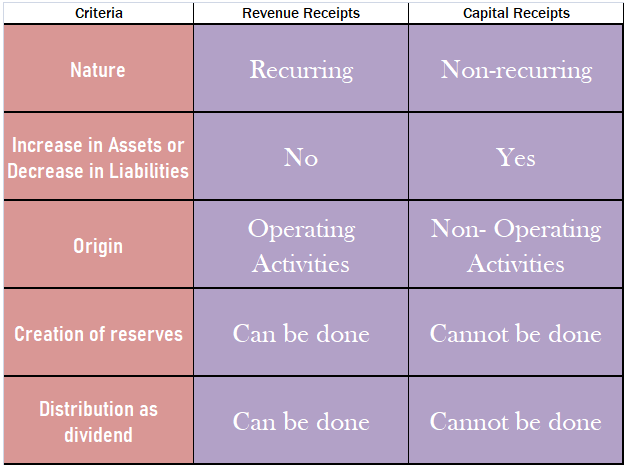
    Revenue receipts:  The term ‘revenue‘ suggests these are the amounts received by a business due to its operating activities. These receipts arise in a recurring manner in a business. Such receipts don’t affect the balance sheet. They are shown in the statement of profit or loss. Such receipts are essential for the survival of the business.

    Examples of revenue receipts are as follows:

    • Proceeds from the sale of goods.
    • Proceeds from the provision of services
    • Rent received
    • Interest received from deposits in banks or financial institutions
    • Discount received from creditors (shown in the debit side of P/L A/c)

    Capital receipts: The term ‘capital’ that such receipts are do not arise due to operating activities, hence not shown in the Profit and loss statement.  These are the money received by a business when they sell any asset or undertake any liability. These receipts do not arise in a  recurring manner in a business.  They don’t affect the profit or loss of the business. They are not essential for the survival of the business.

    Examples of capital receipts are as follows:

    • Loan from a bank or financial institution. (Increase in liabilities)
    • Proceeds from the sale of an asset. (decrease in assets)
    • Proceeds from sale of  investments. (decrease in assets)
    • Proceeds from the issue of equity shares. (Increase in liabilities)
    • Proceeds from issue of debentures. (Increase in liabilities)

    I have given a table below for more understanding:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.