


Meaning A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value. The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the mainRead more
Meaning
A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value.
The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the main ledger account. This is a conservative approach to use valuation accounts to present the value of the concerned asset or liability at a reduced value.
The most common example of a valuation account is the ‘Provision for doubtful debts account’. It appears in the balance sheet as a reduction from the debtors’ accounts. Also when the amount is transferred to this provision, it appears in the statement of profit and loss account. But it doesn’t appear in the debtors’ account ledger.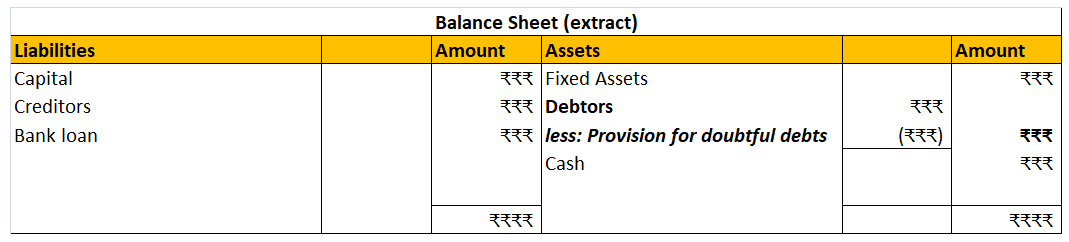
Treatment
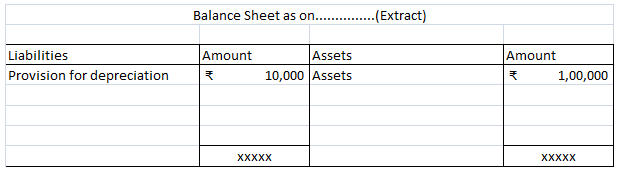
A valuation account appears only in the balance sheet. Sometimes, it also appears in the profit and loss account when any amount is transferred to it.
Valuation accounts are only used in accrual accounting. They cannot be used in cash-based accounting as there is no flow of cash related to valuation accounts.
They have a balance opposite of their paired accounts i.e. if their paired account is an asset then they will have a credit balance and if it is a liability then they will have a debit balance.
Other Examples of valuation accounts are as follows:
- Provision for doubtful debts (offsets the account receivables or debtors’ account)
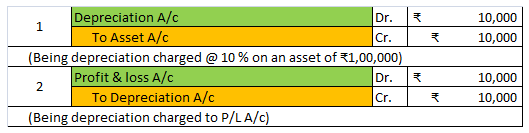
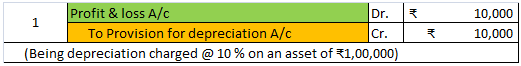
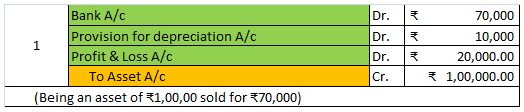
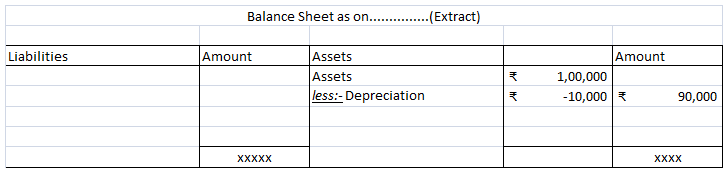
- Accumulated depreciation (report the assets net of depreciation)
- Discount on bonds payable (reduces the reporting balance of bond payable account)





A Capital Account is an account that shows the owner's equity in the firm and a Partner's Capital Account is an account that shows the partner's equity in a partnership firm. Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are: CapitalRead more
A Capital Account is an account that shows the owner’s equity in the firm and a Partner’s Capital Account is an account that shows the partner’s equity in a partnership firm.
Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are:
When partners are given interest on their capital contribution in the firm, it is called on Interest on Capital.
In case the partnership firm does not have a Partnership Deed, the Partnership Act does not include a provision for Interest on Capital. However, if the partners want they can mutually decide the rate of Interest on Capital.
Interest on Capital is calculated on the opening capital of the partners and is only allowed when the firm makes a profit, that is, in case a firm incurs losses, it cannot allow Interest on Capital to its partners.
Example:
In a partnership firm, there are two partners A and B, and their capital contribution is Rs 10,000 and 20,000 respectively. Interest on capital is @ 10% p.a. The Interest on Capital for both the partners is:
Partner A- 10,000 * 10/100 = 1,000
Partner B- 20,000 * 10/100 = 2,000
The journal entry for Interest on Capital is an adjusting entry and is shown as:
See less