Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Bonnie
BonnieCurious
In: 1. Financial Accounting > Financial Statements

What is the primary objective of cash flow statement?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on December 1, 2021 at 2:09 pm
    This answer was edited.

    A cash flow statement is a statement showing the inflow and outflow of cash and cash equivalents during a financial year. Cash Flow Statements along with Income statements and Balance Sheet are the most important financial statements for a company. The Cash Flow Statement provides a picture to the sRead more

    A cash flow statement is a statement showing the inflow and outflow of cash and cash equivalents during a financial year. Cash Flow Statements along with Income statements and Balance Sheet are the most important financial statements for a company.

    The Cash Flow Statement provides a picture to the shareholders, government, and the public of how the company manages its obligations and fund its operations. It is a crucial measure to determine the financial health of a company.

    The Cash Flow Statement is created from the Income Statement and the Balance Sheet. While Income Statement shows money engaged in various transactions during the year, the Balance Sheet presents information about the opening and closing balances.

    The primary objective of a Cash Flow Statement is to present a record of inflow and outflow of cash, cash equivalents, and marketable securities through various activities of a company.

    Various activities in a company can be broadly classified into three parts or heads:

    • Cash Flow from Operating Activities: it represents how money from regular business activities is derived and spent. It includes Net Profit from Income Statement after adjusting for tax and extra-ordinary activities. Items included in Operating Activities are adjustments in Working Capital. If current liabilities are paid or current assets are bought it means outflow of cash, hence it is deducted and if liabilities are increased or assets are sold it means the inflow of cash, hence it is added. Operating Activities take into account taxation, dividend, depreciation, and other adjustments.
    • Cash Flow from Investing Activities: it represents aggregate inflow or outflow of cash due to various investments activities that the company was engaged in. Purchase and sale of non-current assets like fixed assets and long-term investments are considered under this head. If there is an investment made, it means outflow of cash, hence it is deducted and if there is an investment sold it means the inflow of cash, and hence it is added.
    • Cash Flow from Financing Activities: it represents the activities that are used to finance a company’s operations, like, issue of cash or debentures, paying dividends and interest, long-term borrowing taken by a company, etc. If these are paid, it means outflow of cash and is hence deducted and if they are acquired, it means the inflow of cash and hence ae added.

    Cash Flow Statements also present a picture of the liquidity of the company and are therefore used by the management of a company to take decisions with the help of the right information.

    Cash Flow Statements are a great source of comparison between a company’s last year’s performance to its current year or with other companies in the same industry and hence, helps shareholders and potential investors to make the right decisions.

    It also helps to differentiate between non-cash and cash items; incomes and expenditures are divided into separate heads.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

What are biological assets? What is their accounting treatment?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 12, 2025 at 7:40 am

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture. IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity. Agricultural Activity- It is the management of biological transformatRead more

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture.

    IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity.

    • Agricultural Activity- It is the management of biological transformation by an entity and measuring the change in the quality and quantity of biological assets.
    • Biological Transformation- It comprises the process of growth, degeneration, production and procreation that cause qualitative or quantitative changes in a biological asset
    • Biological Asset – They are living plants or animals owned by an entity
    • Agricultural Produce- It is the harvested / detached product of the entity’s biological asset.

    IAS 41 does not apply to

    • Agricultural land
    • Intangible assets related to agricultural activity
    • Products that are the result of processing after the point of harvest, for example, yarn, carpet, rubber, wine, etc
    • The land on which the biological assets grow, regenerate, degenerate.


    Biological Assets

    Definition

    Biological assets are living plants or animals that go through biological transformation, owned by an entity to prepare agricultural produce for the purpose of agricultural activities only.

    Living plants include plants that are consumable within 1 year and are harvested. It also includes plants that are used for lumbering and wood-cutting activities.

    Examples

    Examples of biological assets are:

    Sheep, pigs, poultry, beef cattle, fish, dairy cows, plants for harvest etc

    Importance

    • Farming: They are key to agriculture and food production.
    • Income: They generate substantial income for businesses in industries such as vineyards, livestock, silviculture, etc.
    • Sustainability: Properly managing them helps the environment.


    Accounting & Presentation

    Recognition

    Under IAS 41 biological assets are recognised when

    • The business must have ownership over them from a past event.
    • The future economic benefits are expected to flow to the business from their ownership.
    • The cost or fair value of the asset can be measured reliably.

    Agricultural produce is recognised

    • It is recognised at the point of harvest or detachment.

    Agricultural produce is derecognised when

    • They enter the trading.
    • Enters the production process.

    Measurement

    • Biological assets are measured on initial recognition and at each balance sheet date at their fair value less costs to sell.
    • Costs to sell are incremental costs incurred in selling the asset.
    • Agricultural produce is measured at the point of harvest, at fair value less costs to sell at the point of harvest.
    • Agricultural produce after the point of harvest/ detachment is transferred and treated under the IAS 2 Inventory

    Gains & Losses

    • Gains and losses arising from the initial recognition of biological assets are reported in the statement of profit and loss.
    • The change in fair value less costs to sell of a biological asset between balance sheet dates is reported as gain or loss in the statement of profit and loss.
    • A gain or loss arising on initial recognition of agricultural produce at fair value less selling costs is included in profit or loss for the period in which it arises.

    Treatment

    • The sale of agricultural produce is treated as revenue in the statement of profit and loss.
    • Agricultural produce to be harvested for more than 12 months, livestock to be held for more than 12 months and trees cultivated for lumber are recorded as Biological assets under the Non-current assets head in the balance sheet.
    • Agricultural produce to be harvested within 12 months, livestock to be slaughtered within 12 months and annual crops like wheat, and maize are recorded as Biological assets under the head Current assets in the balance sheet.
    • Inventories produced from agricultural produce are presented as Inventory under the head Current assets in the balance sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation on car as per income tax act?

  • 1 Answer
  • 0 Followers
Answer
  1. Radha M.Com, NET
    Added an answer on July 22, 2021 at 5:48 pm
    This answer was edited.

    The rate of depreciation on a car as per the Income Tax Act depends upon the purpose for which it has been purchased and the year on which it was acquired. As per the Income Tax Act, cars come under the Plant and Machinery block of assets. The Act classifies cars into two categories, Group 1 - MotorRead more

    The rate of depreciation on a car as per the Income Tax Act depends upon the purpose for which it has been purchased and the year on which it was acquired.

    As per the Income Tax Act, cars come under the Plant and Machinery block of assets.

    The Act classifies cars into two categories,

    • Group 1 – Motor cars other than those used in the business of running them on hire.
    • Group 2 – Motor taxis used in the business of running them on hire.


    Group 1:

    1. If the motor car is acquired and put to use on or after 23rd August 2019 but before 1st April 2020, then the rate applicable is 30%.
    2. If the motor car is acquired and put to use on or after 1st April 1990, then the rate applicable is 15%. (All the cars which are not covered under the category (1) comes under this category.)


    Group 2:

    1. If the motor taxi is acquired and put to use on or after 23rd August 2019 but before 1st April 2020, then the rate applicable is 45%.
    2. The rate applicable for motor taxis not covered under category (1) is 30%.


    Here is a summarised version of the rates applicable to cars,


    The rates can also be found on the Income Tax India website.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Journal Entries

What is the journal entry for bad debts?

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on August 9, 2021 at 10:24 am
    This answer was edited.

    Bad Debt is the amount that is irrecoverable from the debtors. It is the portion of the receivables. It includes two accounts “Bad Debts A/c” and “Debtors A/c or Accounts Receivable A/c”. The amount cannot be recovered by the debtor for reasons like the debtor is no longer in the position to pay offRead more

    Bad Debt is the amount that is irrecoverable from the debtors. It is the portion of the receivables. It includes two accounts “Bad Debts A/c” and “Debtors A/c or Accounts Receivable A/c”.

    The amount cannot be recovered by the debtor for reasons like the debtor is no longer in the position to pay off the debt or has become insolvent.

    There are two methods to write off bad debts:

    1. Direct Method
    2. Allowance for Doubtful Debts


    1. Direct Method: In this method, the amount of bad debts is directly deducted from the total receivables and the second effect is transferred to the debit side of Profit and Loss A/c as an expense.

    The journal entry for bad debts as per modern rules of accounting is as follows:

    Bad Debts A/c Debit Increase in expenses
          To Accounts Receivable A/c Credit Decrease in assets
    (Being bad debts written off )


    Journal entry for transferring bad debts to profit and loss account:

    Profit and Loss A/c Debit
          To Bad Debts A/c Credit
    (Being bad debts transferred to profit and loss a/c )


    For example, A Ltd had a total receivable of Rs.2,50,000 and bad debts for the period amounted to Rs.10,000.

    Here, the journal entries will be:

    Bad Debts A/c Debit 10,000
          To Accounts Receivable A/c Credit 10,000
    (Being bad debts written off )


    Profit and Loss A/c Debit 10,000
          To Bad Debts A/c Credit 10,000
    (Being bad debts transferred to profit and loss a/c )


     2. Allowance for Doubtful Debts:  In this method allowance is the estimation of the debts which is doubtful to be paid. The company creates a reserve for such debts which are uncollectible.

    Firstly, the company will create a reserve which will be based on the accounts receivable. The journal entry will be:

    Bad Debts A/c Debit
          To Allowance for Doubtful Debts A/c Credit
    (Being allowance for doubtful debts created)


    When a specific receivable is uncollectible it will be charged as an expense, and Allowance for Doubtful Debts will be “Debited” and Accounts Receivable will be “Credited”.

    Allowance for Doubtful Debts A/c Debit
                  To Accounts Receivable A/c Credit
    (Being bad debts written off)

    For example, Mr.B sold goods worth Rs.15,000 to Mr.D. He creates an allowance of Rs.15,000 in case Mr.D fails to pay the amount. At the end of the period, Mr.D defaults and does not pay the debt.

    In this case, Mr.B will first record the journal entry for allowance and then will write off Mr.D’s account.

    Bad Debts A/c 15,000
          To Allowance for Doubtful Debts A/c 15,000
    (Being allowance of Rs.10,000 created for doubtful debts)


    Allowance for Doubtful Debts A/c 15,000
                  To Mr.D’s A/c 15,000
    (Being Mr.D’s account written off)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Ledger & Trial Balance

What is the difference between ledger and trial balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on August 21, 2021 at 7:04 am
    This answer was edited.

    The difference between a ledger & a trial balance is as follows: Basis Ledger Trial Balance Meaning Ledger is a book/register in which all the accounts are put together. A Trial Balance is a statement showing the debit and credit balance of all the accounts to ascertain the arithmetical accuracyRead more

    The difference between a ledger & a trial balance is as follows:

    Basis Ledger Trial Balance
    Meaning Ledger is a book/register in which all the accounts are put together. A Trial Balance is a statement showing the debit and credit balance of all the accounts to ascertain the arithmetical accuracy of the books of accounts.
    Basis of preparation Journal is the basis for recording transactions in the ledger. The closing balances of different accounts in the ledger are the basis for preparing the trial balance.
    Objective It is prepared to see the net effect of various transactions affecting a particular account. It is prepared to check the arithmetical accuracy of the books of accounts.
    Format A ledger has four identical columns on the debit and credit sides: 1. Date, 2. Particulars, 3. Journal Folio, 4. Amount. A Trial Balance has five columns: 1. S.No, 2. Name of Accounts, 3. Ledger Folio, 4. Debit Balance, 5. Credit Balance.
    Stage of Recording A ledger is prepared after recording the transactions in the journal. A trial balance is prepared after posting the transactions in the ledger.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Miscellaneous

Give any three examples of revenue?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on July 9, 2021 at 3:35 am
    This answer was edited.

    Revenue also called income is nothing but the income generated by individuals or businesses from the sale of goods or investing capital or assets. Some examples of revenue are as follows:- Sales revenue Dividend received Interest earned Rent received Commission    1. SALES REVENUE Sales revenueRead more

    Revenue also called income is nothing but the income generated by individuals or businesses from the sale of goods or investing capital or assets. Some examples of revenue are as follows:-

    1. Sales revenue
    2. Dividend received
    3. Interest earned
    4. Rent received
    5. Commission


     1. SALES REVENUE

    Sales revenue is the income received by the individual or business by selling its product or provision of services. the words “sale” and “revenue” are used interchangeably to mean the same thing. It is to be noted that revenue does not necessarily mean it has been received in cash, it can be partly in cash or partly on credit also.

    How to calculate sales revenue?

    SALES REVENUE = NO. OF UNITS SOLD * AVERAGE PRICE PER UNIT

    For example:- Amazon sold 4000 units of shirts @ 500 each. Therefore sales revenue for amazon is

    Sales revenue = 4000 * 500

    = 20,00,000

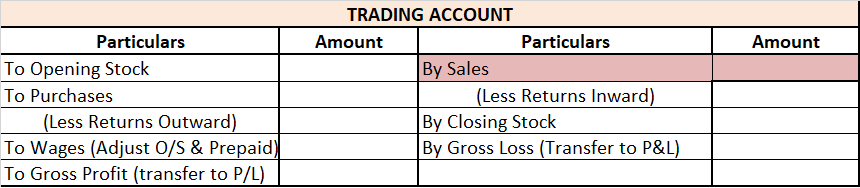
    Treatment of sales revenue in the financial statement, since sales are part of a trading account and appear on the credit side of the trading account.

    2. DIVIDEND RECEIVED

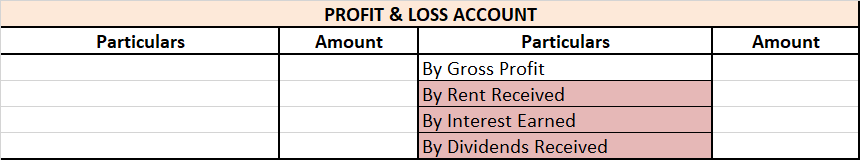
    Naina, this can be explained in simple terms. Suppose you own shares of a company which declares dividend so the dividend received is income for you. Since it does not reduce the assets of a company nor creates a liability it is shown as income and posted on the credit side of profit & loss A/c.

    Let me give you a short example of a dividend received, suppose you own 1000 shares of ABC.ltd. the company at the quarter-end calculate its earnings and decides to declare a dividend of Rs 5 per share. Therefore you would receive 1000* 5 i.e Rs 5000 as dividend income.

    3. INTEREST INCOME EARNED

    Interest income is the earnings the entity receives on any investments made. To be more precise it is money earned by an individual or business for lending their fund either by putting them as deposit in the bank. It is shown on the credit side of the profit & loss A/c.

    A very simple example for interest earned is when a business or an individual deposits money in the bank as savings and decided not to touch it for the coming years then such a depositor will gain interest on such savings by the bank. such type of income so received is treated as interest received and shown as income in the profit & loss A/c.

    3. RENT RECEIVED

    When money is received by the business for exchange of use of assets of the business by the other person, then it will be called rent received. Rent can be received by the business firm in respect of land, building, machinery, etc. As rent received is income for the business firm, it is shown on the credit side of profit & loss A/c.

    For example, X. ltd received Rs 20,000 via cash on one of its properties to Mr. Z. Then rent so received shall be treated as income in the books of ABC. ltd and same shall be treated as income and shown in the profit & loss statement.

    Summarised extract of profit & loss account is shown below for dividend received, Rent received and interest earned.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 1. Financial Accounting > Miscellaneous

Is building a current asset?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 16, 2022 at 9:07 pm
    This answer was edited.

    No, the building is not a current asset. Explanation Current assets are those in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting through normal day-to-day business operations. Examples: Cash and cash equivalent, stock, liquid assets, etRead more

    No, the building is not a current asset.

    Explanation

    Current assets are those in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting through normal day-to-day business operations.

    Examples: Cash and cash equivalent, stock, liquid assets, etc.

    The building is expected to have a valuable life for more than a year and is bought for a longer term by a company. The building is a fixed asset/non-current asset, those assets which are bought by the company for a long term and aren’t supposed to be consumed within just one accounting year.

    In order to understand it more clearly, let’s see the two types of assets in the classification of the assets on the basis of convertibility:

    In the classification of the assets on the basis of their convertibility, they are classified either as current assets or fixed assets. Also referred to as current assets/ non-current assets or short-term/ long-term assets.

    • Current Assets – As explained above, those assets in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting.
    • Fixed Assets – Those assets which are not likely to be converted into cash quickly and are bought by the business for a long term.

    Building in the balance sheet

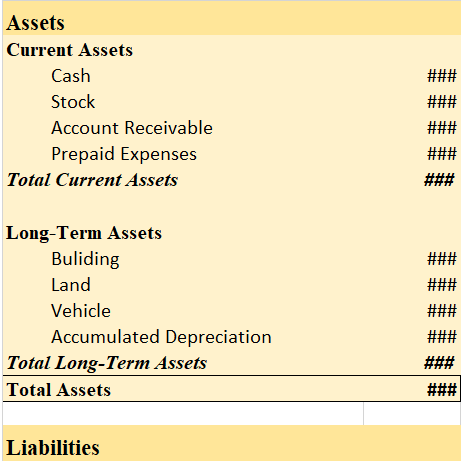
    Let us take a look at the balance sheet’s asset side and see where building and current assets are shown

    Balance Sheet (for the year ending…)


    As we can see, the building is shown on the long-term assets side and not in the current assets.

    Therefore, the building is not a current asset.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.