


Definition The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances. A trial balance is prepared on a particular date and not on a particular period. What does trial balRead more
Definition
The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances.
A trial balance is prepared on a particular date and not on a particular period.
What does trial balance include?
As in each double-entry system, each account has two aspects debit and credit.
Hence the following trial balance includes:
• Debit or credit of the reporting period.
• The amount which is to be debited or credited to each account.
• The account numbers.
• The dates of the reporting period.
• The totaled sums of debits and credits entered during that time.
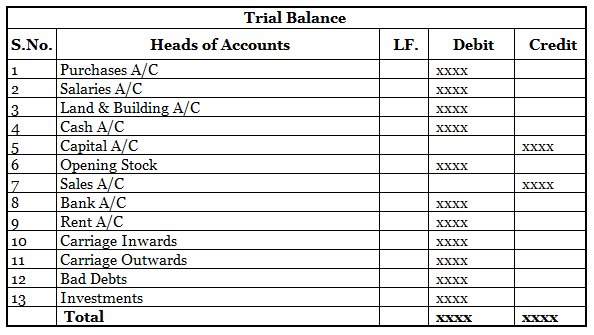
When we prepare a trial balance from the given list of ledger balances, these need to be included which are as follows :
The balance of all
• Assets accounts
• Expenses accounts
• Losses
• Drawings
• Cash and bank balances
Are placed in the debit column of the trial balance.
• The balances of
• liabilities accounts
• income accounts
• profits
• capital
Are placed in the credit column of the trial balance.
Importance
As the trial balance is prepared at the end of the year so it is important for the preparation of financial statements like balance sheets or profit and loss.
The purpose of the trial balance is as follows:
• To verify the arithmetical accuracy of the ledger accounts
This means trial balance indicates that equal debits and credits have been recorded in the ledger accounts.
It enables one to establish whether the posting and other accounting processes have been carried out without any arithmetical errors.
• To help in locating errors
There can be some errors if the trial balance is untallied therefore to get error-free financial statements trial balance is prepared.
• To facilitate the preparation of financial statements
A trial balance helps us to directly prepare the financial statements and then which gives us the right to not look or no need to refer to the ledger accounts.
Structure of trial balance



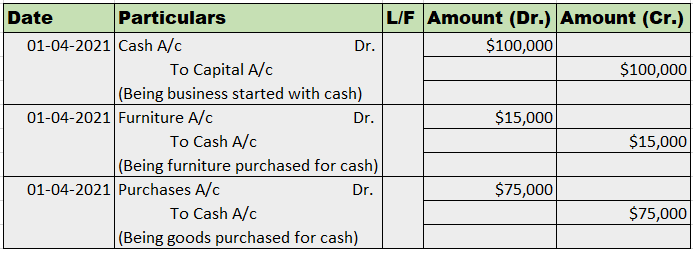
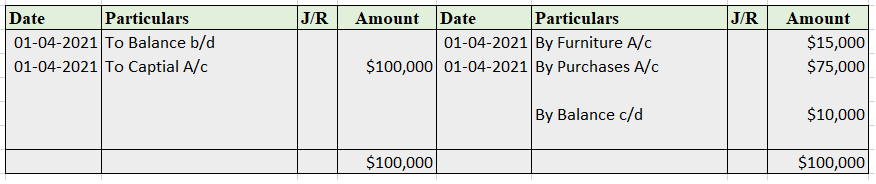
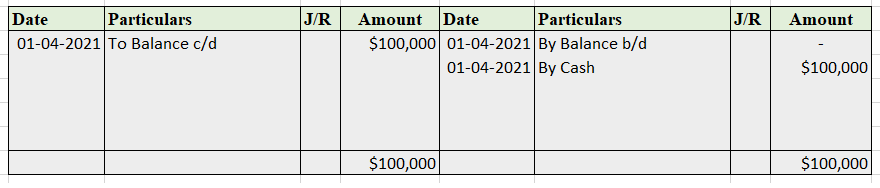
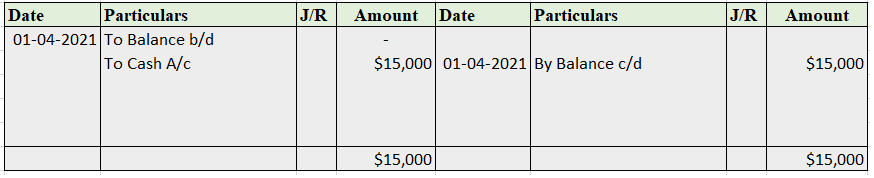

In accounting, sales returns are the goods returned by the customer to the seller. This can be due to goods delivered is damaged or defective. A return can also be due to late delivery, or the wrong items being sent to the buyer. Sales return is a subsidiary book in which all the details are recordeRead more
In accounting, sales returns are the goods returned by the customer to the seller. This can be due to goods delivered is damaged or defective. A return can also be due to late delivery, or the wrong items being sent to the buyer.
Sales return is a subsidiary book in which all the details are recorded for the goods returned which were sold on credit. It is also known as return inwards.
Accounting for Sales Return
Whenever there is a sale return, the seller will debit the sales return account and credit the debtor’s account. The total amount of sales returns is deducted from the gross sales for the period giving the figure for net sales. Debtor’s account is credited because the amount receivable from debtors will reduce.
The sales return is a contra account to the sales.
Format of sales return book:
In the above format, a credit note is a statement prepared by the seller and sent to the buyer. In this statement, all the details are mentioned in respect of the goods sent by the buyer and are an indication that the buyer’s account is credited in respect of the goods received.
For example, Mr. A sold goods to Mr. B costing Rs 50,000 on 1 December. On 5 December, goods amounting to Rs 15,000 were found defective and were returned immediately to Mr. A.
Mr. A will account for this in the following way:
See less