


Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who's ever returning the money is significantly low. Bad debt is a nominal account. A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profitRead more
Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who’s ever returning the money is significantly low. Bad debt is a nominal account.
A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profit or loss. The balances on nominal accounts are normally written off at the end of each financial year. For example, sales A/c, purchases A/c, interest income, loss from the sale of assets etc.
Why are bad debts A/c classified as a nominal account?
First of all, let us understand the other two types of accounts – personal accounts and real accounts.
Personal accounts deal with the records of the business’ transactions with a particular person or entity. For example Mukesh A/c, Mahesh A/c, Reliance A/c, Suresh and Co. A/c etc.
Real accounts deal with transactions and records related to assets. The balance in these accounts is normally carried forward from one period to another. For example “Furniture A/c “, ” Building A/c ” etc.
Now that we have understood the basic definitions of all three types of accounts, we can discuss the reason behind the classification of bad debts as nominal accounts.
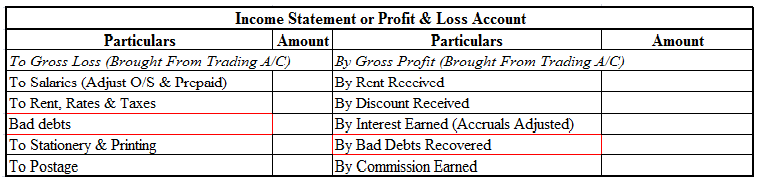
A bad debt is a loss that the company has incurred. It may be due to bankruptcy of customers, customer fraud etc. The company isn’t going to receive that money. The bad debts are written off at the end of the year by transferring them to profit and loss A/c.
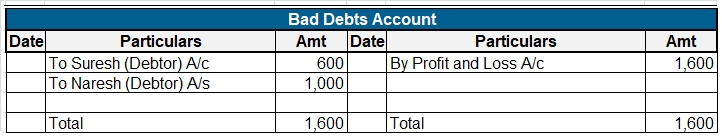
Thus, bad debts relate to loss and are normally not carried forward from one period to another. Hence, they are classified as nominal accounts.
Treatment of Bad Debts
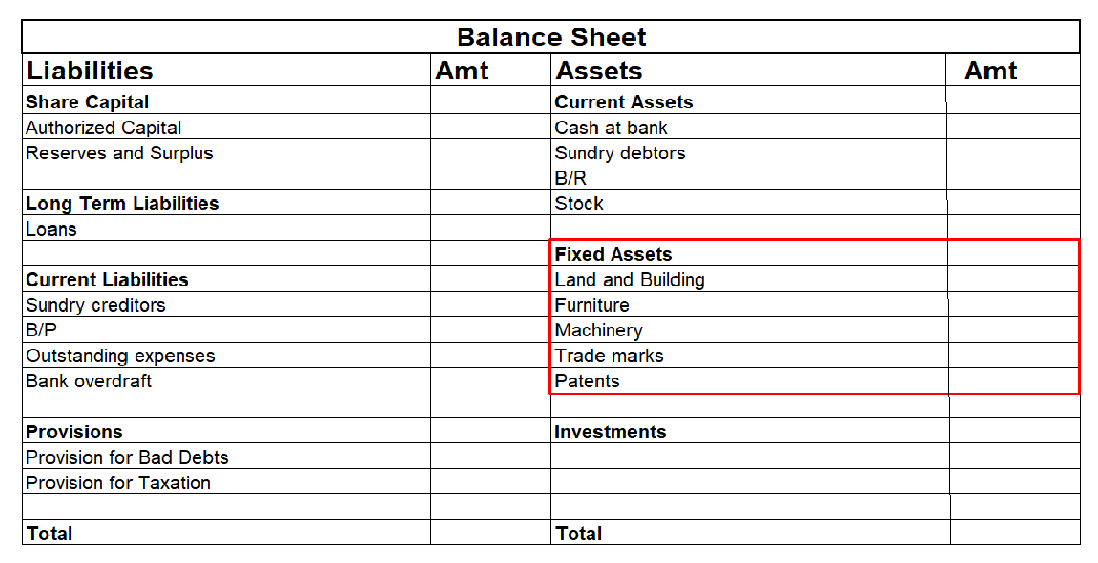
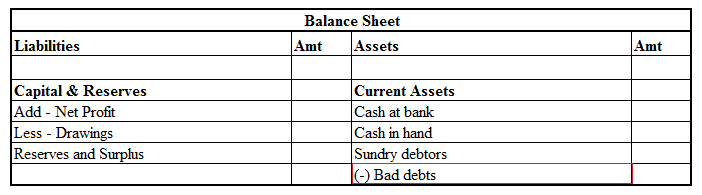
Bad debts are written off at the end of each year by debiting them to the profit and loss A/c. The amount of bad debts is reduced from the amount of debtors that the company has.
A company may also choose to create a provision for bad debts for the balance amount of debtors that the company has after adjusting for bad debts. This provision represents a rough estimate of the amount due to debtors that the business expects to not receive. In other words, it is an estimate of customer bankruptcy that the business expects.
Conclusion
We can conclude that
- There are primarily three types of accounts – real, personal and nominal.
- Bad debts are a nominal account.
- Bad debts is a loss that the business has incurred
- It may be due to bankruptcy of customers, fraud etc
- Bad debts are written off each year by transferring them to the income statement






Definition A limited liability partnership (LLP)is a business vehicle like a partnership that features the partners ‘ liability is limited. Thus, it has elements of partnership and company. Another important feature of LLP is that each partner is not responsible or liable for another partner’s miscoRead more
Definition
A limited liability partnership (LLP)is a business vehicle like a partnership that features the partners ‘ liability is limited. Thus, it has elements of partnership and company.
Another important feature of LLP is that each partner is not responsible or liable for another partner’s misconduct or negligence.
LLP as constituted in INDIA:
The limited liability partnership act, 2008 came into effect on 31st march, 2009. LLP is different from a partnership as it operates like a partnership, but in an LLP each partner is protected from personal liability, except to the extent of his capital contribution in the LLP.
• LLP is subject to income tax like any other partnership firm.
• A partner is not liable for independent or unauthorized actions of other partners, thus allowing individual partners to be shielded from joint liability created by another partner‘s wrongful business decisions or misconduct.
• LLP is a body corporate and legal entity separate from its partners. It has perpetual succession like a limited liability company.
Indian partnership act 1932 is not applicable to LLPs and also the limit on the number of partners in an LLP is not applicable, unlike an ordinary partnership firm where the maximum number of partners cannot exceed the number specified under SEC 464 of Companies Act 2013, which at present is 50.
The LLP Act, 2008 specifies that a least one of the partners in the LLP is a citizen of India and an Indian national.
• The Registrar Of Companies ( ROC) is authorized to register and control LLPs.
Characteristics
• Separate legal entity :
Like a company, LLP also has a separate legal entity. Therefore partners and LLP are distinct from each other, like a company where the company has a legal entity separate from its shareholders.
• Minimum capital :
LLP is not required to maintain minimum capital. Thus partners in LLP decide how much capital will be contributed by each partner.
• The Minimum number of members :
An LLP can be established with at least two members who shall also be the designated partners and shall have Director Identification Number (DIN).
There is no limit on the maximum number of partners. Members other than designated partners are required to have DIN.
• Audit is not mandatory :
All companies, whether private or public, are required to get their accounts audited. However, an audit of LLP‘s books of accounts is not mandatory except :
• If the contribution of the LLP exceeds Rs 25 lakhs: or
• If the annual turnover of the LLP exceeds Rs 40 lakhs.
See less