


Specimen of Ledger account This is the specimen of a ledger account. J.F. here represents the journal folio. A Ledger account is an account that consists of all the business transactions that take place during the current financial year. For Example, cash, bank, machinery, A/c receivable account, etRead more
Specimen of Ledger account

This is the specimen of a ledger account. J.F. here represents the journal folio.
A Ledger account is an account that consists of all the business transactions that take place during the current financial year.
For Example, cash, bank, machinery, A/c receivable account, etc.
After the financial data is recorded in the Journal. It is then classified according to the nature of accounts viz. Asset, liability, expenses, revenue, and capital to be posted in the ledger account.
With this head, the identification as to whether the opening balance will come under the debit side or the credit side is done.
The table below would help to understand the concept of opening balance in the ledger.
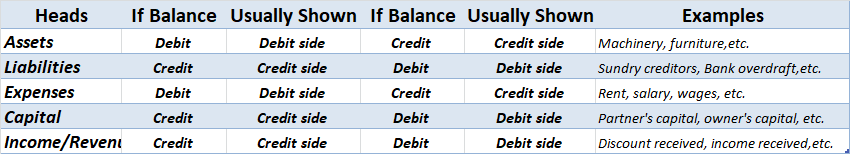
For further clarification of the concept let me give you a practical example.
Suppose, a manufacturing firm Amul purchased machinery for, say, Rs 2,50,000. The installation charges were Rs 25,000 and the opening balance of machinery during the year was Rs 5,00,000.
So as the machinery account comes under the category assets, its opening balance would come under the debit side of the ledger account.
And as purchase and installation charges mean expenses for the firm, they would also come under the debit side of the account.
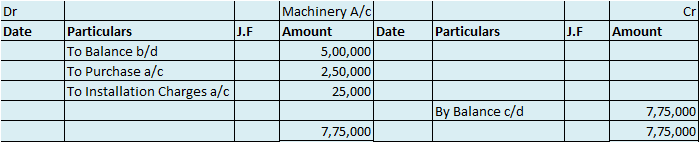
And in case of any sale of a part of the machinery, it would be posted on the credit side of the account as the sales would generate revenue for the firm.
See less




The profit earned by an entity is determined through the profit and loss account. All the expenses are recorded on the debit side of the profit and loss account while all the incomes are recorded on the credit side. The profit is shown as the credit balance of profit and loss A/c. When the sum of itRead more
The profit earned by an entity is determined through the profit and loss account. All the expenses are recorded on the debit side of the profit and loss account while all the incomes are recorded on the credit side.
The profit is shown as the credit balance of profit and loss A/c. When the sum of items on the debit side of a profit and loss account is less than the sum of those on the credit side, it implies profit while when the sum of the items on the credit side is less than the sum of those on the debit side, it implies a loss for the entity.
The Reason for Credit
Profit is recorded as an increase in equity
To understand the reason why profit is recorded as a credit balance, we must first understand the basic principle of debit and credit.
The basic principle of debits and credits is that debits increase asset accounts and decrease liability and equity accounts while credits decrease asset accounts and increase liability and equity accounts.
The revenue that a company earns is credited to the income account and increases equity.
The expenses that a company incurs to earn that revenue are debited to the expense account and decrease equity.
The difference between revenue and expenses is the profit, which is recorded as an increase in equity.
Increase in equity due to revenue – decrease in equity due to expense = profit
Gross Profit Vs Net Profit
Revenue is the total income that a business or profession earns. Profit is the excess revenue that remains after reducing all expenses from it.
Gross profit is the profit that a company earns after reducing the cost of goods sold from sales revenue while net profit is the profit that a business earns after reducing the total of all its direct and indirect expenses from its direct as well as indirect allowable business income.
Conclusion
The basic principle of debit and credit governs the classification of profit as a debit or credit. Since profit increases our equity, it is a credit.
In the case of a company, it belongs to the shareholders. It is usually recorded in the retained earnings account. Profit can be reinvested in the business or can be distributed as a dividend. In the case of a sole proprietorship, the profit belongs to the owner and is recorded in the owner’s capital account.
See less