Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Bonnie
BonnieCurious
In: 1. Financial Accounting > Accounting Terms & Basics

Is capital a real account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 8, 2021 at 5:55 am
    This answer was edited.

    No, capital account is not a real account. Capital account represents the amount of money invested by the owner/owners of the business along with the retained earnings net of drawings or dividends. Capital account has a natural credit balance because it is an internal liability of the business. CapiRead more

    No, capital account is not a real account.

    Capital account represents the amount of money invested by the owner/owners of the business along with the retained earnings net of drawings or dividends. Capital account has a natural credit balance because it is an internal liability of the business.

    Capital account is a personal account because, as discussed above, it represents the investment of the owner or owners. Personal account represents person or persons.

    Whereas a real account represents the material assets of a business. Example:-  Cash A/c, Fixed assets A/c etc. That’s why the capital account is not a real account.

    Being a personal account, the following golden rule of accounting applies to capital account:-

    “Debit the receiver and credit the giver”

    Here, as the owner gives an amount as an investment into the business (owner and the business are separate entities), the capital account has a credit balance.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Miscellaneous

What is an example of general reserve?

  • 1 Answer
  • 0 Followers
Answer
  1. Astha Leader Pursuing CA, BCom (Hons.)
    Added an answer on March 25, 2022 at 5:41 pm
    This answer was edited.

    General reserve is the part of profits or money kept aside to meet future uncertainties and obligations of the entity.  General reserve is created out of revenue profits for unspecified purposes and therefore is also a part of free reserves. General reserve forms a part of the Profit & Loss ApprRead more

    General reserve is the part of profits or money kept aside to meet future uncertainties and obligations of the entity.  General reserve is created out of revenue profits for unspecified purposes and therefore is also a part of free reserves.

    General reserve forms a part of the Profit & Loss Appropriation account and is created to strengthen the financial position of the entity and serves as a sources of internal financing. It is upon the discretion of the management as to how much of a reserve is to be created. No reserve is created when the entity incurs losses.

    General reserve is shown in the Reserves & Surplus head on the liability side of the balance sheet of the entity and carries a credit balance.

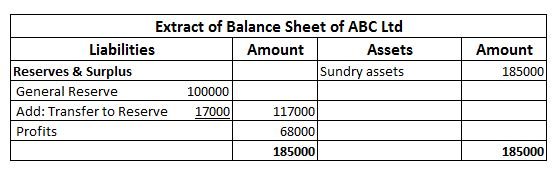
    Suppose, an entity, ABC Ltd engaged in the business of electronics earns a profit of 85000 in the current financial year and has an existing general reserve amounting to 100000. The management decides to keep aside 20% of its profits as general reserve.

    Then the amount to be transferred to general reserve will be = 85000*20% = 17000.

    In the financial statements it will be shown as follows-
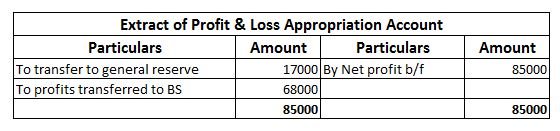
    Now, in the next financial year, the entity incurs losses amounting to 45000. In this case, no amount shall be transferred to the general reserve of the entity and will be shown in the financial statement as follows-
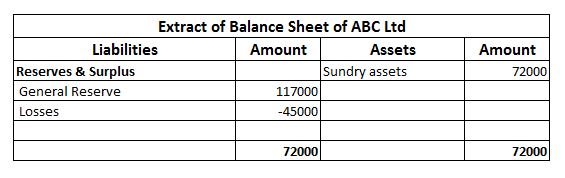
    The creation of general reserve can sometimes be deceiving since it does not show the clear picture of the entity and absorbs losses incurred.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What is a workmen compensation reserve?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 18, 2021 at 7:51 am
    This answer was edited.

    Workmen Compensation Reserve as the name suggests is a reserve created by the company to compensate its employees in the event of any uncertainty in future. It is created to protect the interest of workers in the company. Workmen Compensation Reserve Account is generally given effect in case of admiRead more

    Workmen Compensation Reserve as the name suggests is a reserve created by the company to compensate its employees in the event of any uncertainty in future. It is created to protect the interest of workers in the company.

    Workmen Compensation Reserve Account is generally given effect in case of admission, retirement of partners or dissolution of firm.

    If there is a change in the estimated value of reserve it is given effect during the revaluation of assets and liabilities.

    Journal entry if the existing reserve is less than the new estimated amount:

    Revaluation A/c (Dr)

    To Workmen Compensation Reserve A/c

    The reserve is credited because we need to create more than the existing reserve, since the new estimated liability is more than the existing.

    Journal entry if the existing reserve is more than the new estimated amount:

    Workmen Compensation Reserve A/c (Dr)

    To Revaluation A/c

    The reserve is debited because we need to decrease the existing reserve, since the new estimated liability is less than the existing.

    If a worker claims compensation, it is said to be a liability against the reserve. In case of dissolution, any such liability against workmen compensation reserve takes priority to be paid off according to the law.

    Journal entry in case of claim against reserve is:

    Workmen Compensation Reserve A/c (Dr)

    To Workmen Compensation Claim

    The amount is transferred from the reserve to a new liability, hence the reserve is debited and the claim is credited.

    If there are not sufficient funds in the firm to pay the liability, partners will have to bring funds from their personal assets to pay the workers.

    Journal entry when partner’s have to bring funds:

    Partner’s Capital Account (Dr)

    To Workmen Compensation Reserve A/c

    Partner’s need to bring funds to fulfill the liability, hence there account is debited and since the reserve is increased, hence it is credited.

    If there is no liability against the Workmen Compensation Reserve then it is distributed amongst the partners in their existing profit-sharing ratio.

    Journal entry for distribution of reserve is:

    Workmen Compensation Reserve A/c (Dr)

    To Partner’s Capital Account

    Since, reserve is more than required it is distributed among partners, hence their account is credited and as the reserve decreases, it is debited.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Financial Statements

Why is profit on debit side?

  • 1 Answer
  • 0 Followers
Answer
  1. Kajal
    Added an answer on September 27, 2023 at 11:52 am
    This answer was edited.

    Profit refers to the excess of total revenue over total expenses. According to the rule "Debit all expenses and losses, Credit all incomes and gains", expenses are recorded on the debit side while revenues are recorded on the credit side. There is profit when Total revenue > Total expenses, whichRead more

    Profit refers to the excess of total revenue over total expenses. According to the rule “Debit all expenses and losses, Credit all incomes and gains”, expenses are recorded on the debit side while revenues are recorded on the credit side.

    There is profit when Total revenue > Total expenses, which means the balance of the credit side > the balance of the debit side. Since, in accounting Dr. side is always equal to the credit side, a balancing figure (representing profit or loss) is shown on the shorter side, to make both sides equal.

    When Credit side > Debit side, Profit(balancing figure) is shown on the Dr. side so that both sides are equal. 


    PROFIT

    Profit refers to the excess of total revenue over the total expenses of the business for an accounting year. In simple words, it shows how much extra the firm earned after deducting all the expenses it incurred during the year.

    Profit = Total Revenue – Total Expenses

    Suppose, the firm earned a total revenue of $10,000 for the accounting year 2022-23. Also, it incurred total expenses of $6,000 during the year. So, Profit for the AY 2022-23 is $4,000.


    ASCERTAINING PROFIT

    To ascertain profit earned or loss incurred by the firm during an accounting year, it prepares two accounts.

    • Trading A/c
    • Profit and Loss A/c


    Points to be noted:

    • Both accounts are Nominal Account which follows the rule “Debit all expenses and losses, Credit all incomes and gains”
    • The debit side records expenses while the Credit side records incomes.
    • Both are balanced accounts, which means its Dr. side is always equal to its Cr. side.
    • If they are not balanced, then a balancing figure is added to the shorter side which represents profit or the loss depending on which side is greater.
    • If Dr. side > Cr. side, it means expenses are more than the incomes and thus, there is a loss.
    • If Cr. side > Dr. side, it means there are more incomes than expenses and thus, there is Profit.


    TRADING ACCOUNT

    It is the first final account prepared for calculating gross profit or gross loss during the year because of the trading activities of the firm.

    Trading activities are related to the buying and selling of goods. In between buying and selling a lot of activities are there like transportation, warehousing, loading, unloading, etc. All expenses that are directly related to buying and selling as well as manufacturing of goods are known as Direct expenses and are also recorded in the trading accounts.

    Items included on the debit side:

    • Opening stock
    • Purchases
    • Direct expenses like wages, import duty, royalty, manufacturing expenses, etc.
    • Gross Profit


    Items included on the credit side:

    • Sales
    • Closing stock
    • Gross loss


    Gross Profit is when Cr. side (incomes) > Dr. side (expenses). It is recorded on the debit side as a balancing figure.


    PROFIT AND LOSS ACCOUNT

    A businessman incurs a lot of expenses during the year which may be directly related or indirectly related to the business.

    As the Trading account only considers direct expenses, the businessman prepares the P&L A/c which considers all the expenses incurred during a year to ascertain net profit or loss.

    Items written on the Debit side

    • Gross loss (transferred from the trading a/c)
    • Office and administrative expenses (like employee’s salary, office rent, office lighting bills, legal charges, printing expenses, etc.)
    • Selling and distribution expenses (like advertisement fees, commission, carriage outward, packaging charges, etc.
    • Miscellaneous expenses (like interest on loan, interest on capital, repair, depreciation, etc.)
    • Net Profit


    Items written on the Credit side

    • Gross Profit (transferred from trading a/c)
    • Other incomes and gains (Like income from investments, interest received, rent received, etc.)
    • Net loss


    Net Profit is when the Cr. side (incomes)> Dr. side(expenses). It is recorded on the Debit side as a balancing figure.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Financial Statements

Which type of account is trading account?

  • 1 Answer
  • 0 Followers
Answer
  1. Bonnie Curious MBA (Finance)
    Added an answer on December 13, 2022 at 8:33 am
    This answer was edited.

    As per the Golden Rules As per the golden rules of accounting, a trading account is a nominal account. To ensure that financial statements accurately reflect a business's financial position and performance, the golden rules of accounting guide the preparation of financial statements. The point to noRead more

    As per the Golden Rules

    As per the golden rules of accounting, a trading account is a nominal account. To ensure that financial statements accurately reflect a business’s financial position and performance, the golden rules of accounting guide the preparation of financial statements.

    The point to note is that it is almost impossible to apply the rules of debit and credit with certain accounts such as Trading A/c, Profit & Loss A/c, etc.


    As per the Modern Rules

    The purpose of a trading account is to record transactions related to the purchase and sale of goods for a business. In other words, it serves as a recording and reporting mechanism for business income and expenses.

    An accounting period, like a month, quarter, or year, is the time when a trading account is prepared. It is used to calculate the business’s net profit or loss. Other financial statements, such as the balance sheet, are prepared using the information in a trading account.

    In summary, a trading account is a type of income statement account that is used to track and report on the income and expenses from a business’s buying and selling activities


    Rules of Debit and Credit

    There are three main types of accounts according to the legacy rules of debit and credit: personal accounts, real accounts, and nominal accounts. A personal account is one that is related to an individual or entity owing the business money (e.g. a customer), or owing the business money (e.g. a supplier).

    A real account is one that relates to assets such as cash, inventory, and property.

    Nominal accounts are accounts that relate to income and expenses, such as a “trading account”.

    To summarize, a trading account is a nominal account used to record and report the business’s income and expenses resulting from its buying and selling activities.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Accounting Terms & Basics

Who are shareholders in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 3, 2021 at 5:44 pm
    This answer was edited.

    Shareholders are the entities that hold some amount or number of shares of a company. As we know that ownership of a company is divided into its shares, a shareholder is actually a part-owner of a company. By entity, it means a shareholder may be: An individual Any other company Any other incorporatRead more

    Shareholders are the entities that hold some amount or number of shares of a company. As we know that ownership of a company is divided into its shares, a shareholder is actually a part-owner of a company.

    By entity, it means a shareholder may be:

    • An individual
    • Any other company
    • Any other incorporated entity
    • Cooperative society
    • BOI( Body of Individuals)
    • AOP(Association of Persons)
    • Artificial Juridical Person

    The rights of shareholders depend on the type of shareholder one is.

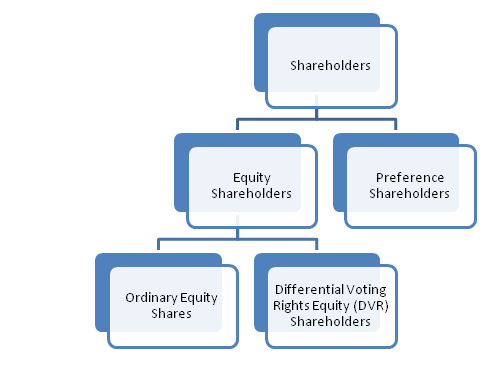
    Types of shareholders

    1.   Equity Shareholders: By the term ‘shareholders’ we usually mean equity shareholders. They are permanent in nature i.e. they are not repaid the money they have invested into the company until the company is liquidated or wound up. Equity shareholders have the following rights:

    • Right to have a share in profits made by the company. The profit made by a company, when distributed to its equity shareholders is known as a dividend.
    • Right to vote on all resolutions to be passed in the Annual General Meeting of a company.
    • Right to get repaid in event of winding up of the company. However, they are paid after meeting the obligations of outsiders and of preference shareholders.
    • Right to transfer ownership of the shares. A shareholder may sell its shares to some willing buyer and cease to be a shareholder of a company.


    2. Preference Shareholders: They are shareholders who are given preference regarding:

    • Dividend
    • Repayment at time of winding up

    Unlike equity shareholders, they are not of permanent nature. Preference shares are redeemable i.e. they are to be repaid after a period which cannot be more than 20 years from the date of allotment of such shares (as the Companies Act, 2013). Also, a company cannot issue irredeemable preference shares. The rights of preference shareholders are as follows:-

    • By preference as to dividend, it means preference shareholders have the right to receive a fixed dividend as a certain percentage on the nominal value of the share and that too before equity shareholders are paid.
    • Right to get repaid at the date of redemption.
    • If the company get liquidated before redemption of the preference shareholder, then they have the right to get repaid before equity shareholders.


    3.  Differential Voting Rights Shareholders: These shareholders hold equity shares but with differential, right as to voting i.e. they may either have less voting rights or more voting right as compared to ordinary equity shares. Generally, DVR shares carry less voting power.

    For example, a DVR shareholder gets 1 vote for 10 shares whereas an ordinary equity shareholder gets 10 votes for 10 shares i.e. one vote for every share. DVR shares issued to raise not only permanent capital but also prevent dilution of voting rights.

    The rest of the right remains the same as the equity shareholders.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Ledger & Trial Balance

Write the process of preparing ledger from a journal?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on August 11, 2021 at 8:01 am
    This answer was edited.

    As you know all transactions occurring in a business are recorded in the journal (book of original entry) in chronological order. After recording them in the journal, they are posted to their respective ledger accounts. Here I've explained the steps involved in posting a journal entry to the ledger.Read more

    As you know all transactions occurring in a business are recorded in the journal (book of original entry) in chronological order. After recording them in the journal, they are posted to their respective ledger accounts.

    Here I’ve explained the steps involved in posting a journal entry to the ledger.

    Posting of an account debited in the journal entry:

    Step 1: Identify the account which has to be debited in the ledger.

    Step 2: Write the date of the transaction under the ‘Date Column’ of the debit side of the ledger account.

    Step 3: Write the name of the account which has been credited in the journal entry in the ‘Particulars Column’ on the debit side of the account as “To (name of the account)”.

    Step 4: Write the page number of the journal where the entry exists in the ‘Journal Folio (JF) Column’.

    Step 5: Enter the amount in the ‘Amount Column’ on the debit side of the ledger account.

    Posting of an account credited in the journal entry:

    Step 1: Identify the account which has to be credited in the ledger.

    Step 2: Write the date of the transaction under the ‘Date Column’ of the credit side of the ledger account.

    Step 3: Write the name of the account which has been debited in the journal entry in the ‘Particulars Column’ on the credit side of the account as “By (name of the account)”.

    Step 4: Write the page number of the journal where the entry exists in the ‘Journal Folio (JF) Column’.

    Step 5: Enter the amount in the ‘Amount Column’ on the credit side of the ledger account.

    I’ll explain the process of preparing a ledger A/c with a simple transaction.

    On 1st May ABC Ltd. purchased machinery for 5,00,000. In the Journal the following entry will be made.

    Machinery A/c   5,00,000
       To Bank A/c   5,00,000
    (Being machinery purchased for 5,00,000)

    Let’s assume that this entry appears on page no. 32 of the journal. Now we will open Machinery A/c and Bank A/c in the Ledger.

    On the debit side of the Machinery A/c “To Bank A/c” will be written. In the Bank A/c “By Machinery A/c” will be written on the credit side.

    An extract of both the accounts are as follows:

    Machinery A/c

    Date Particulars J.F. Amt. Date Particulars J.F. Amt.
    May-01 To Bank A/c 32   5,00,000


    Bank A/c

    Date Particulars J.F. Amt. Date Particulars J.F. Amt.
    May-01 By Machinery A/c 32   5,00,000
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.