Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

What is a prepaid payable?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 14, 2022 at 2:55 pm
    This answer was edited.

    Prepaid Payable Prepaid payable or prepaid expenses refer to the future expenses that have been paid in advance. It is an advance payment made by the business for the goods and services to be received by the business in the future. A prepaid expense is an asset on the balance sheet. The number of prRead more

    Prepaid Payable

    Prepaid payable or prepaid expenses refer to the future expenses that have been paid in advance. It is an advance payment made by the business for the goods and services to be received by the business in the future.

    A prepaid expense is an asset on the balance sheet. The number of prepaid expenses that will be used up within one year is reported on a company’s balance sheet as a current asset. According to generally accepted accounting principles (GAAP), expenses should be recorded in the same accounting period as the benefit generated from the related asset.

    Example

    ABC Ltd. purchases insurance for the warehouse. It was ₹2,000 per month. The company pays ₹24,000 in cash upfront for a 12-month insurance policy for the warehouse. Each month an adjusting journal entry will be passed, adjusting the amount of insurance used from the prepaid insurance.

    Journal Entry-

    Prepaid Expenses in Balance Sheet-

    Prepaid expenses are shown in the balance sheet under the current assets heading as it’s a short-term asset and to be consumed within one accounting year.

    Balance Sheet (for the year ending…)

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Miscellaneous

How are contingent assets different from contingent liabilities ?

  • 1 Answer
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Contingent Asset is an asset the existence, ownership, or value of which may be known or determined only on the occurrence or non-occurrence of one or more uncertain future events. However, the difference between Contingent assets is not disclosed whereas Contingent liabilities are discloRead more

    Definition

    Contingent Asset is an asset the existence, ownership, or value of which may be known or determined only on the occurrence or non-occurrence of one or more uncertain future events.

    However, the difference between Contingent assets is not disclosed whereas Contingent liabilities are disclosed by way of notes they do have different criteria for recognition which are discussed below.

    For example:– a claim that an enterprise is pursuing through the legal process, where the outcome is uncertain, is a contingent asset.

    Contingent liabilities are defined as obligations relating to existing conditions or situations which may arise in the future depending on the occurrence or non-occurrence of one or more uncertain events.

    For example:- Billis discounted but not yet matured, arrears of dividend on cum –preferences-shares, etc.

    Meaning as per AS – 29

    Now let me try to explain to you the meaning according to Accounting Standard 29 of the above contingent assets and liabilities which is as follows:-

    • Contingent asset

    A contingent asset is a possible asset that arises from past events the existence of which will be confirmed only by the occurrence or non-occurrence of one or more uncertain future events.
    Not wholly within the control of the enterprise.

    It usually arises from unplanned or unexpected events that give rise to the possibility of an inflow of economic benefits to the enterprise.

    • Contingent liability

    A possible obligation that arises from past events the existence of which will be confirmed only by the occurrence or non-occurrence of one or more uncertain future events.
    Not wholly within the control of the enterprise.

    A present obligation that arises from past events but is not recognized because it is not probable that the outflow of resources embodying economic benefits will be required to settle the obligation or,
    A reliable estimate of the amount of obligation cannot be made.

    Recognition In Financial Statements

    Contingent assets and liabilities are recognized as follows:-

    • Contingent Assets

    As per the prudence concept s well as present accounting standards, an enterprise should not recognize a contingent asset.

    It is possible that the recognition of contingent assets may result in the recognition of income that may never be realized.

    However, when the realization of income is virtually certain, the related asset no longer remains contingent.

    • Contingent liability

    As per the rules, it is not recognized by an enterprise.

    When recognized?

    Contingent assets are assessed continually and if it has become virtuality an outflow of economic benefits will arise.

    The assets and the related income are recognized in the financial statements of the period in which the change occurs.

    Contingent liability is assessed continually to determine whether an outflow of resources embodying economic benefits has become probable.

    And if it becomes probable that an outflow or future economic benefits will require for an item previously dealt with as a contingent liability.

    A provision is recognized in financial statements of the period in which the change probability occurs except in extremely rare circumstances where no reliable estimate can be made.

    Disclosure

    Now we will see how contingent assets and liability are disclosed which is mentioned below:-

    • Contingent asset

    These contingent assets are not disclosed in financial statements.
    A contingent asset is usually disclosed in the report of the approving authority ( ie.e., Board Of Directors in the case of a company, and the corresponding approving authority in case of any enterprise), if ab inflow of economic benefits is probable.

    • Contingent Assets

    A contingent liability is required to be disclosed by way of a note to the balance sheet unless the possibility of an outflow of a resource embodying economic benefit is remote.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SAMKV
SAMKVCurious
In: 1. Financial Accounting > Journal Entries

PASS THE JOURNAL ENTRIES (WHICH SHOULD HAVE AT LEAST 20 TRANSACTIONS WITH GST) POST THEM INTO THE LEDGER, PREPARE A TRIAL BALANCE BY BALANCE METHOD-

  • 0 Answers
  • 0 Followers
Answer
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Financial Statements

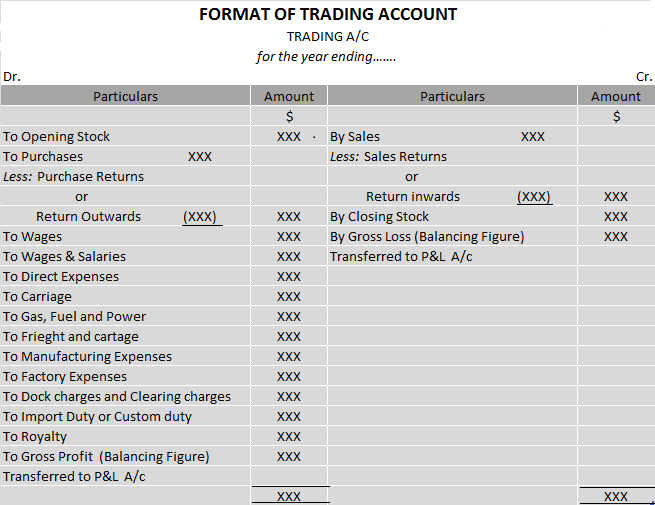
What is debit side of trading account?

  • 1 Answer
  • 0 Followers
Answer
  1. Kajal
    Added an answer on September 20, 2023 at 4:41 pm
    This answer was edited.

    Trading A/c is a nominal account which follows the rule "Debit all expenses and losses, Credit all incomes and gains". So, all expenses relating to the purchase or manufacturing of goods are shown on the debit side of the Trading A/c. It includes Opening Stock, Purchases, Wages, Carriage Inward, ManRead more

    Trading A/c is a nominal account which follows the rule “Debit all expenses and losses, Credit all incomes and gains”.

    So, all expenses relating to the purchase or manufacturing of goods are shown on the debit side of the Trading A/c. It includes Opening Stock, Purchases, Wages, Carriage Inward, Manufacturing Expenses, Dock charges, and other direct expenses that are directly related to the manufacturing or purchase.


    TRADING ACCOUNT

    Trading A/c is prepared for calculating the Gross Profit or Gross Loss arising from the trading activities of a business.

    Trading activities are mostly related to buying and selling of goods. However, in between buying and selling, a lot of activities are involved like transportation, warehousing, etc. So, all the expenses that are directly related to manufacturing or purchase of goods are also recorded in the Trading A/c.


    DEBIT SIDE OF TRADING A/C

    The items shown on the Dr. side are,

    OPENING STOCK – Stock is nothing but goods that are either obtained for resale or manufactured for sale and are yet unsold on any particular date.

    The value of stock at the beginning of an accounting year is called Opening stock while the value of the stock at the end of an accounting year is called closing stock.

    The closing stock of the last year becomes the opening stock of the current year.

    Opening stock includes,

    1. Opening Stock of Raw materials
    2. Opening Stock of Semi-finished goods
    3. Opening Stock of Finished goods

    For example – Suppose you are in the business of manufacturing and trading shirts. On 31st March 2023, there was unused raw material worth $10,000 and shirts worth $50,000 remained unsold.

    So, we have Closing Stock of Raw material – $10,000

    Closing Stock of Finished Goods – $50,000

    This closing stock of last year becomes your opening stock during the current year i.e. on 1st April 2023, we have

    Opening Stock of raw material – $10,000

    Opening Stock of Finished Goods – $50,000

    PURCHASES – Goods that have been bought for resale or raw materials purchased for manufacturing the product are terms as Purchases. These goods must be related to the business you are doing.

    It includes cash as well as credit Purchases.

    Continuing with the above example, suppose you bought raw material worth $ 1,00,000 for manufacturing and shirts worth $50,000 for resale (and not for personal consumption) then both these will be termed as purchases for you. So, your purchases will be $1,50,000 ($1,00,000 + $50,000)

    PURCHASES RETURN – When goods bought are returned to the suppliers due to any reason. This is known as Purchase return. Purchase return is deducted from the Purchases.

    In the above example, you bought shirts worth $50,000 for resale. Out of which shirts worth $20,000 were defective. So, you returned them to the supplier. This return of $20,000 is your purchase return or return outwards (as goods are going out)

    WAGES – Wages are paid to the workers who are directly engaged in the loading, unloading and production of goods.

    For example – Paid $10,000 to workers for manufacturing shirts.

    However, it would be included in Trading A/c only if the wages are paid for work which is directly related to the manufacturing or purchase of goods otherwise it will be shown in P&L A/c.

    Suppose you hired a manager to take care of your business and paid him $20,000 as salary. This salary is indeed an expense for the business but is not directly related to the manufacturing of goods. Since it is an indirect expense, it can only be recorded in P&L  A/c and not in the Trading A/c.

    CARRIAGE or CARRIAGE INWARDS or FREIGHT – It refers to the cost of transporting goods from the supplier.

    Suppose, you ordered raw material in bulk which was transported to you by a van and you paid its fare. This fare is nothing but your carriage inwards.

    However, if carriage or freight is paid on bringing an asset, the amount should be added to the asset account and must not be debited to the trading account.

    MANUFACTURING EXPENSES – All expenses incurred in the manufacture of goods such as  Coal, Gas, Fuel, Water, Power, Factory rent, Factory lighting etc.

    DOCK CHARGES – These are charged by port authorities when unloading goods at a dock or wharf. Such charges paid in connection with goods purchased are considered direct expenses and are debited to Trading a/c.

    IMPORT DUTY or CUSTOM DUTY – It is a tax collected on imports and specific exports by a country’s customs authorities. If import duty is paid on the import of goods, then they are shown on the Dr. side of the Trading A/c.

    For example –  Paid $15,000 as import duty for importing shirts for resale.

    ROYALTY – Royalty refers to the amount paid for the use of assets belonging to another person. It includes royalty for the use of intangible assets, such as copyrights, trademarks, or franchisee agreements. It is also paid for the use of natural resources, such as mining leases.

    Royalty is charged to the Trading A/c as it increases the cost of production.

    GROSS PROFIT – When sales exceed the amount of purchases and the expenses directly connected with such purchases i.e. when Credit side> Debit side.


    CREDIT SIDE OF TRADING A/C

    SALES – When goods are sold to earn a profit, it is called sales. It can be cash sales or credit sales.

    SALES RETURN – When the goods sold are returned by the customer, it is known as a sales return. Sales return is deducted from the sales.

    CLOSING STOCK – The goods remaining unsold at the end of the year are termed as closing stock. It is valued at cost price or market price whichever is less.

    GROSS LOSS – If purchases and direct expenses exceed sales, then it is a Gross loss. In other words, when Debit side > Credit side.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What is an example of specific reserve?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 24, 2021 at 11:49 am
    This answer was edited.

    The reserves created for specific purposes in business are called specific reserves. According to the Companies Act, 2013, these reserves cannot be used for any other purposes. However, if the Article of Association of a company allows, these reserves can be used for other purposes as well. Amount tRead more

    The reserves created for specific purposes in business are called specific reserves. According to the Companies Act, 2013, these reserves cannot be used for any other purposes. However, if the Article of Association of a company allows, these reserves can be used for other purposes as well.

    Amount to any specific reserve is generally transferred from the Profit and Loss Appropriation Account.

    Various specific reserves are:

    • Debenture Redemption Reserve

    Debentures are debt instruments of a company and they have to be redeemed, that is, paid back after the expiry of the specified period. According to Accounting Standards, companies are required to set aside a specific amount in Debenture Redemption Reserve, when they are due for redemption.

    • Securities Premium Reserve

    When shares or debentures are issued at a price higher than its book value/face value, the difference between the market value and book value is called Securities Premium. The amount of Securities Premium is transferred to Securities Premium Account. This amount is utilized to issue fully paid bonus shares, write off preliminary expenses, write off commission discounts, etc., to provide a premium on redemption of debentures.

    • Investment Fluctuation Reserve

    The investments made by a company are subject to fluctuations in its market value. Company Law and Accounting Standards require companies to provide for such fluctuations by creating a reserve called Investment Fluctuation Reserve.

    • Dividend Equalisation Reserve

    Companies are required to pay a dividend to their shareholders. It is often difficult for a company to maintain a consistent rate of dividend as the dividend paid is equivalent to the profit made by a company during the financial year which is not consistent. So, Dividend Equalisation Reserve is created to maintain a consistent rate of dividend on shares over time, in the event of both high and low profits.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Partnerships

What are the types of partnership?

  • 1 Answer
  • 0 Followers
Answer
  1. Mitika
    Added an answer on November 23, 2022 at 4:14 pm

    Types of Partnership A partnership is an agreement between two or more people who comes together to run a business. There are different types of partnerships formed with different perspectives as mentioned: General Partnership Limited Partnership Limited Liability Partnership Partnership at will ParRead more

    Types of Partnership

    A partnership is an agreement between two or more people who comes together to run a business.

    There are different types of partnerships formed with different perspectives as mentioned:

    General Partnership

    Limited Partnership

    Limited Liability Partnership

    Partnership at will

    Partnership for a fixed term


    General Partnership

    It refers to the partnership where all partners actively manage the business and have unlimited legal liability. Generally, all the partners share equal profit and loss in the business and are also equally liable for the outsider’s loan.

    All the partners are responsible for the business’s day-to-day operations and managerial responsibility.

    If the partners decided to share profit and loss in any other ratio (unequal ratio), then they have to disclose this in a agreement called a partnership deed.

    In this, debts are equally borne by selling the partners assets of all the partners. In case of dissolution, if the partnership firm has taken a loan from outsiders and does not have sufficient funds to repay the amount then the payment can be done by selling the partner’s personal property.

    It can be formed by signing the partnership agreement that would be proved as evident in case of disagreement among partners. For instance, if any partner dies or leaves the firm then they should follow the content of the agreement.

    A general partnership does not pay the tax instead the partners personally report their income tax return.


    Limited Partnership

    In a Limited partnership, all the partners contribute capital but not necessarily all of them manage the business.

    The old partners add a new partner into the partnership to fulfill the financial needs of the business i.e. for capital. The rights of decision-making are issued to new partners on the basis of their contribution of capital. The new partner is not associated with day-to-day business activities. He /She is called a limited partner or silent partner.

    The liability partner has limited liability to the extent of his capital. The personal assets of the limited partner can not be used for the payment of the firm’s liability.


    Limited Liability Partnership

    It is a more popular type of partnership in today’s world. To form an LLP you have to register under the Limited Liability Partnership Act, 2008.

    In this, all the partners have limited liability to the extent of the capital investment in the business. The personal assets of the partners can not be used to discharge the liability of the partnership.

    A Minimum of 2 partners are required to form an LLP. However, no maximum limit on a number of partners.

    It has also some features of the company. It has a separate legal entity. The LLP can buy property in its own name and sue and be sued in its name.

    LLPs are often formed by professionals like Chartered Accountants, doctors and Legal firms.


    Features

    • It has a separate legal entity.
    • The cost of forming is low.
    • It requires less compliance and regulations.
    • Minimum two partners are required, no limit on the maximum number of partners.
    • The partners has limited liability.


    Partnership at will

    Partnership at will is a form of business where there is no fixed tenure of the partnership. That means there is no expiration of the partnership. But if the partnership is formed for a fixed duration and its period has expired and still continues then it will become a partnership at will.


    Partnership for a fixed term

    The partnership is created for a fixed duration of the interval. After the expiration of such duration, the partnership may come to an end.

    If the partners share profit and loss even after the expiration of the duration of the partnership then it will become a partnership at will.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radhika
Radhika
In: 1. Financial Accounting > Depreciation & Amortization

What is plant and machinery depreciation rate?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on December 16, 2021 at 8:22 am
    This answer was edited.

    Plant and Machinery are the equipment attached to the earth that supports the manufacturing of the company or its operations. These are tangible non-current assets to the company and as a result, have a debit balance. Depreciation is the decrease in the value of an asset that is spread over the expeRead more

    Plant and Machinery are the equipment attached to the earth that supports the manufacturing of the company or its operations. These are tangible non-current assets to the company and as a result, have a debit balance.

    Depreciation is the decrease in the value of an asset that is spread over the expected life of the asset. Not depreciating an asset presents a false image of the company as the asset is recorded at a higher value and profit is overstated as depreciation expense is not provided for.

    There are two ways that a company provide depreciation:

    • By reducing the balance of an asset in the Asset Account by passing a journal entry.
    • By maintaining a separate account for depreciation called Accumulated Depreciation A/c. The nature of this account is naturally credit since it is created to reduce the value of an asset.

    For most of the depreciation methods, we need a rate to provide for depreciation every year. Now, for accounting purposes, the management can use a rate they think is suitable depending on the use and expected life of the machinery.

    Depreciation is calculated on the basis of the Companies act, 2013 for the purpose of book-keeping. According to Schedule 2 of the Companies Act, depreciation on plant and machinery is calculated on the basis of either SLM or WDV.

    Plant and machinery for those special rates are not assigned useful life is considered to be 15 years and depreciation is calculated @ 18.10% on WDV and @6.33% on SLM.

    According to the Income Tax Act, 15% depreciation is provided every year on Plant and Machinery and, an additional 20% depreciation is provided in the first year of installation of machinery.

    Depreciation on Machinery is charged on the basis of usage of such machinery. if it is used for 180 days or more then full depreciation is allowed and if it is used for less than 180 days then only 50% depreciation is allowed.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.