Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is capital maintenance?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on December 12, 2021 at 2:11 pm
    This answer was edited.

    Capital maintenance is a principle that states profit should not be recorded until its cost or capital has been maintained. In other words, profit should not be recognized unless net assets have been maintained. Capital maintenance states that profit recognized is the increase in the value of net asRead more

    Capital maintenance is a principle that states profit should not be recorded until its cost or capital has been maintained. In other words, profit should not be recognized unless net assets have been maintained.

    Capital maintenance states that profit recognized is the increase in the value of net assets. However, there are two exceptions to it:

    • Cash increased because of sale of stock to shareholders
    • Cash decreased because of dividend payout to its shareholders

    It is important because:

    • It protects the interest of shareholders
    • It protects the interest of creditors
    • Accurately analyzing the performance of the company

    Capital maintenance is of two types:

    • Financial Capital Maintenance

    It is measured by the value of assets at the beginning and end of the financial year.

    • Physical Capital Maintenance

    It is measured by the production capacity at the beginning and end of the financial year.

    Capital maintenance is concerned with keeping proper account balances of assets and not the physical assets.

    Inflation is the increase in the economic value of goods due to the lower purchasing power and not an actual increase in the value of assets. So, if the value of an asset is increased due to inflation it does not depict the right picture for the company.

    Hence, if the value of assets increases due to inflation, companies need to adjust the value of assets to assess if capital maintenance has occurred. 


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of “realization” in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 21, 2021 at 6:02 pm
    This answer was edited.

    Realization is an important principle in accounting. It is the basis of revenue recognition and it gives to accrual accounting. When we used the word realization, it is usually regarding revenue recognition. Realization of revenue means when revenue to be earned from the sale of goods or rendering oRead more

    Realization is an important principle in accounting. It is the basis of revenue recognition and it gives to accrual accounting. When we used the word realization, it is usually regarding revenue recognition.

    Realization of revenue means when revenue to be earned from the sale of goods or rendering of services or any other activity or source becomes absolute and certain. An item is to be shown as revenue in the books of accounts only after it is realized.

    Realization in case of sale of goods

    Realization occurs in the following situations:

    i) When the goods are delivered to the customer for a certain price

    ii) All significant risks and rewards of ownership have been transferred to the customer and the seller retains no effective control over the goods.

    Let’s take an example. Mr Peter received an order of 500 units of goods from Mr Parker on 1st April. The goods were delivered to Mr Parker on 15Th April and payment for goods was received on 30Th April.

    The realization of revenue from the sale of goods will be considered to have occurred on 15th April because the goods were delivered to the customer on that date. The entry of sale of goods will be entered on this day.

    Realization is not considered to have occurred on 1st April i.e the date of order because the seller had effective control on goods on that date.

    Realization in case of rendering of services

    The realization of revenue from the rendering of services occurs as per the performance of service.

    Now there arise two situations:

    • Multiple acts involved in the performance of service: Here, the revenue is realized proportionately on completion of each act.
    • A Single act involved in the performance of service: Here, revenue is realized only when the service is completely rendered or provided.

    Realization of income from other sources:

    • Interest Income: It is realized on a time proportion basis as per the amount outstanding and rates applicable.
    • Dividends: It is realized when the shareholder’s right to receive is established and when it is declared.

    Realization with regards to other sources of income is considered to have occurred only when there exist no significant uncertainty as to measurability or collectability.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aditi
Aditi
In: 1. Financial Accounting > Miscellaneous

How are Research & Development costs treated in financial statements?

  • 1 Answer
  • 0 Followers
Answer
  1. Mehak
    Added an answer on January 14, 2025 at 4:30 am
    This answer was edited.

    Every business requires research and development to create innovative products for consumers. More innovative and creative products and services are more popular among customers, leading to increased revenue and profits for the business. Creating new products or designing changes and testing existinRead more

    Every business requires research and development to create innovative products for consumers. More innovative and creative products and services are more popular among customers, leading to increased revenue and profits for the business.

    Creating new products or designing changes and testing existing products also forms a part of research and development.

    Examples of Research and Development costs are –

    1. Salaries of employees
    2. Cost of making prototypes
    3. Cost of raw material
    4. Overhead expenses

    Let us now understand how research and development costs are treated in Financial Statements.

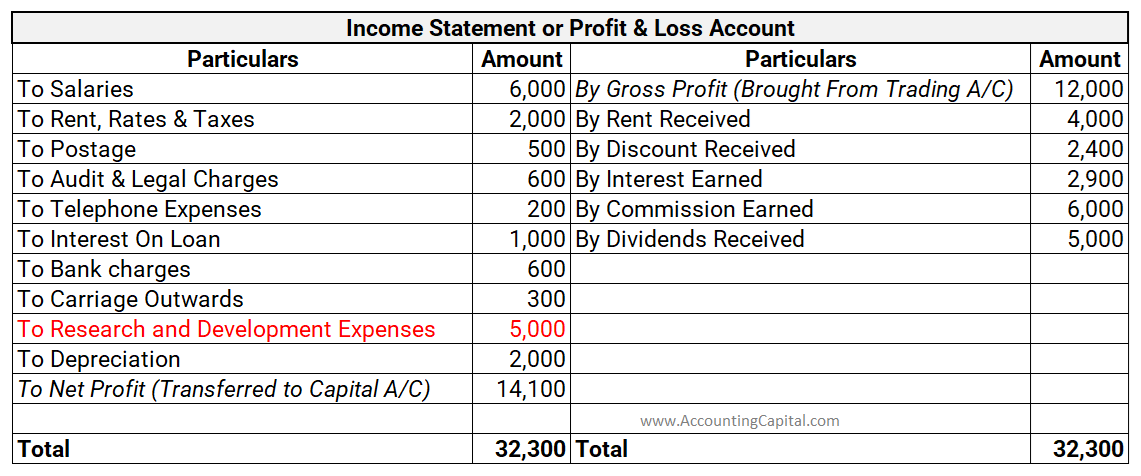
    Research and Development Costs are generally shown as an expense in the Income Statement.

    IAS-38

    IAS-38 majorly governs the accounting of research and development costs. There are two phases in R&D:

    • Research: During this phase, costs are incurred for understanding or designing the product. These costs are expensed as incurred costs as there is an uncertainty of a future benefit.
    •  Development: Economic value can be ascertained during this phase and hence, the costs incurred can be capitalized as Intangible assets. To be recognised as intangible assets, the following conditions shall be satisfied:

    1. it is developed with the intention of putting it to use in the future

    2.  the asset shall hold an economic value

    3. the costs can be measured reliably

    Treatment of R&D costs in the Financial statements:

      1. Income statement: Research costs are shown as expenses in the income statement. However, development costs if capitalized as intangible assets can be amortised over time.
      2. Balance Sheet: Capitalised development costs are shown as intangible assets under the Assets head of the Balance Sheet.

    Conclusion

    The above discussion can be summarised as follows:

    1. Research and development is essential for creating innovative and creative products and services.
    2. Accounting standard IAS-38 governs the accounting for Research and Development.
    3. Research costs are usually shown as an expense in the Income statement of the business.
    4.  Development costs when capitalised can be shown as Intangible assets in the Balance Sheet.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is the difference between operating lease and finance lease?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on June 24, 2022 at 6:40 pm
    This answer was edited.

    Meaning of lease A lease is an agreement or a contract in which the right to use an asset like land, building, or machinery is given by one party to the other party for a fixed period of time against the consideration of a single payment or a series of payments. There are two parties in a lease agreRead more

    Meaning of lease

    A lease is an agreement or a contract in which the right to use an asset like land, building, or machinery is given by one party to the other party for a fixed period of time against the consideration of a single payment or a series of payments.

    There are two parties in a lease agreement:

    • Lessor: The party who gives the right to use its asset in return for a series of payments or a single payment.
    • Lessee: The party who receives the right to use the asset from the Lessor.

    This is similar to a rent agreement or contract. The only difference between lease and rent is duration. A rent agreement is generally for less than 12 months while a lease agreement is for more than 12 months like 5 years or 10 years, sometimes even for like 99years.


    Type of lease

    There are two types of lease:

    • Operating lease
    • Finance Lease


    Operating lease

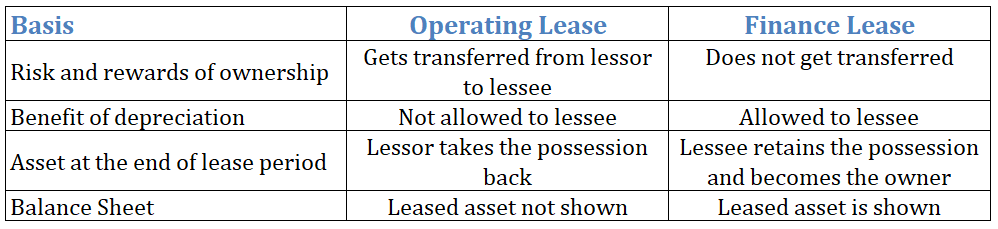
    • An operating lease is a type of lease in which the possession of the leased asset is transferred back from the lessee to the lessor at the end of the lease period.
    • Here, all the risk and rewards incident to ownership remains with the lessor, not the lessee.
    • The depreciation on the leased asset in case of operating lease is not charged by the lessee to its profit and loss account as the leased asset is not shown in the balance sheet. A leased asset is an off-balance sheet item in the case of an operating lease.


    Finance lease

    • Unlike an operating lease, the ownership of the leased asset is transferred to the lessee at the end of the leased period.
    • Thus, at the inception of the lease agreement, all the risk and rewards incident to ownership is transferred from the lessor to the lessee.
    • The depreciation on the leased asset is charged by the lessee to its profit and loss account as the leased asset is shown in the balance sheet. A leased asset is a balance sheet item in the case of an operating lease.
    • Along with the leased asset, the obligation to pay the future lease payment is also shown in the balance sheet as a non-current liability or current liability as the case may be.


    Difference between operating lease and finance lease in tabular format


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ishika Pandey
Ishika PandeyCurious
In: 1. Financial Accounting > Miscellaneous

Is creditor an asset or liability ?

  • 1 Answer
  • 0 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Yes, a creditor is a liability. Creditors are treated as current liability. A creditor is a person who provides money or goods to a business and agrees to receive repayment of the loan or the payment of goods at a later date. The loan may be extended with or without interest. Creditors may be secureRead more

    Yes, a creditor is a liability. Creditors are treated as current liability.

    A creditor is a person who provides money or goods to a business and agrees to receive repayment of the loan or the payment of goods at a later date. The loan may be extended with or without interest.

    Creditors may be secured creditors or unsecured creditors. In the case of secured creditors, some collateral is usually pledged to them. In the case of a default, they can sell or otherwise dispose of the collateral in any manner to recover the money due to them.

    In the case of unsecured creditors, no collateral is pledged against the amount due to them. In the case of a default, they can approach a Court to enforce repayment but cannot sell any asset of the company by themselves.

    Why are Creditors treated as a liability?

    An asset is something from which the business is deriving or is likely to derive economic benefit in the future. The business has legal ownership of that asset which is legally enforceable in a court of law. For example, Plant and Machinery, accrued interest, building, etc

    A liability is a legal obligation of the business. It may be in the form of outstanding payments or loans or the owner’s share of the company that the company has to pay them as and when demanded.

    As the company has a legal obligation to pay money to the creditor, they are treated as a liability. Most creditors are to be repaid within 1 year and are hence classified as current assets.

    Treatment and Importance of Creditors

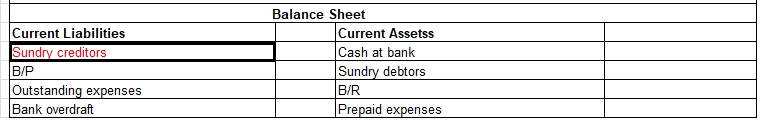
    Creditors are mostly treated as current liabilities. They are shown under the head “current liabilities” of the balance sheet of a company.

    The significance/importance of creditors is as follows:

    • The amount due to creditors affects the current and acid test ratio of a company significantly.
    • It affects the short-term cash requirements of a company.
    • It affects the credit policy of the company. A company can extend longer credit periods to customers if it can avail longer credit periods from its suppliers.
    • Having too many creditors or a large amount due to creditors can affect investor sentiment negatively regarding the business.

    We can conclude that the creditor being a person to whom the business is legally liable to pay a certain sum of money after a certain period of time has to be classified as a liability.

    Creditors play a major role in determining the success of a business. They act as a major constituent of the supply cycle of the business and affect the cash flows of the business. They are shown under the head “current liabilities” of the balance sheet of a company.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of capitalized in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 20, 2022 at 10:34 pm

    Capitalize in Accounting The term 'capitalized' in accounting means to record an expenditure as an asset on the balance sheet. Capitalization takes place when a business buys an asset that has a useful life. The cost of the relevant asset is then allocated to expense over its useful life i.e charginRead more

    Capitalize in Accounting

    The term ‘capitalized’ in accounting means to record an expenditure as an asset on the balance sheet. Capitalization takes place when a business buys an asset that has a useful life. The cost of the relevant asset is then allocated to expense over its useful life i.e charging depreciation, etc. This means that the relevant expenditure will appear on the balance sheet instead of the income statement. The capitalizing of the expenses is a benefit for the company as the assets bought by them for the long-term are subjected to depreciation and capitalizing expenses can amortize or depreciate the costs. This process is called capitalization.

    In order to capitalize any expense, we’ll have to make sure it meets the criteria stated below.

    The assets exceeding the capitalization limit

    The companies set a capitalization limit, below which the expenses are considered too immaterial to be capitalized. Therefore, the limit is supposed to be followed and considered as it controls the capitalization of the expenses. Generally, the capitalization limit is $1,000.

    The assets have a useful life 

    The companies also seek to generate revenues for a long period of time. Thus, the asset should have a long and useful life at least a year or more. Thereby, the business can record it as an asset and depreciate it over its valuable life.

    Most of the important principles of capitalization in accounting are from the matching principle.


    Matching Principle

    The matching principle states that the expenses in the accounting should be recorded when they are incurred and not when the payment is made. This helps the business identify the amounts spent to generate revenue.

    For e.g, the company bought machinery for manufacturing goods with more efficiency. It is supposed to have a useful life for a period of over 10 years. Instead of expensing the entire cost of the machinery, the company will write off (depreciated) the cost of the asset over its useful life i.e 10 years. Therefore, the asset will be written off as it is used and these types of assets are automatically used as capitalized assets.


    Benefits of Capitalization

    Capitalization is of course recording expenses as an asset but this indeed has benefits.

    • This reduces the fluctuation of income over time as the fixed assets (long-term) are costly. For the small business owners or the small firms, it’s even greater.
    • The capitalization of expenditures increases the company’s asset balance, without changing the company’s liability balance. This improves the financial ratios like the current ratio.
    •  Small businesses have a provision for tax benefits related to the depreciation of capitalized assets. Section 179 of depreciation allows those business owners to depreciate certain assets quicker than others are allowed.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

Which account has a debit balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Saurav
    Added an answer on September 20, 2023 at 4:40 pm
    This answer was edited.

    Debit balance means excess of credit side over debit side. For Example- At the beginning of the year the debit balance of trade receivables is 3,000 and there is a decrease(credit) of trade receivables of 1,000 during the year and an increase(debit) of trade receivables of 4,000 then at the end therRead more

    Debit balance means excess of credit side over debit side.

    For Example- At the beginning of the year the debit balance of trade receivables is 3,000 and there is a decrease(credit) of trade receivables of 1,000 during the year and an increase(debit) of trade receivables of 4,000 then at the end there will be a debit balance of 6,000 of trade receivables at the end

    A Debit balance basically signifies all expenses and losses and all positive balances of assets. The debit balance increases when any asset increases and decreases when any asset decreases.

    Assets

    All the assets that appear in the balance sheet always have a debit balance. The debit balance under it will increase as it debits. Some of these assets can be illustrated below -:

    •  Cash and Bank Balance: Cash and Bank Balance means the amount that is held by a person in physical form or in a current/savings account.
    • Property, Plant, and Equipment-  Property Plant, and Equipment means assets that are used for the production of goods and services.
    • Account Receivables– Account Receivables means the amount that is due from debtors to whom goods were sold at credit for a specified time period.
    • Inventory – Inventory means goods that are used in the normal course of business.
    • Investments– Investments are the amount invested in other companies from which they were expecting returns in future periods.


    Expenses and Losses

    All expenses that appear on the debit side of the P&L account have a debit balance in their accounts.

    For eg-: A rent of 10,000 is given to the landlord under which the work has been done by the entity.

    For eg-: A depreciation of 10% is there on an asset of 12,000 will result in a debit balance under depreciation in the P&L Account.

    Some of the following expenses can be illustrated below

    • Rent- Rent means a property that an entity takes on lease for business purpose and pay a certain amount to the landlord for such lease.
    • Depreciation– Depreciation means a fall in the value of an asset due to its usage every year
    • Loss on Sale of an asset- Loss on the Sale of an Asset means the sale amount of the asset is less than its WDV
    • Printing and stationery– Printing and Stationery means the paperwork or anything related to stationery used for business purposes
    • Audit fees– Audit fees are the amount which is given to an auditor for auditing the financials of an entity
    • Salaries and Wages– Salaries and Wages are the amount given to employees for the work they have done for the entity
    • Insurance– Insurance means a premium given by an entity for insurance done by them
    • Advertising– Advertising means any promotion that a company does of its product to increase its revenue

    So after seeing all the above points we can conclude that the debit balance includes all the expenses that are in the P&L account and all the assets that are there in the Balance sheet. So its balance increases when there is an increase in its account.


    CREDIT BALANCE

    Credit balance means excess of credit side over debit side.

    For example, At the beginning of the year, the credit balance of trade payable is 3,000 and there is a debit of trade payable of 1,000 during the year and an increase(credit) of trade payable of 4,000 then at end there will be a credit balance of 6,000 for trade payable at the end

    .A Credit balance signifies all income and gains and all liabilities and capital that is there in business.

    Liabilities

    • Account Payables
    • Bank Overdraft
    • Bonds
    • Income Tax Payables
    • Notes Payable
    • Deferred Tax Liability


    Income and Gains

    • Interest Received
    • Dividend Received
    • Rent Received
    • Gains on Sale of Capital Gains


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.