Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Atreya
AtreyaCurious
In: 1. Financial Accounting > Not for Profit Organizations

Which type of accounting is done by NPOs ?

  • 1 Answer
  • 1 Follower
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on May 23, 2023 at 2:18 pm

    Definition Not-for-profit organizations are also known as non-profit organizations set up to further cultural, educational, religious, professional, or public service objectives. Its  aim is not to earn profit Accounting done by non-profit organizations is fund based.   Type of accounting Non-pRead more

    Definition

    Not-for-profit organizations are also known as non-profit organizations set up to further cultural, educational, religious, professional, or public service objectives. Its  aim is not to earn profit

    Accounting done by non-profit organizations is fund based.


    Type of accounting

    Non-profit organizations do Fund Based Accounting.

    Donations received or funds set aside for specific purposes are credited to a separate fund account and are shown on the liabilities side of the balance sheet.

    The income from or donations for these funds are credited to the respective fund account. On the other hand, expenses or payments out of these funds are debited.

    Accounting when done on this basis is known as Fund Based Accounting.

    Let me explain to you with an example :

    The sports fund has a balance of Rs 100000 which is invested as a fixed deposit in a bank earning 8% interest. A further donation of Rs 10000 is received towards it. Expenses incurred towards prizes are Rs 7000; Rs 3000 towards trophies and Rs 4000 distribution of cash prizes. The accounts are shown as follows :

    Categories of funds

    In the case of non-profit organizations, funds may be classified under the following heads :

    Unrestricted fund :

    The unrestricted fund does not carry any restriction with respect to its use. In other words, management can use the amounts in the funds as it deems appropriate, but to carry out the purpose for which the organization exists.

    This is known as the general fund or the capital fund to which the surplus for the year is added and in case of deficit, deducted.

    Restricted fund :

    A restricted fund is a fund, the use of which is restricted either by the management or by the donor for a specific purpose.

    Examples of such funds are endowment funds, annuity funds, loan funds, prize funds, sports funds, etc.

    • Government grant: grant received from the government for a specific purpose is restricted to be used for the purpose it is granted. It is accounted for in the books following fund-based accounting.
      • For example, a grant received from the government for ‘the polio eradication program is credited to the polio eradication fund, and income earned relating to the fund is credited to the fund while expenses are debited.


    • Endowment fund: it’s a fund usually a non-profit organization, arising from a bequest or gift, the income of which is devoted to a specific purpose.


    • Annuity fund: an annuity fund is established when a non-profit organization receives assets from a donor with a condition to pay


    • Loan fund: loan fund is set up to grant loans for specific purposes say loans to pursue higher studies.


    • A fixed assets fund is a fund earmarked for investment in fixed assets or already invested in fixed assets.


    • Prize funds: it is a fund set up to use for distribution as prizes say for achievements or contributions to the welfare of society.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Miscellaneous

What are examples of current assets?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 18, 2022 at 7:31 pm
    This answer was edited.

    Current Assets & Examples Current Assets are those assets that are bought by the company for a short duration and are expected to be converted into cash, consumed, or written off within one accounting year. They are also called short-term assets. These short-term assets are typically called currRead more

    Current Assets & Examples

    Current Assets are those assets that are bought by the company for a short duration and are expected to be converted into cash, consumed, or written off within one accounting year. They are also called short-term assets.

    These short-term assets are typically called current assets by the accountants and have no long-term future in the business. Current assets may be held by a company for a duration of a complete accounting year, 12 months, or maybe less. A major reason for the conversion of current assets into cash within a very short amount of time is to pay off the current liabilities.

    Examples

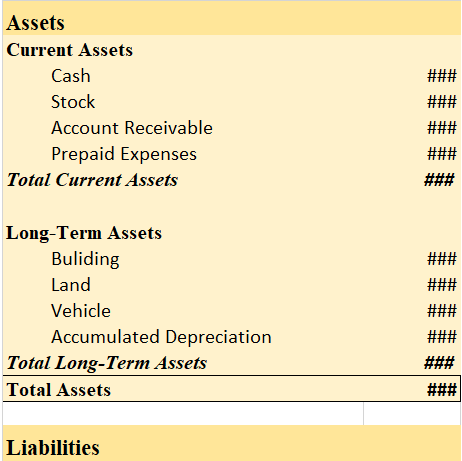
    Some of the major examples of current assets are – cash in hand, cash at the bank, bills receivables, sundry debtors, prepaid expenses, stock or inventory, other liquid assets, etc.

    • All of these assets are converted into cash within one accounting year.
    • Liquid assets are a part of current assets. Although they are easier to be converted into cash than current assets.
    • Current assets (along with current liabilities) help in the calculation of the current ratio. And they’re also referred to as circulating/floating assets.
    • Current assets are shown on the balance sheet (on the asset side) under the heading, current assets.

    Current assets on the balance sheet

    Balance Sheet (for the year…)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Journal Entries

What is the journal entry for cash sales?

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on August 7, 2021 at 1:33 pm
    This answer was edited.

    The journal entry for Cash Sales is- Particulars Amount Amount Cash A/c                                                      Dr $$$      To Sales A/c $$$ Sales Account is a Revenue Account and Cash Account is an Asset Account for the business. So, According to the modern approach for Sales account:Read more

    The journal entry for Cash Sales is-

    Particulars Amount Amount
    Cash A/c                                                      Dr $$$
         To Sales A/c $$$

    Sales Account is a Revenue Account and Cash Account is an Asset Account for the business.

    So, According to the modern approach for Sales account:

    • When there is an increase in the Revenue, it is ‘Credited’.
    • When there is a decrease in the Revenue, it is ‘Debited’.


    According to the Modern approach for Cash  account:

    • When there is an increase in the Asset, it is ‘Debited’.
    • When there is a decrease in the Asset, it is ‘Credited’.


    So, the journal entry here is about cash sales and since there is an increase in Revenue on account of goods being sold, the sales account will be credited as per the modern rule and due to the increase in cash on account of sales, cash account will be debited.

    For Example, Polard sold goods for cash worth Rs 2,000 for his business.

    I will try to explain it with the help of steps.

    Step 1: To identify the account heads.

    In this transaction, two accounts are involved, i.e. Cash A/c and Sales A/c.

    Step 2: To Classify the account heads.

    According to the modern approach: Sales A/c is a Revenue account and Cash A/c is an Asset account.

    Step 3: Application of Rules for Debit and Credit:

    According to the modern approach: As Sales increases, because goods have been sold, ‘Sales A/c’ will be credited. (Rule – increase in Revenue is credited).

    Cash account is an Asset account. As cash has been received on account of goods sold, there is an increase in assets and hence Cash account will be debited (Rule – increase in Asset is debited).

    So from the above explanation, the Journal Entry will be-

    Particulars Amount Amount
    Cash A/c                                                      Dr 2,000
         To Sales A/c 2,000


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Accounting Terms & Basics

Can you explain interest on drawings?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 25, 2022 at 8:39 pm
    This answer was edited.

    Interest on drawings Drawings refer to the money withdrawn by owners/partners for personal use from the business. The drawings, in accounting terms, can be of any type. It can be cash withdrawn from business or furniture or car etc. Drawings are money or assets that are withdrawn from a company by iRead more

    Interest on drawings

    Drawings refer to the money withdrawn by owners/partners for personal use from the business. The drawings, in accounting terms, can be of any type. It can be cash withdrawn from business or furniture or car etc. Drawings are money or assets that are withdrawn from a company by its owners for personal use and must be recorded as a reduction of assets. It’s paid back to the business with some interest.

    Interest on drawings is an income for the business and reduces the capital of the owner. Interest on drawings is the amount of interest paid by the partners, calculated concerning the period for which the money was withdrawn.

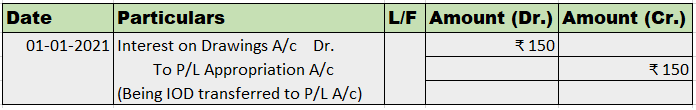
    • It’s an income for the business. Hence, credited to P&L Appropriation A/c.
    • It’s an expense for the owner/partner. Therefore, debited to owner’s/partner’s capital a/c
    • Interest on drawings is charged to the partners only when there is an agreement made among the partners in this regard or if it is mentioned in the Partnership Deed.

    Formulae for Interest on drawings

    There are three formulae used for calculating the interest on drawings. They are:

    1. Simple Method: In this method, as the name suggests, the amount of interest on drawings is calculated simply for the time the amount has been utilized.

    Interest on Drawings = Amount of drawings × Rate/100 × No. of Months/12 

    2. Product Method: This method is used when-

    • Drawings are made of unequal amounts at irregular intervals of time. Then this formula is used-

    Interest on Drawings = Total of Products × Rate/100 × 1/12

    • When drawings are made of equal amounts at regular/equal intervals of time. Then interest on drawings can be calculated on the total of the amount drawn, for the average of the period applicable to the first and last installment.

    Interest on Drawings= Total amount of drawings × Rate/ 100 × Average Period/12

    Also, note-

    Average Period = (No. of months left after first drawings+ No. of months left after last drawings)/2

    Example:

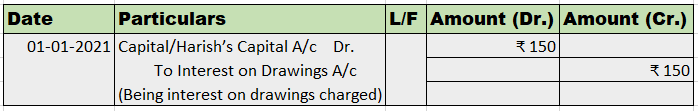
    Harish withdrew equal amounts at the beginning of every month for 9 months. Total drawings amounted to ₹6,000. Calculate the interest on drawings charged if the rate was 6% p.a.

    Solution:

    Average period = (No. of months left after first drawings+ No. of months left after last drawings)/2 = (9+1)/2 = 5 months 

    Interest on Drawings = Total of drawings × Rate/100 × 5/12

                                            = ₹ 6,000 × 6/100 × 5/12
                                            = ₹ 150.

    Journal entry for interest on drawings: 

    Interest transferred to Profit & Loss A/c:


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What is the best example of accrual accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. Saurav
    Added an answer on October 5, 2023 at 7:07 am

    Accrual Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irrespective of the fact when such amount has been paid. An accrual of the expenditure which is not paid will be listed in the books of accounts. These accruals can be furtRead more

    Accrual

    Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irrespective of the fact when such amount has been paid.

    An accrual of the expenditure which is not paid will be listed in the books of accounts. These accruals can be further divided into two parts


    Accrual Expense-

    Accrual Expense means any transaction that takes place in a particular period but the amount for it will be paid on a later period.

    For example- If rent of 10,000 for the month of March was paid in April month then this rent will be accounted for in the books in March

    For example- Interest of 1,000 for the month of March of the loan amount of 10,000 paid in April then will be accounted for in the books in March

    These are the following accrued expense

    • Accrual Rent– Accrual rent means the amount for using the land of the landlord is paid at a later period than the period when it is put into use.
    • Accrual Insurance– Accrual insurance means the amount paid as a premium to the insurance company paid on a later period than the period when it is due
    • Accrual Expense- Acrrual expense means the amount for any expense paid on a later period than the period when it pertains to be paid
    • Accrual Wages- Accrual wages means the amount which is paid to employees on a later period than the period when the wages get due
    • Accrual Loan Interest– Loan Interest means the amount of interest on a loan which is paid on a later period than the period when it is due on


    Accrual Revenue-

    Accrual Revenue means any transaction that takes place in a particular period but the amount for it will be received in the later period.

    For example- If interest of 10,000 on bonds for the period of March is received in April months then this amount will be accounted for in March. These are the following accrued revenue

    For example- Rent of 10,000 for the month of March received in April month then this rent will be accounted for in the books in March

    • Accrual Income- Acrrual expense means the amount for any income received on a later period than the period when it pertains to be received
    • Accrual Rent– Accrual rent means the amount for using the land of the entity by the other party is received at a later period than the period when it is put into use.
    • Accrued Interest– Accrued interest means the amount of interest received on a later period than the period when it pertains to receive
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
prashant06
prashant06
In: 1. Financial Accounting > Miscellaneous

What are prepaid expenses?

  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on August 17, 2021 at 11:23 am
    This answer was edited.

    Prepaid expenses are those expenses that have not been expired yet but their payment has already made in advance. There are many examples of prepaid expenses such as rent paid in advance, interest paid in advance, unexpired insurance You might be wondering what kind of account it is? As the name sugRead more

    Prepaid expenses are those expenses that have not been expired yet but their payment has already made in advance. There are many examples of prepaid expenses such as rent paid in advance, interest paid in advance, unexpired insurance

    You might be wondering what kind of account it is? As the name suggests it should be an expense but actually it’s an asset. When we initially record prepaid expenses we consider them as current assets and show them in the balance sheet. It turns out to be an expense when we use the service/item for what we have paid for in advance.

    The entry for the above explanation is as follows:

    From the modern rule, we know Assets and expenses increased are debits while decrease in assets and expenses are credit.

    As this is asset, increase in asset therefore we debit prepaid expense and on the other hand we pay cash/ bank on behalf of that asset in advance hence there is decrease in assets hence credited. The entry will be as follows:

    Prepaid Expense A/c                                                  …….Dr XXX
               To Cash/ Bank XXX

    when this prepaid expense actually becomes expense we pass the adjusting entry. The entry will be as follows:

    Expense A/c                                                               …….Dr XXX
               To Prepaid expense XXX

    Let me give you simple example of the above entry.

    Suppose you pay advance rent of Rs 9,000 for six months for the space you haven’t used yet. So you need to record this as prepaid expense and show it on the asset side of the balance sheet under current assets. Since you paid for the same the entry would be as follows:

    Prepaid Rent A/c                                                  …….Dr 9,000
               To Cash/ Bank 9,000

    As each month passes we will adjust the rent with prepaid rent account. Since the rent was advanced for 6 months, therefore (9,000/6) Rs 1500 will be adjusted each month with the rent expense account. The adjustment entry will be:

    Rent A/c                                                               …….Dr 1,500
               To Prepaid rent 1,500

    The process is repeated until the rent is used and asset account becomes nil.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ishika Pandey
Ishika PandeyCurious
In: 1. Financial Accounting > Miscellaneous

Why is profit and loss suspense an asset?

  • 0 Answers
  • 1 Follower
Answer
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.