Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Accounting Terms & Basics

What is Gross profit versus net profit?

  • 1 Answer
  • 1 Follower
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses. When the result of this computation is negative it is referred to as gross loss Formula : ToRead more

    Definition

    Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses.

    When the result of this computation is negative it is referred to as gross loss

    Formula :

    Total Revenues – Cost Of Goods Sold

    Net profit is defined as the excess of revenues over expenses during a particular period.

    When the result of this computation is negative it is called a net loss.

    Net profit may be shown before or after tax.

    Formula :

    Total Revenues – Expenses
    Or
    Total Revenues – Total Cost ( Implicit And Explicit Cost )

    The basic difference between gross profit and net profit is that gross profit estimates the profitability of a company whereas net profit is to show the performance of the company.

    Key points of Gross Profit

    Some of the key points of as for gross profits follows :

    • Stage of calculation: Gross Profit is calculated in the first stage of the Final Account.

    • Purpose of calculation: It is calculated to know the total profit earned during the particular accounting

    • Type of balance: Gross Profit shows the credit balance of the Trading Account.

    • Dimension: It is a narrow concept as it is a part of Net Profit.

    • Treatment: It is not treated directly in the balance sheet. It is transferred to the Profit And Loss Account.

    Key points of Net Profit

    Some of the key points of as for gross profits follows :

    • Stage of calculation: Net Profit is calculated in the second stage of the Final Account.

    • Purpose of calculation: It is calculated to know the net profit earned during the particular accounting

    • Type of balance: Net Profit shows the credit balance of the Profit And Loss Account.

    • Dimension: It is a wider concept as it includes Gross Profit.

    • Treatment: It is treated directly in the balance sheet by adding or subtracting from the capital.

    Examples

    Now let me explain to you by taking an example which is as follows :

    In a business organization there were the following data given as purchases made Rs 73000, inventory, in the beginning, was Rs 10000, direct expenses made were Rs 7000, closing inventory which was Rs 5000, revenue from operation during the period was Rs 100000.
    Then,
    COST OF GOODS SOLD = Purchases + Opening Inventory + Direct Expenses – Closing Inventory.
    = Rs ( 73000 + 10000+ 7000- 5000)
    = Rs 85000

    GROSS PROFIT = REVENUE – COST OF GOODS SOLD
    = Rs ( 100000 – 85000 )
    = Rs 15000

    Now from the above question keeping the gross profit same if the indirect expenses of the organization are Rs 2000 and the other income is Rs 1000.
    Then,

    NET PROFIT = GROSS PROFIT – INDIRECT EXPENSES + OTHER INCOMES
    = Rs ( 15000 – 2000 + 1000)
    = Rs 14000

    Conclusion

    So here I conclude that gross profit is the difference between revenues from sales and/or services rendered and its direct cost.

    Whereas net profit is after the deduction of total expenses from the total revenues of the enterprise.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is debit balance class 11?

  • 1 Answer
  • 5 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 14, 2023 at 2:55 am
    This answer was edited.

    Definition Debit balance may arise due to timing differences in which case income will be accrued at the year's end to offset the debit. The amount is shown in the record of a company s finances, by which its total debits are greater than its total credits. The account which has debit balances are aRead more

    Definition

    Debit balance may arise due to timing differences in which case income will be accrued at the year’s end to offset the debit.

    The amount is shown in the record of a company s finances, by which its total debits are greater than its total credits.

    The account which has debit balances are as follows:

    • Assets accounts
    Land, furniture, building machinery, etc

    • Expenses accounts
    Salary, rent, insurance, etc

    • Losses
    Bad debts, loss by fire, etc

    • Drawings
    Personal drawings of cash or assets

    • Cash and bank balances
    Balances of these accounts

    In class 11th, we learned about all these accounts that have debit balances.
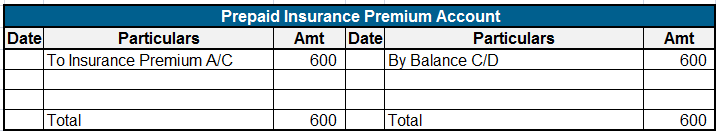
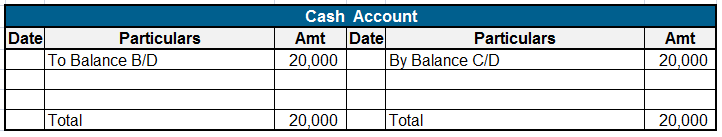
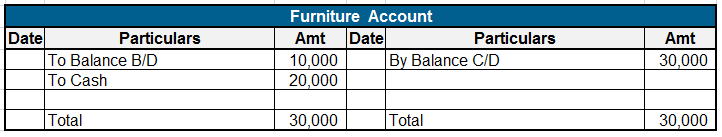
    Where the total of the debit side is more than the credit side therefore the difference is the debit balance and is placed credit side as “ by balance c/d “

    Here are some examples showing the debit balances of the accounts :
    See less
    • 6
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is managerial remuneration?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on November 30, 2021 at 7:12 pm
    This answer was edited.

    The major affairs of the company are handled by the manager and hence he is entitled to receive some compensation for his efforts. This is termed Managerial Remuneration. The manager has to bring out the maximum potential of the employees while ensuring that the interests of the shareholders and othRead more

    The major affairs of the company are handled by the manager and hence he is entitled to receive some compensation for his efforts. This is termed Managerial Remuneration. The manager has to bring out the maximum potential of the employees while ensuring that the interests of the shareholders and other stakeholders are secured.

    MAXIMUM REMUNERATION

    As per section 197 of the Companies Act, the Company has certain limits on paying maximum remuneration, depending on whether he is working full-time or part-time. If the company has only one whole-time manager, he is entitled to a maximum remuneration of 5% of net profits. If there is more than one whole time manager, then the percentage increases to 10%.

    For part-time directors, the remuneration allowed is 1% of net profits (if there is a whole-time director present) and if no whole-time manager is present, then remuneration for a part-time director is 3%.

    Therefore, a company can only pay a maximum remuneration of 11% of net profits.

    A public company is allowed to pay remuneration in excess of 11% by :

    • Passing a special resolution approved by the shareholders
    • Subject to compliance with Schedule V conditions

    Remuneration can be paid to such managers who do not have any direct interest in the company and also possesses special knowledge and expertise along with a graduate-level qualification.

    PENALTY

    Any person who fails to comply with the provisions of managerial remuneration shall be punishable with a fine that can vary from Rs. 1 Lakh to a maximum of Rs. 5 Lakhs.

    However, Sec 197 applies to only public companies and hence private companies are free to pay managerial remuneration with no upper limit.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

What is the meaning of accrued expenses in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on January 13, 2023 at 7:12 am
    This answer was edited.

    Accrued expenses are those expenses that have already been incurred but not paid. The business has already received the benefit of these goods or services but is yet to pay for them. For example, X Ltd took an insurance policy on 30th September 20XX. The premium is to be paid annually on 30th SeptemRead more

    Accrued expenses are those expenses that have already been incurred but not paid. The business has already received the benefit of these goods or services but is yet to pay for them.

    For example,

    • X Ltd took an insurance policy on 30th September 20XX. The premium is to be paid annually on 30th September every year for the next 20 years.
    • While preparing the financial statements for the year 20XX – 20XX+1, the business will recognize insurance premiums for the period 30th September, 20XX to 31st March 20XX+1 as an accrued expense. The premium would be actually paid on September 20XX+1.
    • As we can see, the company has already incurred the insurance premium for the period 30th September, 20XX to 31st March 20XX+1.
    • Thus, it has to recognize the same as an expense of that period only even though it will be actually paid in the next accounting period.

    Why does the concept of accrued expenses arise in accounting?

    The concept of accrued expenses arises in accounting because accounting records transactions on an accrual and not cash basis.

    Accounting on an accrual basis implies recording transactions as and when they are incurred while recording transactions on a cash basis means recording them as and when cash is actually paid for receiving those services.

    For example,

    • X Ltd ordered 5 televisions from LG. It received the delivery of all 5 televisions on 1st March, 20XX. However, it received the invoice for those televisions on 31st April, 20XX.
    • Now, the question arises as to whether while preparing the financial statements on 31st March, 20XX, X Ltd will recognize the cost of those 5 televisions as a purchase expenditure.
    • If X Ltd were recording transactions on a cash basis, they would not have recognized the cost of those 5 televisions as a purchase expenditure in the financial statements prepared on 31st March 20XX as the payment had been made in the next financial year.
    • Thus, in that case, that purchase would be recorded in the financial statements of the next year.
    • However, accounting is done on an accrual basis. As per accrual basis, as the event of purchase has occurred during the financial year ending 31st March 20XX, it must be recorded in financial statements for that period only.
    • Thus, due to the accrual basis, X Ltd will record that expenditure in the financial statements prepared on 31st March 20XX even though cash has been paid in the next financial year.

    Treatment of Accrued Expenses

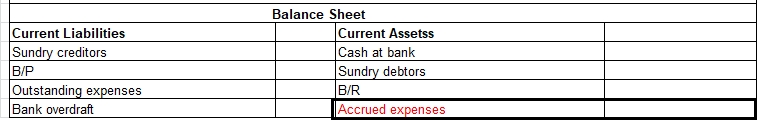
    Accrued expenses are classified as current liabilities. That is because the business has a short-term obligation to pay these expenses. The other party has a legal right to receive the amount due. In other words, accrued expenses become payable in the near term.

    As current liabilities, accrued expenses are carried in the balance sheet on the liabilities side. They are also recognized in the income statement as an expense as per the concept of accrual basis of accounting.

    Conclusion

    Accrued expenses are the expenses for which the business has already received the benefit of goods or services but which are payable in an accounting period other than the one in which such benefit is received.

    As per the accrual basis of accounting, they are recognized in the year in which the expense is incurred. The expense is carried forward as a current liability until the period in which it is actually paid.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Ratios

What are profitability ratios?

  • 1 Answer
  • 0 Followers
Answer
  1. A_Team (MBA - Finance Student) ISB College
    Added an answer on December 13, 2022 at 5:28 am

    Profitability ratios measure how profitable a company is and are used to assess its performance and efficiency. Based on the income statement and balance sheet of a company, these ratios are calculated. In terms of profitability ratios, there are several types, each providing a different viewpoint.Read more

    Profitability ratios measure how profitable a company is and are used to assess its performance and efficiency. Based on the income statement and balance sheet of a company, these ratios are calculated.

    In terms of profitability ratios, there are several types, each providing a different viewpoint.

    The following are some common profitability ratios:

    Gross profit margin: This ratio measures the percentage of revenue that remains after the cost of goods sold has been deducted. Producing and selling efficiently is indicated by this metric.

    Net profit margin: An organization’s net profit margin is the portion of revenue left after all expenses have been deducted. A company’s profitability is measured by this indicator.

    Return on assets (ROA): This ratio measures how profitable a company’s assets are. In other words, it indicates how effectively a company generates profits from its assets.

    Return on equity (ROE): This ratio measures the profitability of a company’s equity. It shows how effectively a company generates profits from its shareholders’ investments.

    Analysts and investors use profitability ratios to evaluate a company’s performance and profitability ability.

    An investor or analyst can evaluate a company’s relative strength and identify potential opportunities or risks by comparing its profitability ratios with its peers or its industry averages.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Miscellaneous

What account is land?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 19, 2022 at 10:18 am
    This answer was edited.

    The land is a fixed asset and is treated as a long-term asset account.  Explanation The land is a fixed asset which is also referred to as a long-term asset. The fixed assets are those assets that are not expected to be cashed, consumed, last, sold, or written off within one accounting year and areRead more

    The land is a fixed asset and is treated as a long-term asset account. 

    Explanation

    The land is a fixed asset which is also referred to as a long-term asset.

    The fixed assets are those assets that are not expected to be cashed, consumed, last, sold, or written off within one accounting year and are purchased for long-term use. The fixed assets are also called non-current assets and the reason behind it is that current assets are easily converted into cash within one year and they are not.

    Fixed assets are planned by the company to be used for the long term in order to generate income.

    Example- Land, building, furniture, plants & equipment, etc.


    Why is land an asset?

    Although the land is not depreciated, it is still considered to be an asset because just like other assets the business spends its own money to acquire it.

    It can also be used by the business for different operations and it doesn’t create any liability for the business. Instead, reselling the land after a few years can help the company earn a huge margin of profit.


    Land in the balance sheet

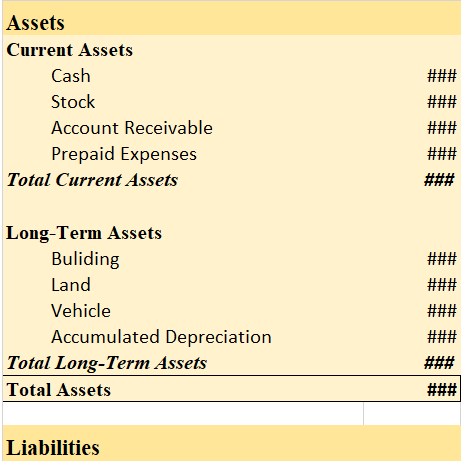
    On the asset side of the balance sheet, the land is stated under the heading long-term assets.

    Balance Sheet (for the year…)


    Therefore, the land is a fixed asset and is treated as a long-term asset account.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Miscellaneous

What is a deferred tax liability?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 11, 2025 at 8:38 am
    This answer was edited.

    Deferred Tax Liability A deferred tax liability represents an obligation to pay taxes in the future. These taxes are owed by a company but are not due to be paid until a future date. Companies that incur such an obligation prepare and maintain two financial reports every year: a tax statement and anRead more

    Deferred Tax Liability

    A deferred tax liability represents an obligation to pay taxes in the future. These taxes are owed by a company but are not due to be paid until a future date.

    Companies that incur such an obligation prepare and maintain two financial reports every year: a tax statement and an income statement.

    This is because companies maintain their books as per book accounting rules (GAAP/IFRS), but they have to pay taxes according to tax accounting rules, and they each have to follow their own guidelines.

    For example, a tax statement follows the cash basis of accounting, and an income statement follows the accrual basis of accounting.

    Companies calculate their profit as per the accounting rules as well as tax laws known as accounting income and taxable income, respectively. Some differences arise due to the application of different provisions of law.

    These temporary differences are accounted for, recognized, and carried forward in the books of accounts and create deferred tax.


    Example

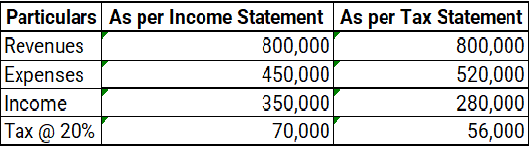
    Here is an example of deferred tax liability.

    In the given example, tax as per income statement is 70,000, whereas as per tax statement it is 56,000. This temporary difference is termed as deferred tax liability of 14,000.

    When accounting income is more than taxable income, it creates Deferred Tax Liability. It will be adjusted in the books of accounts during one or more subsequent year(s).


    How Does it Arise?

    There are several instances under which a company creates a deferred tax liability. Some other instances are:

    Depreciation Methods

    • One of the most common reasons for deferred tax liability is when a company uses different depreciation methods in the Income and Tax Statement.
    • Assets are depreciated by calculating the straight-line method in the Income Statement, while the written-down value method is used in the Tax Statement.
    • Since the straight-line value method produces lower depreciation when compared to the WDV method, accounting income is temporarily higher than taxable income.
    • The company recognises deferred tax liability as this difference between accounting income and taxable income.

    Treatment of Revenue & Expenses

    • Deferred tax liability can also arise when there is a difference in the way revenue and expenses are treated in books of accounts.
    • As mentioned earlier, accounting rules follow the accrual basis of accounting while tax laws follow the cash basis of accounting.
    • Meaning in the tax statement, income and expenses are recorded when they are received or paid, not when they are incurred or realised.
    • This difference in the treatment of revenue and expenses creates deferred tax liability.


    Impact on Financial Statements

    Recognising deferred tax liability and its subsequent effect on the company’s financial statement is important as it simplifies the process of auditing and analysing financial reports.

    Balance Sheet

    • Deferred tax liabilities are recorded on the liability side of the balance sheet under non-current liabilities.

    Cash Flow Statement

    • The deferred tax liability is added back to the net income in calculating cash flow from operating activities to show the actual cash flow.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.