


Profits earned by a firm are not completely distributed to its owners, some of the profits are retained for various purposes. Reserves are profits that are apportioned or set aside to use in the future for a specific or general purpose. Reserves follow the Conservative Principle of accounting. ReveRead more
Profits earned by a firm are not completely distributed to its owners, some of the profits are retained for various purposes. Reserves are profits that are apportioned or set aside to use in the future for a specific or general purpose. Reserves follow the Conservative Principle of accounting.
Revenue reserve is created from the net profits of a company during a financial year. Revenue reserve is created from revenue profit that a company earns from the daily operations of the business.
Various types of reserves are:
- Capital Redemption Reserve: It is created to issue fully paid bonus shares or reduction of capital in accordance with Article 3 of the Companies Act, 2013.
- General Reserve: It is a reserve created to provide for various requirements of the company from time to time.
- Debenture Redemption Reserve: It is required by the Companies Act, 2013 to transfer the amount of debentures that are going to be redeemed in the following year to minimize the risk of default.
- Securities Premium Reserve: When shares and debentures are issued at a price higher than the book value, then such higher amount is transferred to Securities Premium Reserve
- Revaluation Reserve: It is created to revalue the assets and liabilities and provide for gain or loss.
Different parts of profit are apportioned to create a different reserve and those reserves can only be used for purposes as defined.
While accounting for Revenue Reserve, the profit decided to transfer to Revenue Reserve are first transferred to Profit and Loss Appropriation Account and then to Revenue Reserve Account. In the balance sheet, Revenue Account is shown under the Capital and Reserves head.
| Liabilities | Amount | Amount |
| Share Capital | ||
| Reserve and Surplus | ||
| General Reserve | ||
| Capital Redemption Reserve | ||
| Securities Premium Account | ||
| Profit and Loss Account |
Uses of Revenue Reserve:
- Revenue Reserves are created to expand business or for meeting contingencies that may arise in the future.
- It can also be used to distribute dividends or bonus shares to its shareholders.
Example:
Given that Revenue Reserve Account stands at Rs 1,00,000 and the company wants to distribute Rs. 40,000 as dividend to its shareholders. The treatment of this transaction in the financial statements will be-
Particulars Amount (Rs.)
Revenue Reserve Account 1,00,000
(less) Dividend distributed (40,000)
The amount shown in Balance Sheet 60,000
See less







Sales return shows the sale price of goods returned by customers. It is deducted from sales or gross sales in the income statement. It is a contra revenue account that represents returns from the customers and deductions to the original selling price, in case of any defective product received by theRead more
Sales return shows the sale price of goods returned by customers. It is deducted from sales or gross sales in the income statement.
It is a contra revenue account that represents returns from the customers and deductions to the original selling price, in case of any defective product received by the customer or any other manufacturing default.
Sales allowances arise when any customer accepts the product at a lower price than the original price or, in other words, a reduction in the price charged by a seller, due to any problem related to the sold product like a quality issue, an incorrect price charged or shipment issue.
Sales allowances are created before the final billing is paid by the buyer.
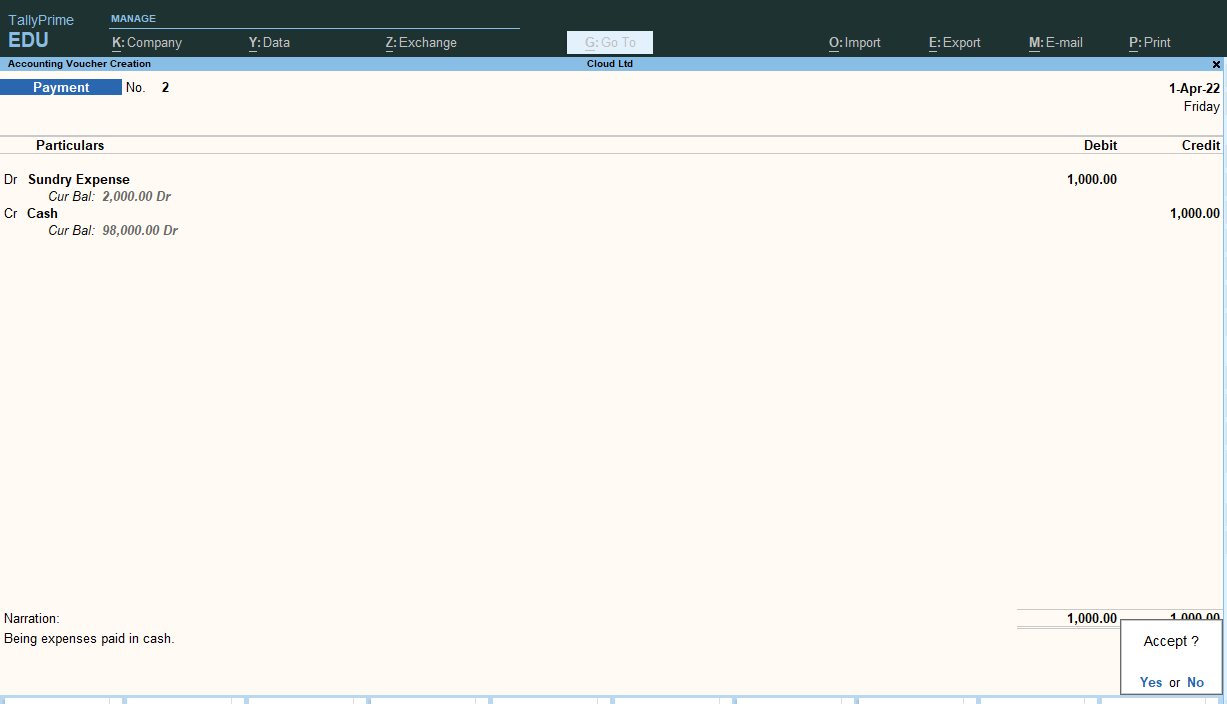
Journal entry for sales return and allowances:
See less