Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Jayesh Gupta
Jayesh GuptaCurious
In: 2. Accounting Standards > AS

When to start charging depreciation on an asset as per AS 10?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on September 21, 2021 at 8:06 pm
    This answer was edited.

    As per AS-10 ( Revised ): Property, Plant and Equipment, depreciation on an asset should begin when the asset is in the location and condition necessary for it to be capable of operating in the manner as intended by the management. This means a firm should start charging depreciation when the assetRead more

    As per AS-10 ( Revised ): Property, Plant and Equipment, depreciation on an asset should begin when the asset is in the location and condition necessary for it to be capable of operating in the manner as intended by the management.

    This means a firm should start charging depreciation when the asset is ready to be used as per the management’s desire.

    Let’s take an example to understand this clearly:

    A business bought a drinking water cooler for its office use on 1st April 2021. Now, this water cooler needs to be installed and wiped with Isopropyl Alcohol before it can be put to use.

    The business completed all the required procedures by 1st May 2021, but it opened the machine for office use from 1st August 2021.

    So the question arises, from when to start charging depreciation?

    • 1st April 2021 – The date of Purchase
    • 1st May 2021- The date when the machine was ready to use.
    • 1st August 2021 –The date from which the machine was put to use.

    The answer is 1st May 2021– The date when the machine was ready to use.

    It doesn’t matter whether the company started the use of an asset or not. Once an asset is in

    • the location and condition
    • necessary for it to be capable of operating
    • as intended by the management,

    the depreciation should begin.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 4. Taxes & Duties > GST

What is the concept of supply in GST?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on March 28, 2022 at 2:19 pm

    Introduction Like, in the case of excise duty, the taxable event is the manufacture of goods, supply is a taxable event with respect to the Goods and Services Tax regime in India. A taxable event is an event on occurrence of which tax is charged. Excise duty is charged when any specified good is manRead more

    Introduction

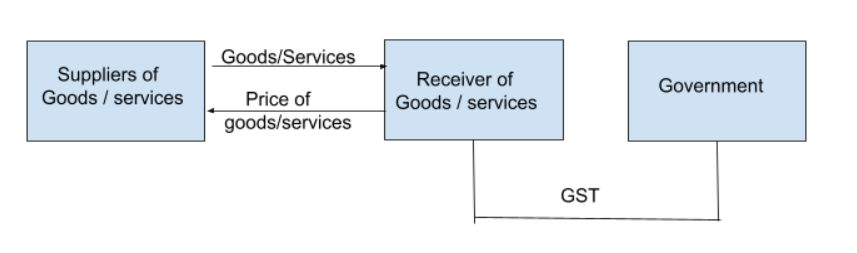
    Like, in the case of excise duty, the taxable event is the manufacture of goods, supply is a taxable event with respect to the Goods and Services Tax regime in India. A taxable event is an event on occurrence of which tax is charged.

    Excise duty is charged when any specified good is manufactured, GST is charged when any good or service is supplied.

    Definition of Supply

    The concept of supply is of great significance to the GST architecture. It can be called the ‘bones to the body of GST’.

    Section 7 of the CGST defines ‘supply’.

    At first, I have provided the whole Section 7 which consists of four sub-sections:

    • 7(1)
    • 7(1A)
    • 7(2)
    • 7(3).

    Thereafter will be the explanation of each sub-section in simple language.

    Section 7

    Section 7(1) of the CGST Act, 2017 defines ‘supply’. As per section 7(1) of the CGST Act, 2017, the supply includes:

    • All forms of supply of goods and services or both such as sale, transfer, barter, exchange, license, rental, lease or disposal made for a consideration by a person in the course or furtherance of business
    • Importation of service, for a consideration whether or not in the course or furtherance of business and
    • The activities specified in Schedule I, made or agreed to be made with or without consideration.

    Section 7(1A) states, ‘where certain activities or transaction constitute as supply in accordance of with the provisions of sub-section (1), they shall be treated either as a supply of good or supply of services as referred to Schedule II.

    Section 7(2) states, ‘notwithstanding with anything contained in sub-section (1).

    • Activities and transactions stated specified in Schedule III or
    • Such activities and transactions undertaken by the Central government, state government or local authority in which they are engaged as public authorities, as may be notified by the government on the recommendation of the Council

    shall not be treated neither as a supply of goods nor a supply of services.

    Section 7(3) states ‘subject to sub-section (1), (1A) and (2), the government may, on the recommendation of the council specify, by the notification, the transaction that is treated as :

    • a supply of goods and not as a supply of services
    • a supply of services and not as a supply of goods.

    Explanation of Section 7 in simple terms.

    Section 7(1) (a) sets three parameters of an activity or transaction to be a supply.

    • Supply should be only of goods and services. Supply of anything other than goods or services like money, securities do not attract GST.
    • Supply should be made for a consideration
    • Supply should be made in the course or furtherance of business

    Any activity or transaction will be treated as a supply if the above parameters are fulfilled as per sub-section (1) clause (a).

    Section 7(1)(b) is actually an exception to the 3rd parameter of supply. Import of service for a consideration will be considered a supply even if it is not made in furtherance of business,

    Section 7(1)(c) states that item in the schedule I will be treated as supply whether there is consideration or not. This is an exception to the 2nd parameter.

    Section 7(1A) states any activity which is a supply as per sub-section (1), shall be classified either as a supply of goods or as a supply of service as per schedule II. There are many activities and transactions which have the characteristics of both goods and services.

    For example, dining in a restaurant.  Schedule II helps to eliminate this confusion and helps to classify such activities or transactions as either supply of goods or supply of services. As per Schedule II, dining or take-away from a restaurant is a supply of service.

    Section 7(2) states the activities which are neither supply of goods nor neither of services even if they fulfilled the condition of the sub-section (1).

    Section 7(3) says that the central government have the power to notify transactions that are to be treated as supply of goods nor as a supply of service or supply of services not as a supply of services

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 4. Taxes & Duties > GST

What is reverse charge in GST?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on January 4, 2022 at 6:06 pm

    Goods and services tax (GST) is an indirect tax that was introduced in place of other indirect taxes like value-added tax, service tax, purchase tax, etc. It was introduced to ensure that only one tax would be applicable all over India. Reverse Charge is a mechanism where the liability to pay tax onRead more

    Goods and services tax (GST) is an indirect tax that was introduced in place of other indirect taxes like value-added tax, service tax, purchase tax, etc. It was introduced to ensure that only one tax would be applicable all over India. Reverse Charge is a mechanism where the liability to pay tax on goods and services lies on the recipient instead of the supplier.

    APPLICABILITY

    Reverse charge is applicable when:

    • It is specified by the CBIC for the supply of certain goods and services.
    • Goods are supplied by an unregistered dealer to a registered dealer.
    • There is a supply of services through an E-commerce operator.

    TIME OF SUPPLY

    As per reverse charge in the case of goods, the time of supply is the earliest of the three:

    • Date of receipt of goods
    • Date of payment
    • The date is immediately after 30 days from the date of issue of invoice from the supplier.

    For example, If goods were received by the supplier on 15th June, and the date of the invoice was on 3rd July but the date of entry in the books of the receiver was 25th June, then the time of supply of goods would be on 15th June.

    As per reverse charge in the case of services, the time of supply is the earliest of the two:

    • Date of payment.
    • Date immediately after 60 days from the date of issue of invoice by the supplier.

    For example, if the date of payment of services provided was on 16th July, and the date of issue of the invoice was on 15th May ( 60 days from 15th May is 14th July), then the time of supply of services would be 14th July.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Miscellaneous

Can you provide a list of external liabilities?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on September 29, 2021 at 7:30 am

    External liabilities are the amounts which a business is obliged to pay to the outsiders (who are not owners of the business). Here is the list of external liabilities:- Accounts payable ( trade creditors and bills payables) Loan taken from outsiders Loan from bank Debentures Public deposits accepteRead more

    External liabilities are the amounts which a business is obliged to pay to the outsiders (who are not owners of the business).

    Here is the list of external liabilities:-

    1. Accounts payable ( trade creditors and bills payables)
    2. Loan taken from outsiders
    • Loan from bank
    • Debentures
    • Public deposits accepted
    1. Outstanding expenses
    • Outstanding salary
    • Outstanding rent
    • Outstanding tax
    1. Interest due on loans taken from outsiders

    The list is not exhaustive.

    Just for more understanding, internal liabilities are those liabilities which a business is supposed to pay back to its owners.  Such as capital balance, profit surplus etc.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Journal Entries

How to do adjustment entry for closing stock?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on December 9, 2021 at 2:25 pm
    This answer was edited.

    The value of inventory at the end of the financial year or balance sheet date is called closing stock. Closing stock includes: Raw Material Work-in-Progress Finished Goods Example: If the value of raw material is Rs 10,000, value of WIP is Rs 5,000 and value of Finished Goods is Rs 15,000 then valueRead more

    The value of inventory at the end of the financial year or balance sheet date is called closing stock. Closing stock includes:

    • Raw Material
    • Work-in-Progress
    • Finished Goods

    Example:

    If the value of raw material is Rs 10,000, value of WIP is Rs 5,000 and value of Finished Goods is Rs 15,000 then value of Closing Stock will be Rs (10,000 + 5,000 + 15,000) = Rs 30,000

    Adjustment entries are done on the accrual basis of accounting, that is, income is recorded when earned and not received and expenses are recorded when incurred and not paid. Adjustment entries are usually made before or after the preparation of the trial balance at the end of the accounting period.

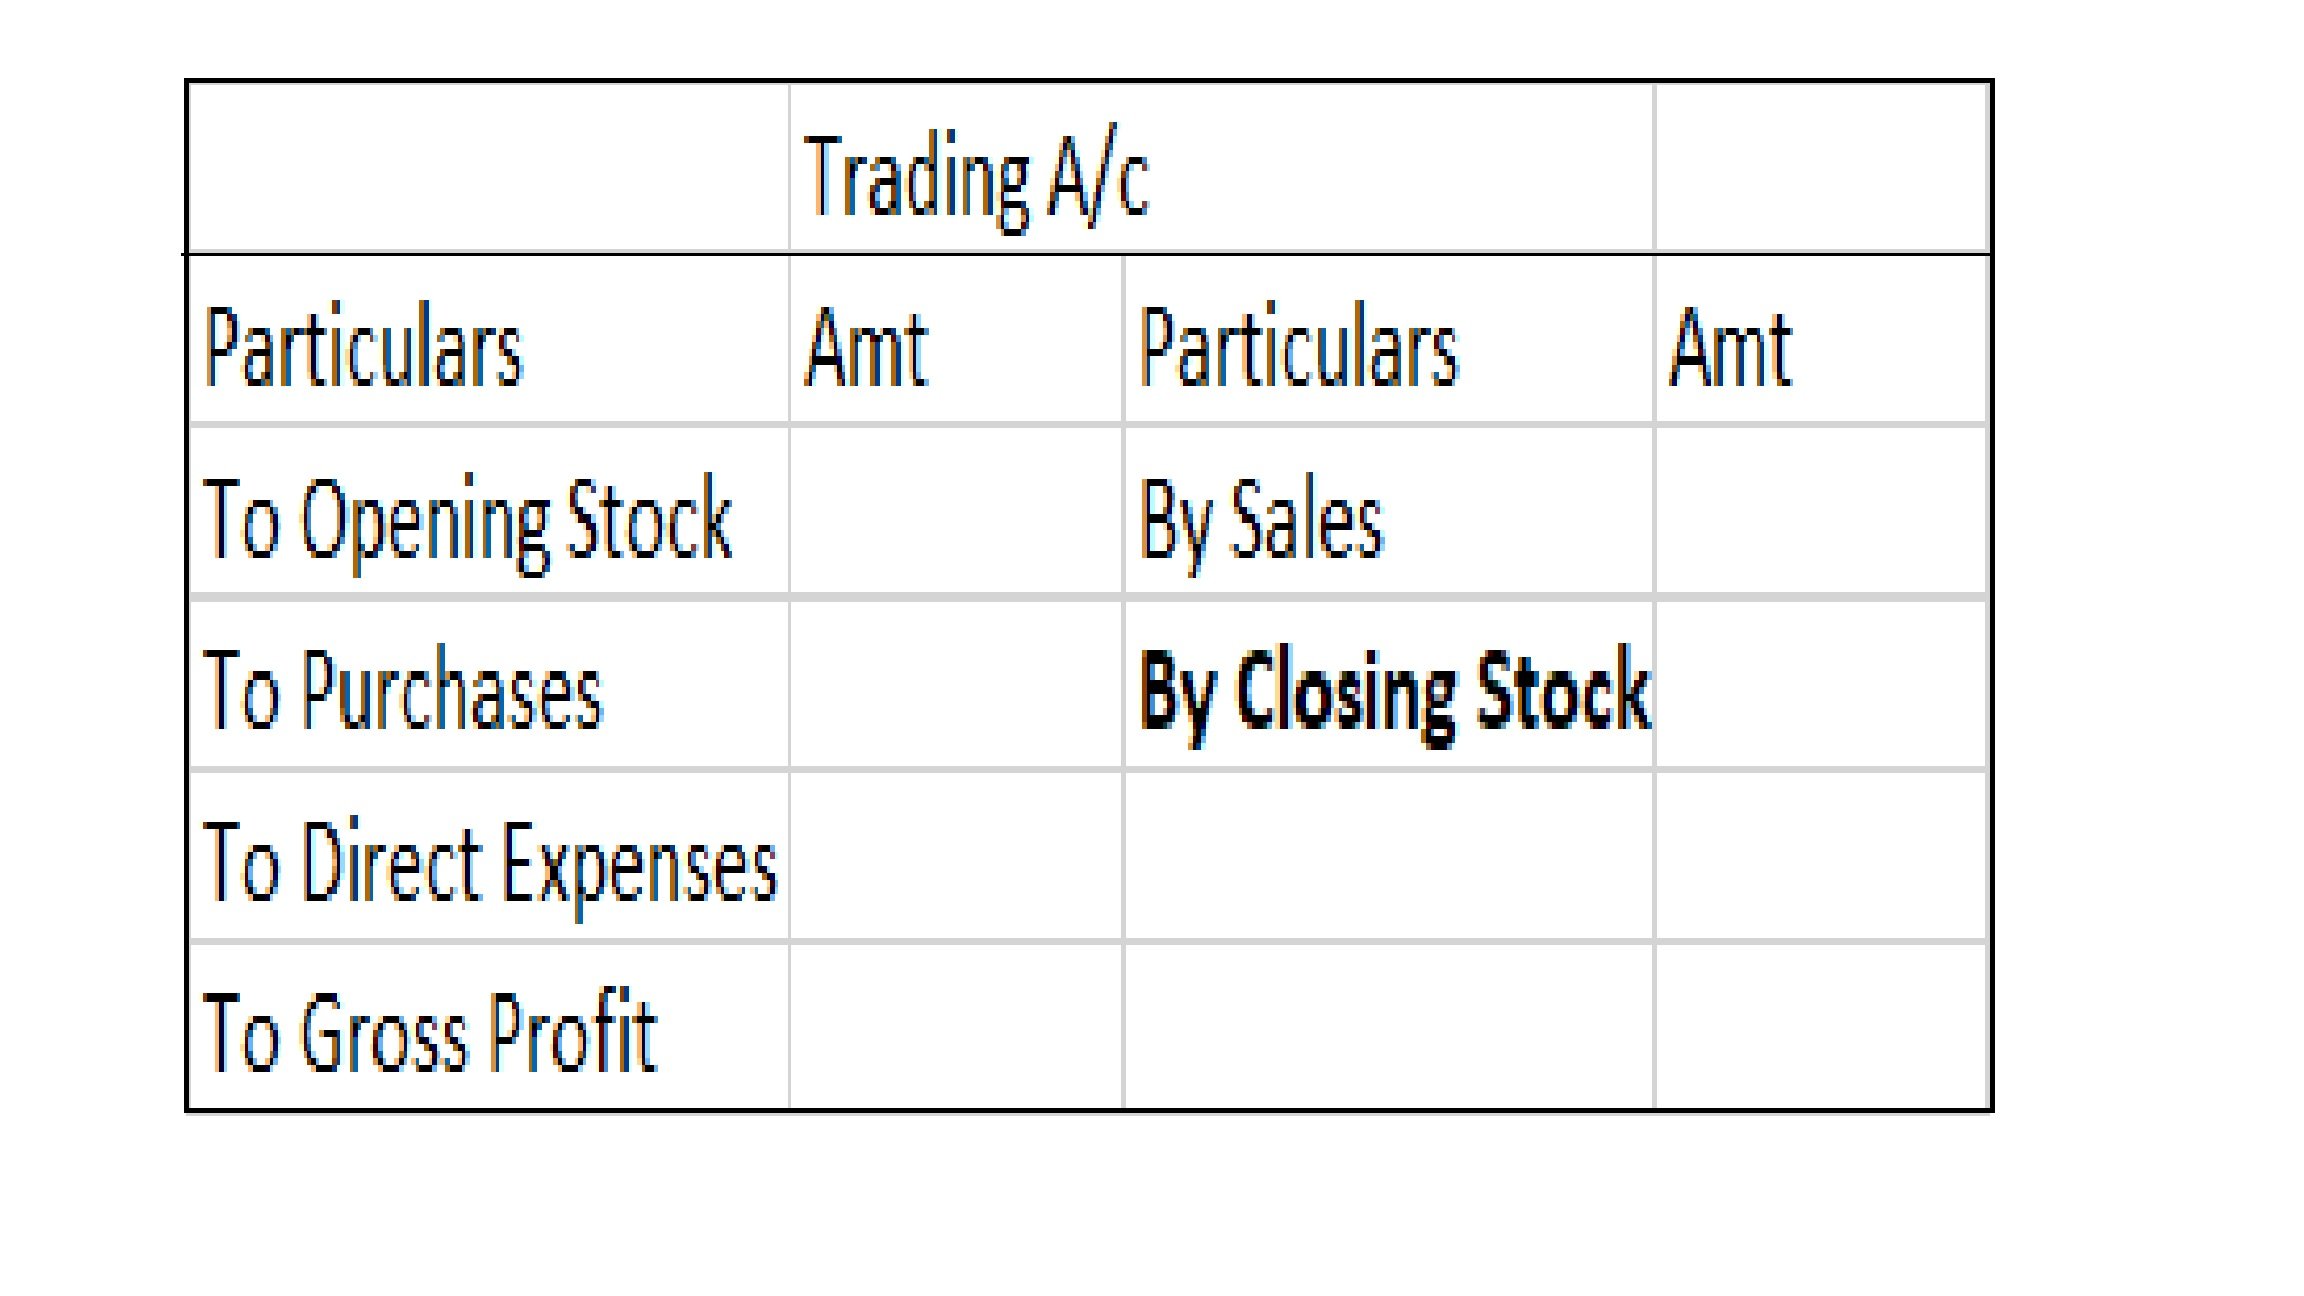
    If the entries are made after the preparation of the trial balance, then two adjustment entries are recorded while preparing Trading and Profit & Loss A/c.

    Since closing stock is an item outside the trial balance, the double-entry would be:

    The journal entry

    Closing Stock A/c  (Dr.) Amt
    To Trading and Profit & Loss A/c Amt
    • Trading and Profit & Loss A/c is credited because it is of profit to the company and hence will be shown on the credit side.
    • Closing Stock is debited as an asset for the company and it will be recorded for the first time in accounting books, hence, will be debited.

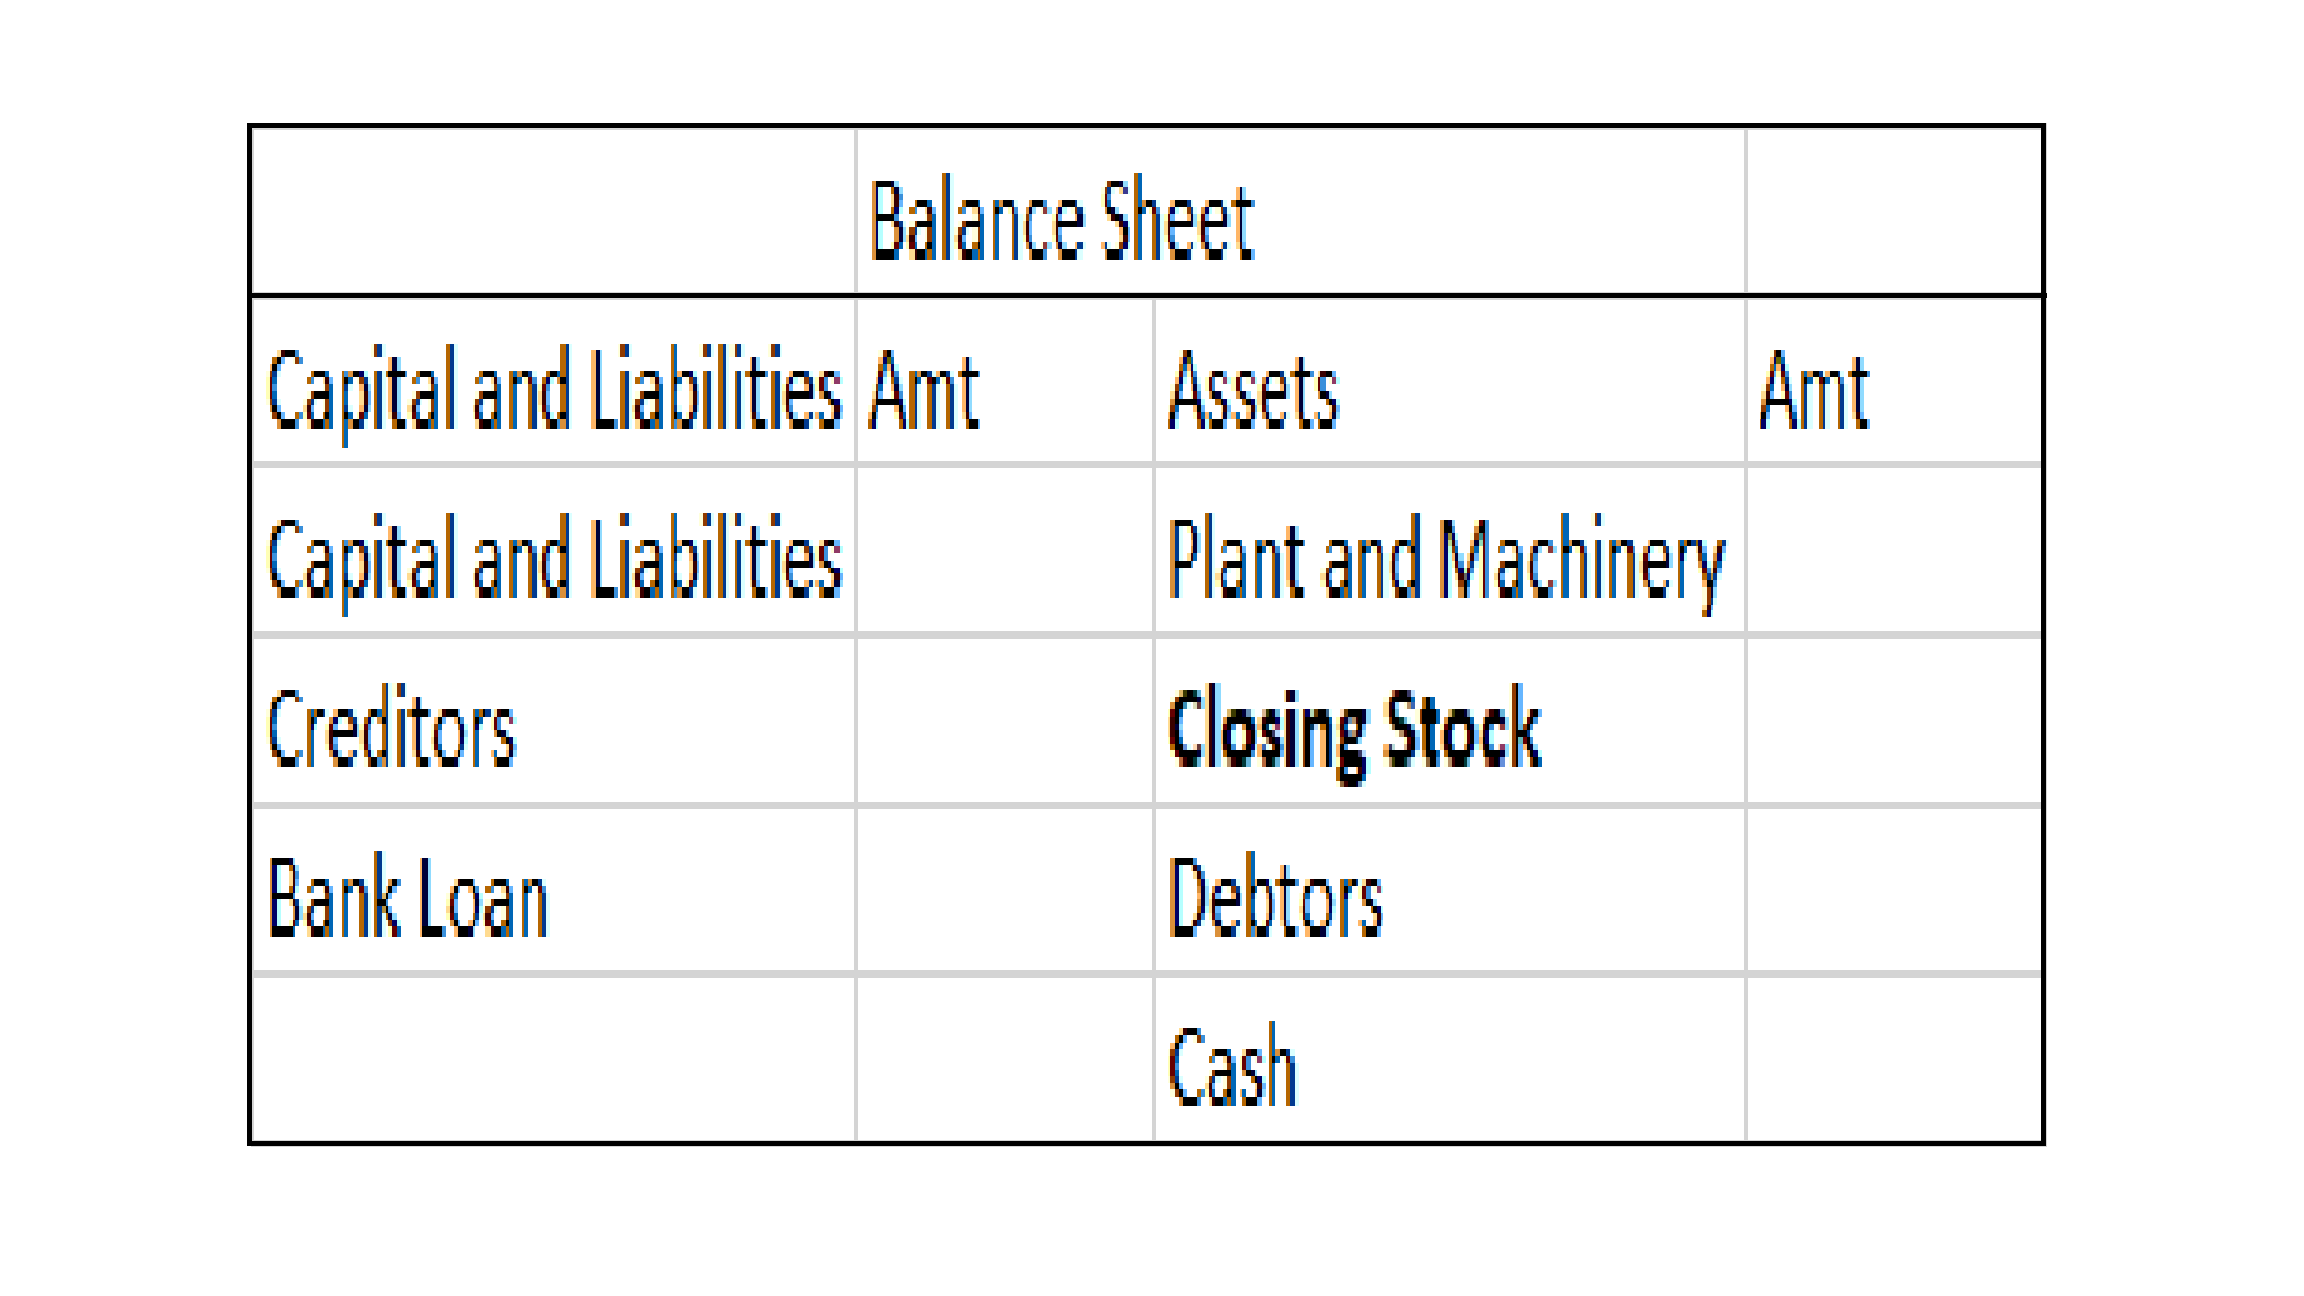
    The second adjustment would be to show closing stock on the balance sheet and since the closing stock is an asset it is shown under the head Current Assets.  

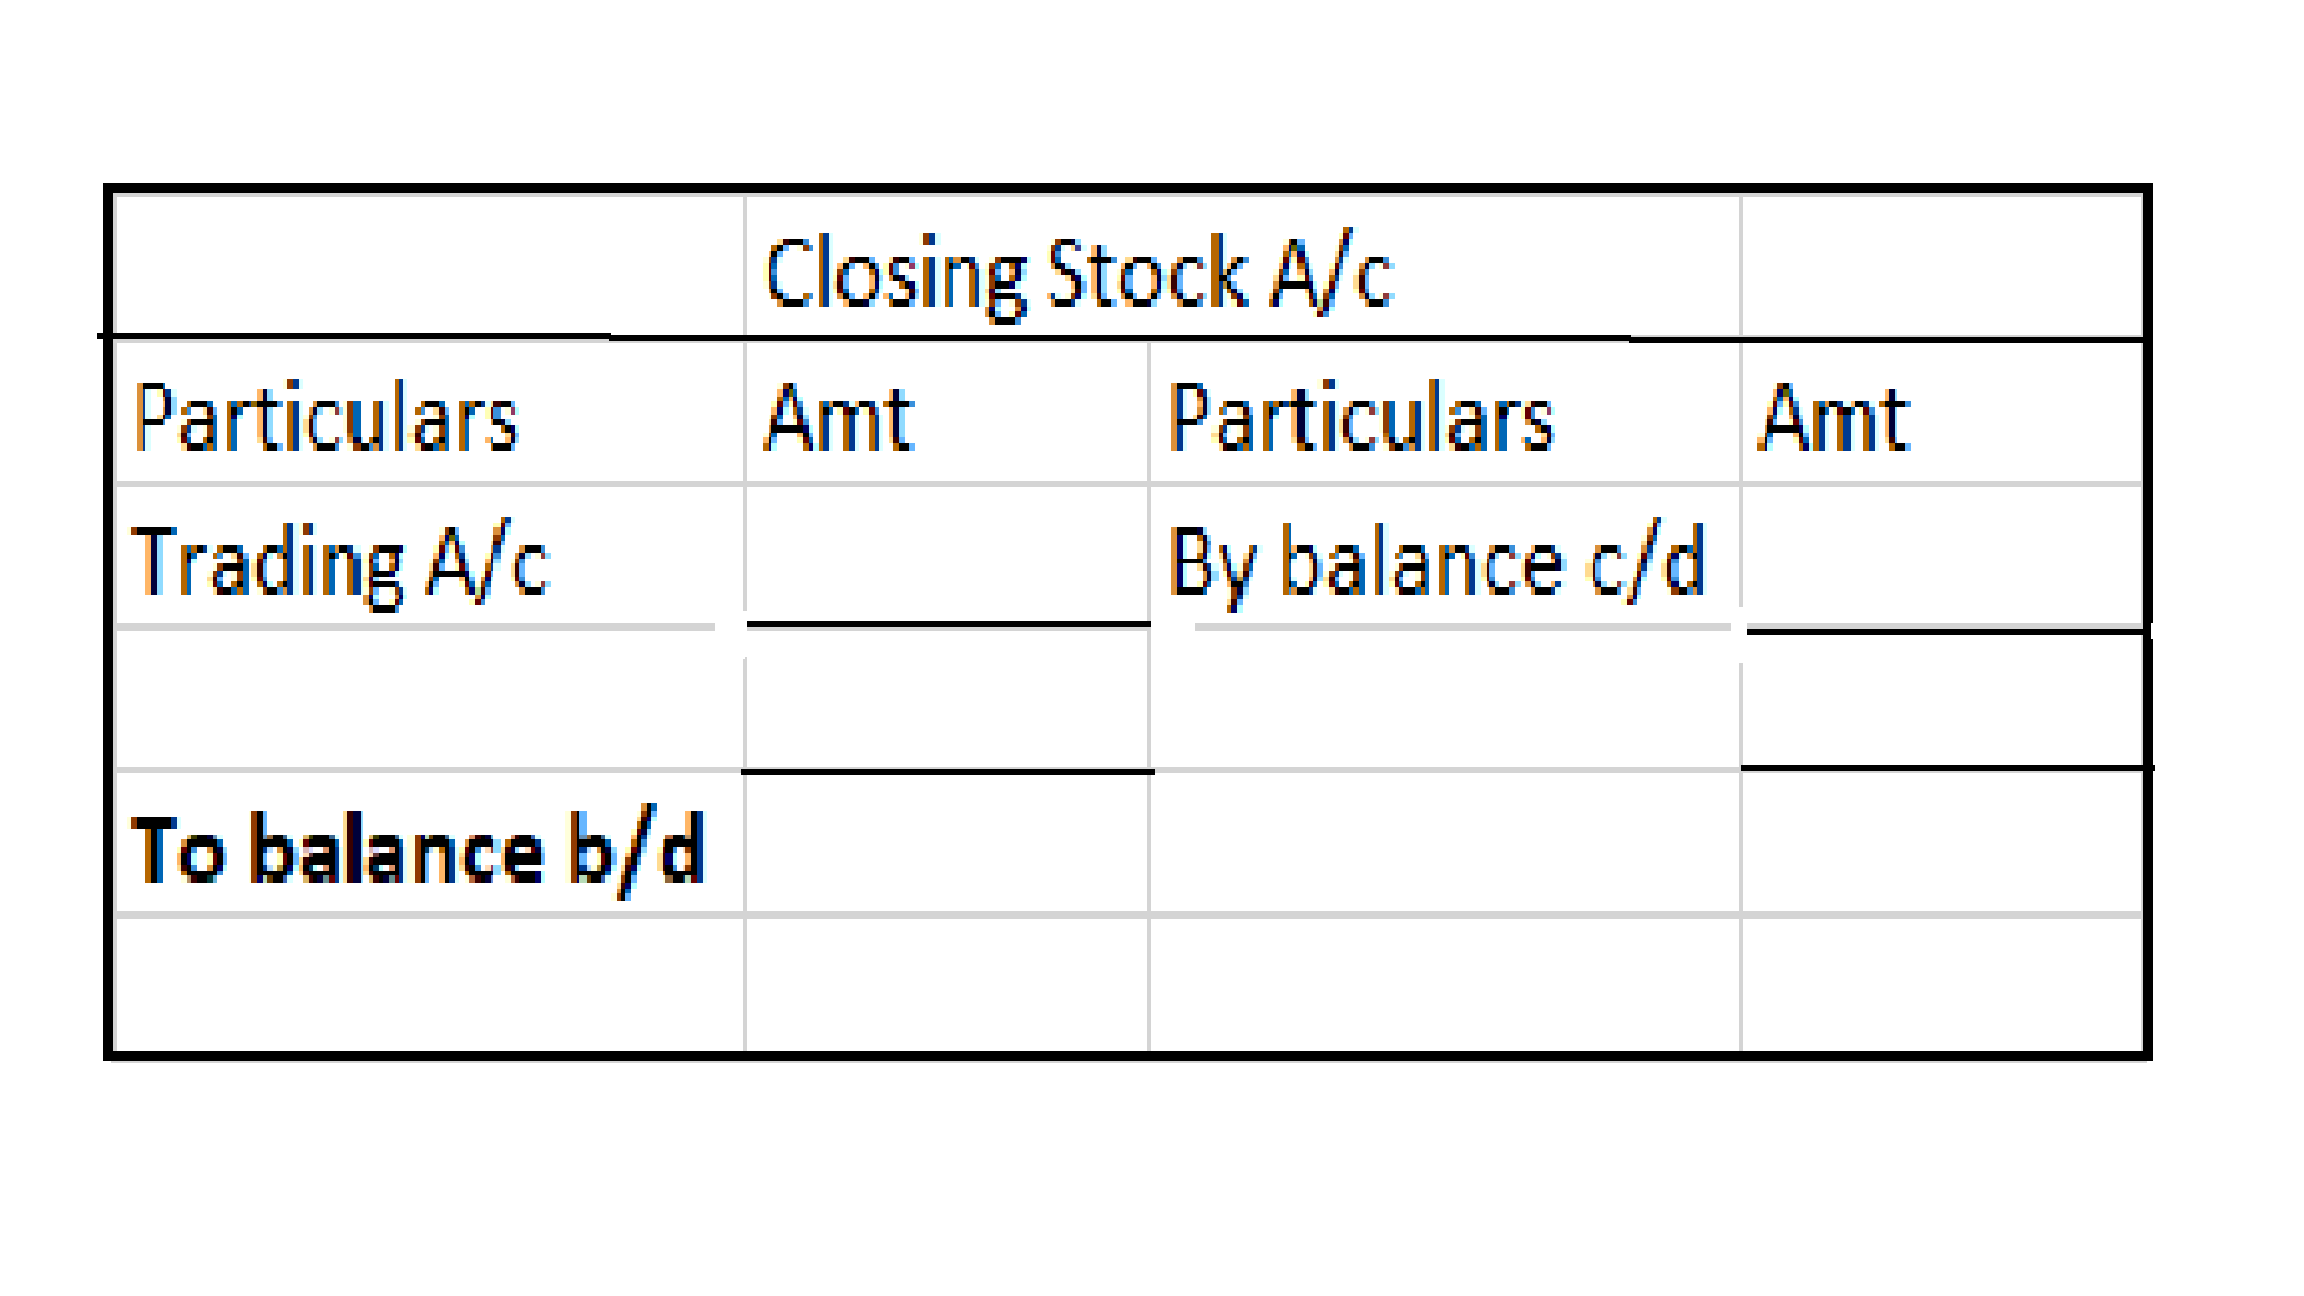
    In case where adjustment for Closing Stock is to be done before preparation of Trial Balance, then it will be shown on the credit side of the Trial Balance, since it is an asset for the company and will have a credit brought down balance as shown in the image.

    Later, while preparing Balance Sheet, Closing Stock will be shown on the Asset side of the Balance Sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 4. Taxes & Duties > GST

What is composite supply and mixed supply?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on April 2, 2022 at 6:36 pm
    This answer was edited.

    Introduction In GST, a supply is a taxable event. This means whenever there is a supply of goods or services or both, GST is charged. Supply includes the exchange of goods or services between supplier and recipient by way of sale, barter, lease etc for consideration and in the course or furtheranceRead more

    Introduction

    In GST, a supply is a taxable event. This means whenever there is a supply of goods or services or both, GST is charged. Supply includes the exchange of goods or services between supplier and recipient by way of sale, barter, lease etc for consideration and in the course or furtherance of business. The rate of GST on any supply depends on the type of good or service supplied.

    Composite supply and mixed supply are two special types of supplies, in which two or more goods or services or both are offered together in a bundle. As two or more goods are supplied together, the question arises at which rate the GST is to be charged on such supplies as such goods or services may have different rates of GST applicable to them. Sections 8 of the CGST act, 2017 deals with the tax liability of such supplies.

    Composite supply

    A composite supply is a type of supply in which two or more goods or services or both are supplied together in the ordinary course of business. Such goods or services are natural bundles. By natural bundle, we mean the goods or services are complementary to each, they are naturally provided together and are to be used along with each other.

    For example, mobile phones and chargers are supplied as a bundle. This concept of the natural bundle is the main determiner of a composite supply.

    In such supplies, there is one main product which is called the principal supply. Like in the above example, the mobile phone is the principal supply. Other goods or services are dependent on the principal supply.

    A composite supply will be taxable as the rate of GST applicable on the principal supply.

    For example, suppose the rate of GST on mobile phones is 18% and that on the charger is 12%, then the whole supply will be taxable at the rate of 18%.

    Mixed supply

    A mixed supply is a type of supply in which two or more goods or services or both are supplied together but they do not complement each other and are not a natural bundle. They are not supplied in the ordinary course of business, For example, a combo of bottled honey and face cream.

    In mixed supply, the good or service which attracts the highest rate of GST is considered the rate of supply for the whole supply.

    For example, suppose bottled honey attracts 5% GST and face cream 18% GST, then the whole supply will be charged 18% GST.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Partnerships

What are unrecorded liabilities?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 19, 2021 at 3:03 pm
    This answer was edited.

    As the name suggests, unrecorded liabilities means the liabilities that a firm fails to record in its book of accounts. Usually, a firm gets to know about its unrecorded liabilities when it is about to get dissolved. What happens is that upon hearing that a firm is going to dissolve in near future,Read more

    As the name suggests, unrecorded liabilities means the liabilities that a firm fails to record in its book of accounts.

    Usually, a firm gets to know about its unrecorded liabilities when it is about to get dissolved. What happens is that upon hearing that a firm is going to dissolve in near future, its creditors and lenders report to the firm about their dues.

    At that time, a firm may get to know that it had failed to record some liabilities in its books and it has settled them now.

    We know that when a partnership firm is dissolved, a realisation account is created to which all the assets and liabilities of the firm are transferred.  Entries are as given below:

    Realisation A/c     Dr.      ₹ Amt

    To Assets A/c                  ₹ Amt

    ( Asset transferred to realisation account)

    Liabilities A/c    Dr.        ₹ Amt

    To Realisation A/c       ₹ Amt

    (Liabilities transferred to realisation account)

    Hence, for transferring unrecorded liabilities, the procedure is the same for the recorded liabilities:

    Unrecorded Liabilities A/c        Dr.     ₹ Amt

    To Realisation A/c                               ₹ Amt

    ( Unrecorded liabilities transferred to realisation account)

    Then to pay off the unrecorded liability the entry is:

    Realisation A/c     Dr.    ₹ Amt

    To Cash / Bank A/c       ₹ Amt

    (Unrecorded liabilities paid off)

    That’s it, I hope I was able to make you understand.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.