
Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

ShreyaSharma
ShreyaSharma
In: 1. Financial Accounting > Subsidiary Books

What are subsidiary books as per 11th?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 25, 2022 at 9:51 pm
    This answer was edited.

    Subsidiary Books Introduction & Definition In large business organizations, it is practically impossible to keep a record of every single business affair, while neglecting them and not recording them wouldn't be an ideal choice, this is where subsidiary books come into the role. As we were introRead more

    Subsidiary Books

    Introduction & Definition

    In large business organizations, it is practically impossible to keep a record of every single business affair, while neglecting them and not recording them wouldn’t be an ideal choice, this is where subsidiary books come into the role. As we were introduced to the basics of accounting in the 11th standard, we learned about different elements like journals, ledgers, trial balances, etc. It is practically impossible for a business to keep track of every single affair just through only those elements. Thus, the Subsidiary book is the next step here.

    Subsidiary books are the books of original entry. They are a dedicated form of books that maintains an analysis of a specific account. It records financial transactions of a similar nature. They are sub-division of a journal.

    In big business organizations, it’s very hard for a bookkeeper or accountant to record all the transactions in one journal and post them into various accounts.  This is where special purpose books or subsidiary books may be required for more efficient bookkeeping. They are a subdivision of journals and for every type of transaction, there is a separate book.


    Types of Subsidiary Books

    There are eight types of subsidiary books that are required for recording transactions. The list of various subsidiary books is as follows:

    1. Cash Book
    2. Purchase Book
    3. Sales Book
    4. Purchase Return Book
    5. Sales Return Book
    6. Journal Proper
    7. Bills Receivable Book
    8. Bills Payable Book


    Types of Subsidiary Books

    Now, we’ll be taking a closer look at each and every subsidiary book.


    Cash Book

     The cash book is the most important subsidiary book, it’s a book of a prime entry recording all the cash spent or received by the business, either in cash form or from the bank. In simple words, recording all the transactions made by the business.

    It is of three types i.e single-column cash book, double-column cash book, and triple-column cash book. As the name indicates, the column of cash, bank, and discount increases/decreases as per the column of the cash book stated.

    Format 


    Note: this is a triple-column cash book format, for the double-column cash book format, we remove the discount column from both sides, and for the single column, we may remove the bank column as well.

    Purchase Book

    A purchase book is a subsidiary book that records all the transactions related to the credit purchase in a business. Thereby, the normal purchasing of assets is never recorded in the purchase book.

    The credit purchases are directly recorded in the purchase book from the journals or the source documents. The source document indicates bills payable, invoices, etc.

    Format


    Sales Book

    A sales book, similar to a purchase book, is a special book where all the credit sales are recorded. The sales book doesn’t record the transactions related to the normal sale of assets and hence, is a special type of book, just like the purchase book.

    Format


    Purchase Return Book

    The purchase return book, also known as the return outwards book, is that book that records the goods that were returned by us to the supplier. Thereby, called purchase return book.

    When the goods are returned, a debit note is issued against every return and hence, recorded in the purchase return book.

    Format


    Sales Return Book

    The sales return book, also known as the return inwards book, refers to that subsidiary book that records the goods which were returned to us by the customer.

    For every good returned to us, a credit note is issued to the customer. And thus, it is recorded in the sales return book.

    Format


    Journal Proper

    Just like we recently learned in class 11th about what a journal entry is and how it is made, it’s a little different from the journal proper. Journal proper is a subsidiary book that records all the transactions which are not recorded in other subsidiary books.

    A journal is an original book of entries that records all the business transactions, while a journal proper is a subsidiary book in which all types of miscellaneous credit business transactions are recorded that do not fit anywhere in the other subsidiary books. Its format is the same as the journal entries’ format. Therefore, it’s also known as a miscellaneous journal.

    Format


     Bills Receivable Book

    The bills receivable book is the book that draws the bills favorable to the business i.e when the goods or services are provided to any customer on credit, they become a debtor, and bills receivable is a written note received from the customer indicating that they formally agree to pay the sum of money owed.

    Therefore, it helps in recording these types of transactions. The sum total of the bills receivable book is posted to the bills receivable account.

    Format


    Bills Payable Book

    The bills payable book is the subsidiary book that records all the bills that are drawn on the company. The bills payable is drawn on the company when we buy a good/service on credit and agrees to pay the amount to the supplier by signing a written note with the date we agree to pay.

    It’s a liability of the business and the total of the bills payable book is posted on the credit side of the bills payable account.

    Format


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
prashant06
prashant06
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation of fixed capital assets refers to?

A. Normal wear and tear B. Foreseen obsolescence C. Normal wear & tear & foreseen obsolescence D. Unforeseen obsolescence  

DepreciationFixed Assets
  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on July 14, 2021 at 2:25 pm
    This answer was edited.

    Depreciation of fixed capital assets refers to C. Normal wear & tear & foreseen obsolescence. Normal wear & tear refers to the damage caused to an asset due to its continuous usage. Even when the asset is properly maintained, wear and tear occurs. Hence, it is considered to be inevitableRead more

    Depreciation of fixed capital assets refers to C. Normal wear & tear & foreseen obsolescence.

    Normal wear & tear refers to the damage caused to an asset due to its continuous usage. Even when the asset is properly maintained, wear and tear occurs. Hence, it is considered to be inevitable and natural.

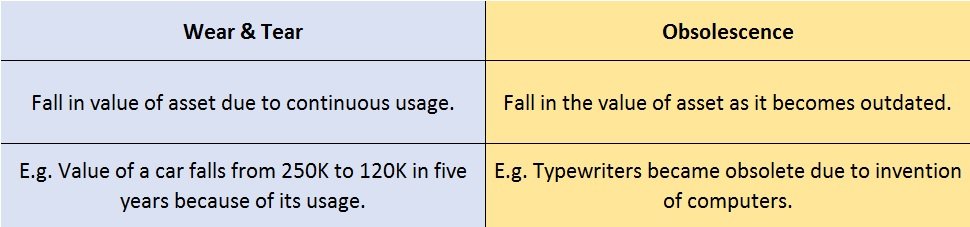
    For example, Kumar has purchased a car for 25,00,000. After five years he wishes to sell his car. Now the market price of his used car is 12,00,000. This reduction in the value of the car from 25,00,000 to 12,00,000 is because of its usage. This fall in the value of the asset due to usage is known as normal wear & tear.

    In generic terms, obsolescence means something that has become outdated or is no longer being used. Foreseen obsolescence is nothing but obsolescence that is expected.

    In the context of business, whenever the value of an asset falls because it has become outdated or is replaced by a superior version, we call it obsolescence. The fall in the value of the asset due to obsolescence expected by the purchaser of the asset is known as foreseen obsolescence.

    When an asset becomes obsolete it doesn’t mean it is not in working condition. Even when an asset is in good working condition it can become obsolete due to the following reasons:

    • Technology advancement.
    • Change in demand (change in fashion, change in taste and preferences of the consumers, etc.)


    For example, before the invention of computers, people used typewriters for getting their paperwork done. With the invention of computers, laptops, etc. it is easier to type as well as save our documents, spreadsheets, etc. Thus typewriters became obsolete with the invention of computers. It has become a technology of the past.

    Here is a summarised version of wear & tear and obsolescence:
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 4. Taxes & Duties > Income Tax

Is agricultural income taxable in India?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 28, 2021 at 10:21 am
    This answer was edited.

    Income derived from farming land, building constructed or associated with farming land, and commercial products from farming land is called agricultural income. According to Section 10(1) of the Income Tax Act, agricultural income is exempt from tax. However, the government can levy tax if agricultuRead more

    Income derived from farming land, building constructed or associated with farming land, and commercial products from farming land is called agricultural income.

    According to Section 10(1) of the Income Tax Act, agricultural income is exempt from tax. However, the government can levy tax if agricultural income is above Rs 5,000.

    Following are the sources to be considered for agricultural income according to the conditions mentioned in Section 2 (1A) of the Income Tax Act:

    • Revenue generated through rent or lease of land in India that is used for agricultural purposes.
    • Revenue generated through the commercial sale of produce gained from agricultural land.
    • Revenue generated through the renting or leasing of buildings in and around the agricultural land subject to the following conditions:
    • The cultivator or farmer should have occupied the building, either through rent or revenue.
    • The building is used as a residential place, storeroom, or outhouse.
    • The agricultural land or the land where the building is located, is being assessed for land revenue or subject to a local rate assessed.

    If the land does not fall under the provisions stated above, the Income Tax Act requires a separate evaluation to calculate tax.

    The Income-tax Act has laid down a method to indirectly tax such income.
    This method or concept is called the partial integration of agricultural income with non-agricultural income. It aims at taxing the non-agricultural income at higher rates of tax.

    Partial integration of agricultural income with non-agricultural income involves the following steps:

    1.  For example, the base income of the individual is Rs. 20,000 and agricultural income is Rs 10,000, then we first have to calculate tax on Rs 30,000. For convenience, we can call this tax T(30,000)
    2. Assuming that the income falls under tax slab A, this tax slab A has to be added to the agricultural income and tax has to be calculated on it as well and it is called T(S+10,000).
    3. The final tax on the individual’s income will be T(30,000)- T(A+10,000)

    The important step to keep in mind is to aggregate the agricultural income while calculating tax otherwise it can lead to double taxation, extra tax, or interest on tax.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Partnerships

What is the difference between dissolution of partnership and dissolution of firm?

Difference BetweenDissolution of FirmDissolution of Partnership
  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 12, 2021 at 1:35 pm
    This answer was edited.

    Dissolution of partnership means partnership coming to an end while the firm still stands. Various reasons for the dissolution of partnership could be: Admission of a partner Death of a partner Retirement of a partner Dissolution of firm In the event of the above cases, the existing partnership is dRead more

    Dissolution of partnership means partnership coming to an end while the firm still stands. Various reasons for the dissolution of partnership could be:

    • Admission of a partner
    • Death of a partner
    • Retirement of a partner
    • Dissolution of firm

    In the event of the above cases, the existing partnership is dissolved and a new partnership is created with the new partners without affecting the firm.

    A new partnership deed is created, in case there is a partnership deed agreed among partners and new profit-sharing ratios among the partners are decided, while the assets and liabilities of the firm remain the same.

    Dissolution of a firm means the firm no longer exists. Various reasons for the dissolution of a partnership firm could be:

    • Mutual decision of partners
    • By the court of law

    A partnership firm is dissolved by a court of law when there has been a non-compliance of law, the firm is engaged in illegal practices, or that the court’s opinion is that it is in the public interest for the firm to be dissolved.

    The partnership is also dissolved with the dissolution of the firm but the converse need not be true.

    When a firm is dissolved, there is a sequence that is followed to pay creditors and partners.

    • First, outside creditors like banks, third party creditors are paid firstly with the cash available with the firm and then by selling the assets.
    • Second, partners who have lent money in the form of a loan to the firm are paid.
    • Lastly, if there is any surplus, partners are paid with the amount of their capital. In case of loss, partners are required to pay from their personal assets.

    Dissolution of the firm can be done by the partners themselves and they could also appoint a third person to do so on the payment of fees, charges, the proportion of surplus, or any contract that has been agreed to.

    To summarize, we can a draw a difference table as follows:

    Dissolution of Partnership Dissolution of Partnership Firm
    The partnership ends but the firm still stands. A partnership firm no longer exists.
    A new partnership deed is created by the mutual agreement of partners. A new partnership firm is created if the partners decide.
    Reasons:

    ·        Admission

    ·        Retirement

    ·        Death

    Reasons:

    ·        By court

    ·        Mutual decision of partners

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Not for Profit Organizations

Prepare Income and Expenditure Account for the Year Ended 31st March, 2020 from the Following?

Receipts and Payments A/C for the year ended 31st March 2020 Receipts Amt Payments Amt To Balance b/d  (Cash)        180,000 By Salary        480,000 To Subscriptions        900,000 By Rent           50,000 To Sale of Investments        200,000 By Stationery           20,000 To Sale ...

  • 1 Answer
  • 0 Followers
Answer
  1. Radha M.Com, NET
    Added an answer on August 22, 2021 at 7:10 am
    This answer was edited.

    Here I've prepared the Income & Expenditure A/c. Income & Expenditure A/c for the year ended 31st March 2021 Expenditure Amt Income Amt To Salary      4,80,000 By Subscriptions      9,00,000 To Rent          50,000 By Donations          10,000 To Stationery          20,000 To Loss on sale ofRead more

    Here I’ve prepared the Income & Expenditure A/c.

    Income & Expenditure A/c for the year ended 31st March 2021

    Expenditure Amt Income Amt
    To Salary      4,80,000 By Subscriptions      9,00,000
    To Rent          50,000 By Donations          10,000
    To Stationery          20,000
    To Loss on sale of furniture (WN)          10,000
    To Surplus      3,50,000
         9,10,000      9,10,000


    Working Note: Calculation of Loss on sale of furniture

    The following calculation is made to identify the loss incurred on the sale of furniture.

    Particulars Amt
    Book Value of Furniture        40,000
    Less: Sale Value of Furniture        30,000
    Loss on Sale of Furniture        10,000


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Financial Statements

Explain provisional financial statements?

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on July 28, 2021 at 9:16 am
    This answer was edited.

    Provisional financial statements are prepared on the basis of past data i.e. for the period which is already over. For example, the bank requested for Q4 financial statement but there were still 15 days left for the quarter to get over. In this case, the business/company will prepare a provisional fRead more

    Provisional financial statements are prepared on the basis of past data i.e. for the period which is already over. For example, the bank requested for Q4 financial statement but there were still 15 days left for the quarter to get over. In this case, the business/company will prepare a provisional financial statement.

    Provisional financial statements can be requested by banks, investors, and large vendors while making decisions regarding business and want current financial statements which can be obtained easily.

    It is prepared with the help of past actual figures on a particular date or before the end of a financial statement. The main purpose of preparing is to show the company’s financial position on a particular date. Items of the provisional financial statement are assets, liabilities, and equity/capital.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of “set off” in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 23, 2021 at 8:22 pm

    The term set off in English means to offset something against something else. It thereby refers to reducing the value of an item. In accounting terms, when a debtor can reduce the amount owed to a creditor by cancelling the amount owed by the creditor to the debtor, it is termed as set off. It is coRead more

    The term set off in English means to offset something against something else. It thereby refers to reducing the value of an item. In accounting terms, when a debtor can reduce the amount owed to a creditor by cancelling the amount owed by the creditor to the debtor, it is termed as set off.

    It is commonly used by banks where they seize the amount in a customer’s account to set off the amount of loan unpaid by the customer.

    Types

    There are various types of set-offs as given below:

    • Transaction set-off – This is where a debtor can simply reduce the amount he is owed from the amount he owes to the creditor.
    • Contractual set-off – Sometimes, a debtor agrees to not set off any amount and hence he would have to pay the entire amount to the creditor even if the creditor owed some amount to the debtor.
    • Insolvency set-off – These rules are mandatory and have to be followed under the Insolvency rules 2016.
    • Bankers set-off – Here, the bank sets off the amount of a customer with another account of the customer.

    Example

    Let’s say Divya owes Rs 20,000 to Sherin for the purchase of goods. But, Sherin owed Rs 6,000 to Divya already for use of her Machinery. Therefore, the amount of 6,000 can be set off against the 20,000 owed to Sherin and hence Divya would effectively owe Sherin Rs 14,000.

    This helps in reducing the number of transactions and unnecessary flow of cash.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.