Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Naina@123
Naina@123
In: 1. Financial Accounting > Subsidiary Books

Overdraft as per cash book means?

1. Credit balance in the cash column of the cash book 2. Credit balance in the bank column of the cash book 3. Neither of the two 4. Both (a) ...

  • 1 Answer
  • 0 Followers
Answer
  1. Radha M.Com, NET
    Added an answer on July 31, 2021 at 9:28 am
    This answer was edited.

    The correct answer is 2. Credit balance in the bank column of the cash book. The credit balance in the bank column of Cash Book represents the overdraft facility utilized by the business. Overdraft is a credit extension facility offered by banks to both savings and current account holders. It allowsRead more

    The correct answer is 2. Credit balance in the bank column of the cash book.

    The credit balance in the bank column of Cash Book represents the overdraft facility utilized by the business. Overdraft is a credit extension facility offered by banks to both savings and current account holders. It allows the account holder to borrow a specified sum of money over and above the balance in their accounts.

    It is a form of short-term borrowing offered by banks and is extremely useful for businesses to resolve short-term cash flow issues.

    The account holder can withdraw money even when his/her account does not have enough balance to cover the withdrawal. Since the business is withdrawing money that is not in its account, an overdraft is represented by a negative bank balance. That is why they are shown as a credit balance in the bank column of the Cash Book.

    Overdraft is a liability for the business. Hence, it is shown on the Equity and Liability part of the Balance Sheet under the head Current Liabilities and sub-head Short Term Borrowings.

    Banks do not offer this facility to all customers. Only those who have a good reputation and credit score are eligible for this facility. Like any other borrowing, interest is charged on the amount utilized by the account holder as an overdraft.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Not for Profit Organizations

What is the accounting equation for non profit organisation?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on August 1, 2022 at 8:14 pm

    The accounting equation for a non-profit organisation is almost the same as in the case of the profit-oriented organisation. Let's first briefly understand what accounting equation and non-profit organisation are: Accounting Equation Accounting equation is an equation that depicts the relationship bRead more

    The accounting equation for a non-profit organisation is almost the same as in the case of the profit-oriented organisation. Let’s first briefly understand what accounting equation and non-profit organisation are:

    Accounting Equation

    Accounting equation is an equation that depicts the relationship between assets, liabilities and capital of an entity.

    Assets = Liabilities + Capital

    As per this equation, the total assets of an entity are equal to the sum of its total liabilities and total capital. This equation holds good in every situation.

    Non-Profit Organisation

    A Non-Profit Organisation is an entity which exists for purposes other than for profit. Such organizations exist and operate for charitable purposes, promotion of culture and sports and welfare of society. The accounting for Non-profit organisation is slightly different from For-profit organisations. In the case of a non-profit organisation, the capital account is known as the capital fund.

    Accounting Equation for non-profit organisations

    The Accounting equation for a non-profit organisation is as follows:

    Assets = Liabilities + Capital fund.

    The difference is only in name. In the case of non-profit organizations, the capital is known as a capital fund. Rest everything is the same. The accounting equation will be prepared as normally prepared for business concerns.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 3. Cost & Mgmt Accounting

Can anyone tell me the meaning of terms “cost driver” & “cost center”?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on November 27, 2021 at 11:54 am
    This answer was edited.

    Under Activity-Based Costing, overheads are accurately assigned to different activities and their costs are determined through costing methods. Activities are those events that incur costs whereas overheads are expenditures that cannot be traced to any particular cost unit. A Cost driver refers to tRead more

    Under Activity-Based Costing, overheads are accurately assigned to different activities and their costs are determined through costing methods. Activities are those events that incur costs whereas overheads are expenditures that cannot be traced to any particular cost unit.

    A Cost driver refers to the factor that causes a change in the cost of an activity. Activity-Based Costing is done to establish a link between the activities and the product. The cost drivers are those links between the activities and the product.

    Cost drivers are divided into four categories:

    • Resource Cost Driver – It is a measure of the number of resources used by an activity. It assigns the cost of a resource to an activity.
    • Activity Cost Driver – It is a measure of the frequency and intensity of demand, placed on activities by cost objects. It assigns activity costs to cost objects.
    • Structural Cost Driver – It results from the economic and technological structure of the industry.
    • Executional Cost Driver – It reflects the firm’s ability to plan and operate its production operations effectively.

    A Cost Centre refers to a department in a business where costs can be allocated. These departments run various processes and incur costs. They can be related to the production of goods or the provision of services. Different centres are allocated different budgets and hence it enables the business to run efficiently by tracking its incomes and expenses easily.

    Proper management of cost centres can help the company cut additional costs from each department. It also helps in more accurate forecasts depending on future changes.

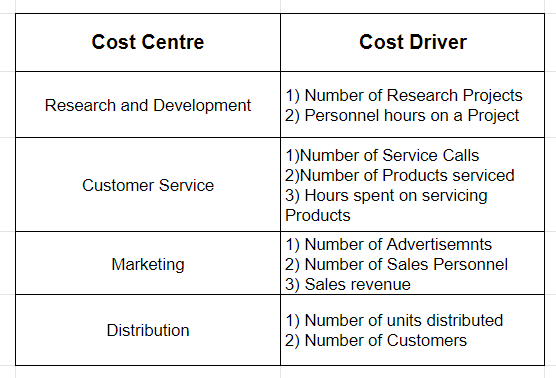
    Cost centres and Cost Drivers are both important factors while following Activity-Based Costing. Some examples of cost drivers and cost centres are as follows :


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Ledger & Trial Balance

Why is trial balance prepared?

  • 2 Answers
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on January 2, 2023 at 10:52 am
    This answer was edited.

    Definition The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances. A trial balance is prepared on a particular date and not on a particular period. Importance As the tRead more

    Definition

    The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances.

    A trial balance is prepared on a particular date and not on a particular period.

    Importance

    As the trial balance is prepared at the end of the year so it is important for the preparation of financial statements like balance sheet or profit and loss

    Purpose of trial balance which are as follows:

      • To verify the arithmetical accuracy of the ledger accounts
      • This means trial balance indicates that equal debits and credits have been recorded in the ledger accounts.
      • It enables one to establish whether the posting and other accounting processes have been carried out without any arithmetical errors.
      • To help in locating errors
      • There can be some errors if the trial balance is untallied therefore to get error-free financial statements trial balance is prepared.
      • To facilitates the preparation of financial statements
      • A trial balance helps us to directly prepare the financial statements and then which gives us the right to not look or no need to refer to the ledger accounts.


    Preparation of trial balance

      • To verify the correctness of the posting of ledger accounts in the terms of debit credit amounts periodically, a periodic trial balance may be prepared ( say ) at the end of the month or quarter, or half year.
      • There is no point in denying that a trial balance can be prepared at any time.
      • But it should at least be prepared at the end of the accounting period to verify the arithmetical accuracy of the ledger accounts before the preparation of financial statements.


    Methods of preparation

    • Balance method
    • Total amount methods


    These are two methods that you can use to prepare trail balance, now let me explain to you in detail about these methods which are as follows:-


    Balance method

    • The balances of all the accounts ( including cash and bank account ) are incorporated in the trial balance.
    • When ledger accounts are balanced only this method can be used.
    • This method is generally used by accountants for preparation of the financial statements.


    Total amount method

    • Under this method, the total amount of debit and credit items in each ledger account is incorporated into the trial balance.
    • This method can be used immediately after the completion of posting from the books of the original entry ledger.


    Steps to prepare a trial balance

    • First, we need to decide the method to opt for the preparation of the trial balance which is mentioned above.
    • Then once opted, collect all the balances as per the method adopted and prepare accordingly by posting the debit and credit side of the trial balance.
    • After this process arrange all the accounts in order of their nature (assets, liabilities, equity, income, and expenses ).
    • Then you have to total debit and credit balances separately.
    • After the above steps if there is any difference between the total debit and credit side balances then that is adjusted through the suspense account.


    A suspense account is generated when the above case arises that is trial balance did not agree after transferring the balance of all ledger accounts including cash and bank balance.

    And also errors are not located in  timely, then the trial balance is tallied by transferring the difference between the debit and credit side to an account known as a suspense account.


    Rules of trial balance

    When we prepare a trial balance from the given list of ledger balances, the following rules to be kept in mind that are as follows :

    • The balance of all
    • Assets accounts
    • Expenses accounts
    • Losses
    • Drawings
    • Cash and bank balances

    Are placed in the debit column of the trial balance.

    • The balances of
    • liabilities accounts
    • income accounts
    • profits
    • capital

    Are placed in the credit column of the trial balance.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Rahul_Jose
Rahul_Jose
In: 1. Financial Accounting > Ratios

What is Statutory Liquidity Ratio?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on November 29, 2021 at 8:30 pm

    Statutory Liquidity ratio is the minimum percentage of reserves of liquid assets that the commercial bank should maintain. These liquid assets are in the form of gold, cash, and other securities. These reserves are kept with the bank itself and not with the Reserve Bank of India. The bank holds variRead more

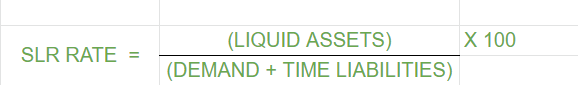
    Statutory Liquidity ratio is the minimum percentage of reserves of liquid assets that the commercial bank should maintain. These liquid assets are in the form of gold, cash, and other securities. These reserves are kept with the bank itself and not with the Reserve Bank of India.

    The bank holds various demand and time deposits of the public, the total of which is called Net Demand and Time Liabilities (NDTL). This includes demand deposits that have to be paid on demand. Various other deposits like time deposits, fixed deposits, demand drafts, etc. are also included.

    Every bank must keep a portion of its NDTL in the form of cash, gold, or other liquid assets. Therefore, the Statutory Liquidity Ratio is the ratio of these liquid assets to the total demand and time liabilities. The authority to determine the ratio lies with the RBI, who can increase it to the extent of 40%.

    FORMULA

    PURPOSE OF SLR

    RBI controls the flow of cash in the economy by means of monetary policy measures through financial instruments like Statutory Liquidity Ratio. At the time of inflation, RBI increases SLR to reduce the flow of cash whereas, at the time of deflation, they reduce SLR to increase the flow of cash. Maintaining SLR also helps ensure the solvency of the commercial banks.

    If the banks do not maintain the necessary level of SLR, they would be liable to pay a penalty to RBI at 3% per annum above the bank rate, on the shortfall amount of that day.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Goodwill

Goodwill is a fictitious asset?

A. True B. False

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on August 11, 2021 at 7:02 am
    This answer was edited.

    The answer is B. False. Before jumping on the solution to know why goodwill is not fictitious, we need to know what are fictitious assets? Fictitious assets are false assets or not true assets. These are not assets but expenses & losses that are not written off from the profit & loss accountRead more

    The answer is B. False. Before jumping on the solution to know why goodwill is not fictitious, we need to know what are fictitious assets?

    Fictitious assets are false assets or not true assets. These are not assets but expenses & losses that are not written off from the profit & loss account but shown in the balance sheet as assets under the head miscellaneous expenditure. For example preliminary expenses, loss on issue of debentures, etc.

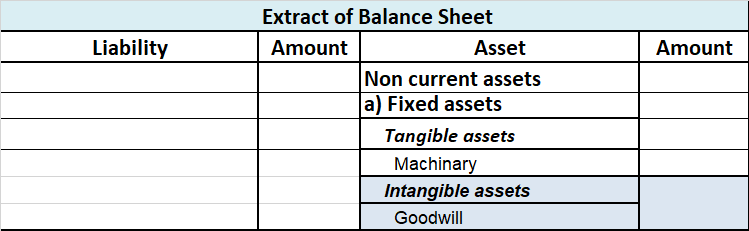
    Goodwill is not a fictitious asset but an intangible asset which means it has no actual physical appearance and cannot be touched and felt like other assets like buildings and machinery. It is nothing but a firm’s reputation which can be sold just like other assets help the business grow and earn revenue. Goodwill is shown in the balance sheet as follows:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ishika Pandey
Ishika PandeyCurious
In: 1. Financial Accounting > Subsidiary Books

What is bills payable and bills receivable book ?

  • 1 Answer
  • 2 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on February 5, 2023 at 12:58 pm

    A bills receivable book is a subsidiary book that shows the details of various bills receivables drawn on customers. It shows the amount, due date, date when the bill was drawn, name of the acceptor, and various other details pertaining to each bill. A bills payable book is a subsidiary book that shRead more

    A bills receivable book is a subsidiary book that shows the details of various bills receivables drawn on customers. It shows the amount, due date, date when the bill was drawn, name of the acceptor, and various other details pertaining to each bill.

    A bills payable book is a subsidiary book that shows the details of various bills that suppliers have drawn on the business. It shows the amount, due date, date when the bill was drawn, name of the drawer and various other details pertaining to each bill.

    The total of both these books is ultimately transferred to the general ledger. From there, it is used in drafting the balance sheet.

    Importance of bills receivable and bills payable books

    Bills receivable books help us know the amount that each customer is liable to pay us on specific dates while bills payable books help us know the amounts that we have to pay our various suppliers on certain dates.

    Together these books help us handle our cash flows in an efficient manner.

    We can evaluate our credit cycle. Bills receivable books help us avoid bad debts while bills payable books help us to avoid defaults.


    Difference between bills receivable and bills payable

    These are the primary differences between bills payable and bills receivable:

    • Bills receivable represent the amounts that the business is to receive from customers while bills payable represent the amounts that the business has to pay to suppliers.
    • Bills receivable are recorded as an asset in the balance sheet while bills payable are recorded as a liability.
    • Bills receivable are drawn by the business on the customers while the bills payable are drawn by the suppliers on the business.
    • Bills receivable are the outcome of credit sales while bills payable are the outcome of credit purchases.
    • Bills receivable result in an inflow of cash while bills payable result in an outflow of cash.
    • The dishonor of a bill receivable is recorded as an increase in the debtors of the business. Default on payment of bills payable may occur either because the business has become bankrupt or the business may record an increase in creditors.

    We can conclude that both bills receivable and bills payable books are subsidiary books. Bills receivable shows the details of every bill that the business has drawn on each credit customer. Bills payable show the details of every bill that each credit supplier has drawn on the business.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.