Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Astha
AsthaLeader
In: 1. Financial Accounting > Contingent Liabilities & Assets

When and where are Contingent Assets disclosed?

Contingent Assets
  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on June 29, 2021 at 9:04 am
    This answer was edited.

    To begin with, let me first give you a small explanation of what Contingent assets are A contingent asset is a potential asset or economic benefit that does not exist currently but may arise in the near future. Such an asset arises from an uncertain and unpredictable event. To make it clear with anRead more

    To begin with, let me first give you a small explanation of what Contingent assets are

    A contingent asset is a potential asset or economic benefit that does not exist currently but may arise in the near future. Such an asset arises from an uncertain and unpredictable event.

    To make it clear with an example: String Co. filed a lawsuit against a competitor company Weave Tech Co. for infringing on company ABC’s patent. Even if it is probable (but not certain) that Strings Co. will win the lawsuit, it is a contingent asset.

    As such, it will not be recorded in Strings Co. general ledger accounts until the lawsuit is settled.

    At most the Strings Co. can do is, prepare a note disclosing the fact that it has filed the lawsuit the outcome of which is uncertain.

    Disclosing Contingent Assets

    • The probability of occurrence is virtually certain or probable: It will be disclosed as an asset in the balance sheet.

    For Example, The court orders for reimbursement to Strings Co. say 1,00,000 for the damages, but it has not yet received the money. Although it is virtually certain that the company will receive the money in the near future, it will be treated as an asset and can be disclosed in the balance sheet on the assets side.

    • The probability of occurrence is probable: It will be disclosed as notes to accounts below the balance sheet.

    For Example, Strings Co. filed a lawsuit against a competitor company Weave Tech for infringing on Strings Co. patent. Even if it is probable (but not certain) that Strings Co. will win the lawsuit, it is a contingent asset.

    As such, it will not be recorded in Strings company’s general ledger until the lawsuit is settled.

    At most the Strings Co. can do is, prepare a note disclosing the fact that it has filed the lawsuit the outcome of which is uncertain. 

    • The probability of occurrence is remote or not probable:  It will not be treated as a contingent asset.

    In this case, the disclosure of it is not permitted.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Miscellaneous

What is the difference between bad debt and write off?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 28, 2021 at 7:05 pm
    This answer was edited.

    The term ‘bad debt’ and ‘write off’ are often used together in a sentence but they have different meanings. First, we will discuss them in brief to understand the differences between them. Bad debts We know, debtors for a business are their assets because the business has the right to receive moneyRead more

    The term ‘bad debt’ and ‘write off’ are often used together in a sentence but they have different meanings. First, we will discuss them in brief to understand the differences between them.

    Bad debts

    We know, debtors for a business are their assets because the business has the right to receive money from the debtors due to the goods supplied to them.

    But if due to circumstances, there appears no probability that the amount due to one or more debtors will be realised to the business, then such debts are categorised as bad debts.

    In short, bad debts refer to the amount of money that will not be received from some debtors of the business due to some circumstances like insolvency of debtor etc.

    Bad debt is deducted from debtors account by the following journal entry:

    Bad debts A/c Dr. Amt
    To Debtors A/c Cr. Amt
    (Being bad debts written off from debtors)

    As bad debts are losses to a business, it is ultimately written off from the profit and loss account.

    Profit and loss A/c Dr. Amt
    To Bad debts A/c Cr. Amt
    (Being bad debts written off to profit and loss account)

    Write off

    In layman terms, write off means to deduct something out from something. In accounting, write off means to deduct or reduce value of assets by crediting it to a liability account which is usually a reserve account or the profit and loss account.

    It also refers to the elimination of an item from the books of accounts particularly losses and expenses.

    Generally, writing off is associated with the following:

    1. Bad debts.
    2. Damaged Inventories.
    3. Loss on issue or redemption of debentures.
    4. Preliminary expenses.
    5. Bad loans and advances.

    Write off can be done in one of the following methods:

    1. Direct write-off: The write off is directly done by crediting asset account or loss account and debiting the reserve or P/L account.
    2. Indirect write-off: Here, an intermediate account is involved between the asset account and liabilities account. A common example is writing off of bad debts where the bad debts account is the intermediate account.

    Hence, the following differences can be observed between bad debts and write off or writing off:
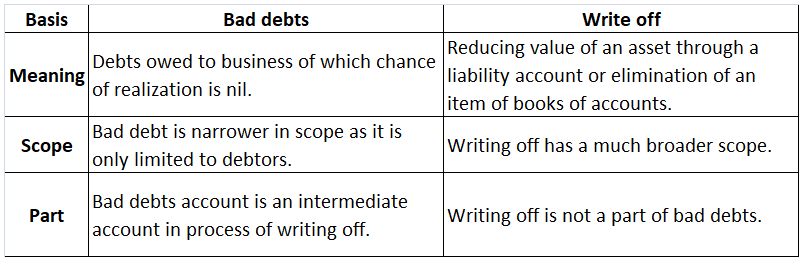
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Depreciation & Amortization

Is depreciation a cash flow?

Cash FlowDepreciation
  • 1 Answer
  • 1 Follower
Answer
  1. Astha Leader Pursuing CA, BCom (Hons.)
    Added an answer on June 2, 2021 at 12:43 pm
    This answer was edited.

    Depreciation refers to that portion of the value of an asset that a company uses in an accounting year to generate revenue. Assets are written off in form of depreciation over time also called the useful life of the asset. It denotes the wear and tear of an asset over time. Suppose, a company namedRead more

    Depreciation refers to that portion of the value of an asset that a company uses in an accounting year to generate revenue. Assets are written off in form of depreciation over time also called the useful life of the asset. It denotes the wear and tear of an asset over time.

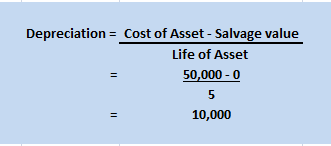
    Suppose, a company named Johnson ltd. purchases machinery for 50,000 that has a useful life of 5 years with nil salvage value. Then the yearly depreciation to be charged can be calculated as:

    Depreciation calculation with formula

    Is Depreciation a Cash Flow?

    Cash flows are inflows and outflows of cash and cash equivalents in an entity. The payments made by the entity denote the outflows whereas the revenues or incomes of the entity denote the inflows. Talking about cash flows, depreciation is a non-cash item of expense which means it neither results in inflow nor outflow of cash resources.

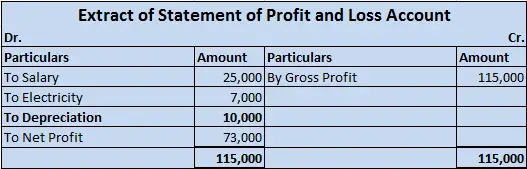
    In the adjacent Profit and Loss statement, a cash payment of 7,000 for electricity implies outflow of cash however, depreciation of 10,000 is merely an imputed cost to write off an asset or we can say, a part of profits set aside each year so that there are sufficient funds available to procure a new asset after the currently available asset is discarded.

    showing depreciation in profit and loss account

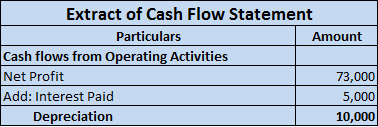
    However, cash flow statements are affected by depreciation. Depreciation is added back to the net profits while calculating cash flows from operating expenses since it is a non-cash item and has been deducted while calculating net profits in the profit and loss statement.

    Depreciation shown in cash flow statement

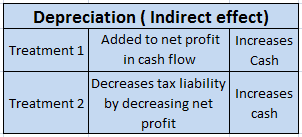
    Depreciation does not directly impact the amount of cash generated or expended by a business but it is tax-deductible and will reduce the cash outflows related to income taxes. Thus, depreciation affects cash flow by reducing the amount of cash a business has to pay for income taxes.

    depreciation effect on cash flow indirectly

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Subsidiary Books

The closing balance of petty cash book is considered as?

1) Liability 2) Asset 3) Expenses 4) Income

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 21, 2022 at 8:15 pm
    This answer was edited.

    Therefore, 2) Asset is the correct option. Explanation   The petty cash book is managed and made by not an accountant but the petty cashier and is done to record small incomes and expenditures that are not recordable in the cash book. Therefore, the desired result we obtain from the deduction oRead more

    Therefore, 2) Asset is the correct option.

    Explanation


    The petty cash book is managed and made by not an accountant but the petty cashier and is done to record small incomes and expenditures that are not recordable in the cash book. Therefore, the desired result we obtain from the deduction of the total expenditure and total cash receipt is the closing balance of the petty cash book.

    Petty cash refers to the in-hand physical cash that a business holds to pay for small and unplanned expenses.

    Asset: The closing balance of the petty cash book is considered an asset because the petty cash book is a type of cash book. The petty cash book also deals in outflow and inflow of the cash, it also maintains and records income and expenditure that are similar to the cash book.


    The petty cash book since being a part of the cash book, which records all the inflow and outflow of cash in a business, which is an asset, thus petty cash book’s closing balance is considered an asset. Also, the balance of the petty cash book is never closed. Their closing balance is carried forward to the next year.


    Liability: The closing balance of the petty cash book is not considered a liability because that closing balance of the petty cash book doesn’t create a liability for the business. In fact, the closing of the petty cash book is placed under the head current asset in the balance sheet as mentioned above, it’s a part of the cash book which records the transactions of cash a/c which is an asset itself.


    Expenses or Income: It is not an expense because the closing balance of the petty cash book is calculated by deducting the total expenditure from the total cash receipt.

    That is an asset and it is considered to be a current asset, neither an income nor an expense. It is used for paying out petty expenses.


    Therefore, the closing balance of the petty cash book is considered an asset.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 5. Audit > Miscellaneous - Audit

Is forensic accounting same as audit?

  • 1 Answer
  • 0 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on January 13, 2023 at 7:12 am

    No, forensic accounting and auditing are not the same thing. Forensic accounting is a much more detailed task that is normally done when fraud or other illegal activity is suspected. The evidence collected by forensic accountants is used in the court of law. Forensic accounting is mostly done when aRead more

    No, forensic accounting and auditing are not the same thing. Forensic accounting is a much more detailed task that is normally done when fraud or other illegal activity is suspected.

    The evidence collected by forensic accountants is used in the court of law. Forensic accounting is mostly done when a suit has already been filed or is likely to be filed.


    How Forensic Accounting Differs from Auditing?

    Auditing means an inspection of financial statements done by experts with a view to obtaining reasonable assurance as to whether or not the financial statements correctly state the financial position and financial performance of the entity during the period under audit.

    Forensic accounting is the use of accounting skills to detect any fraud, embezzlement or other illegal activity that may have occurred within the entity.

    This is how forensic accounting differs from auditing:

    • Forensic accounting is different from auditing in that forensic accounting is done with an intention to identify and uncover frauds while auditing is normally done to provide the users of financial statements reasonable assurance that the statements are correct and true.
    • Auditing usually identifies only those misstatements that are material. Materiality is the one of the main concerns of auditors. However, in forensic auditing every type of misstatement is scrutinized as material. The forensic accountants try to identify fraud in every misstatement.
    • Forensic accounting is usually done only when fraud and other illegal activities are suspected and some suit has been filed or is likely to be filed while auditing of annual financial statements is mandatory for firms meeting certain threshold limits of turnover/gross receipt/revenue.

    Importance of Forensic Accounting

    • Forensic accounting is used to detect frauds, forgery, misappropriation of assets and other illegal activities.
    • The evidence collected during forensic accounting can be used in a court of law. Often, those conducting forensic accounting are also called upon to testify as experts in a court.
    • Forensic accounting identifies loopholes in the internal controls of an entity that has been or may be exploited for conducting frauds and other illegal activities.
    • Forensic accountants suggest different measures that an entity can take to make it’s internal controls more effective and prevent illegal activities in the future.

    Conclusion

    Forensic accounting and auditing are very different from each other. While auditing is done to identify only material misstatement, forensic accounting is done with an objective of detecting possible fraud or other illegal activity. Auditing of financial statements is mandatory for firms exceeding certain threshold limits of turnover/gross receipts/revenue while financial accounting is usually done when a suit for fraud, embezzlement etc has been filed or is likely to be filed.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Accounting Terms & Basics

The following is a statement of revenues and expenses for a specific period of time?

A. Trading Account B. Trial Balance C. Profit and Loss Statements D. Balance Sheet  

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 12, 2021 at 6:05 pm
    This answer was edited.

    The correct answer is Option C. The Profit and loss statement is also referred to as the statement of revenues and expenses. It is because the Profit and Loss statement reports all types of revenue that have been earned and all types of expenses that have been incurred during a particular period ofRead more

    The correct answer is Option C.

    The Profit and loss statement is also referred to as the statement of revenues and expenses. It is because the Profit and Loss statement reports all types of revenue that have been earned and all types of expenses that have been incurred during a particular period of time.

    Option A Trading Account reports only the operating revenues and operating expenses.

    Option B Trial Balance shows the balances of all the ledgers of a business and is prepared to check the arithmetical accuracy of the books of accounts.

    Option D Balance sheet reports the balances of assets and liabilities of a business as at a particular date.

    People often confuse the trading and the profit and loss statement to be the same. But they are different.

    Trading Account is prepared with aim of arriving at operating profit or gross profit whereas the profit and loss statement is prepared to arrive at the net profit of a business and reports every revenue and expense whether operating or non operating in nature.

    Operating revenue and operating expense are earned or incurred respectively are related to the chief business activities of a business.

    Features of profit and loss statement:

    1. It is prepared to measure the net profit of a business hence its profitability.
    2. It is usually prepared for a period of one year but many companies do prepare quarterly statements to better judge their performance.
    3. It helps the management in decision making and the other stakeholders like shareholders, creditors to make informed decisions.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Miscellaneous

What is outstanding income?

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on August 17, 2021 at 3:32 pm

    Outstanding Income is the income that is due and is being earned but not yet received. The person/ firm has the legal rights to receive that part of the income which it has earned. Outstanding Income is an Asset Account for the business/ the person. According to the modern approach, for Asset AccounRead more

    Outstanding Income is the income that is due and is being earned but not yet received. The person/ firm has the legal rights to receive that part of the income which it has earned.

    Outstanding Income is an Asset Account for the business/ the person.

    According to the modern approach, for Asset Account:

    • When there is an increase in the Asset, it is Debited.
    • When there is a decrease in Asset, it is Credited.

    So the journal entry  will be-


    For Example, Mr. Rashid works as a laborer in a factory and he earns wages @Rs 500/day.

    So by the end of the week, he receives a payment of Rs 3000 of Rs 3500 i.e. he receives payment of 6 days instead of 7 days. So here Rs 500 would be an outstanding income of Mr. Rashid as he has earned that income but has not received it yet.

    Journal Entry –


    Another example, Yes Bank gave a loan of Rs 10,00,000 to company Ford @ 10% as interest payable monthly. The interest for one month i.e. Rs 1,00,000 has not been received by Yes Bank which is being due. So it will be outstanding income for Yes Bank since it is due but not yet received.

    Journal entry-


    Accounting Treatment for Outstanding Income-

    • Treatment in Income Statement

    The Outstanding Income is shown on the credit side of the income statement as the income is earned for the current year but not yet received.

    • Treatment in Balance Sheet

    Outstanding Income is an Asset for the business and hence shown on the Assets side of the balance sheet.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.