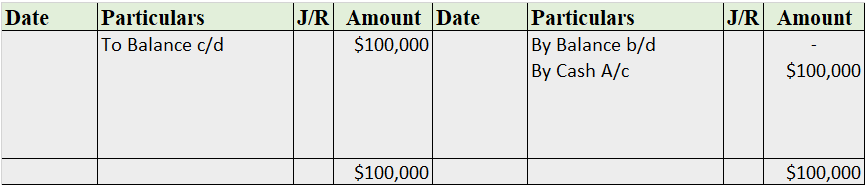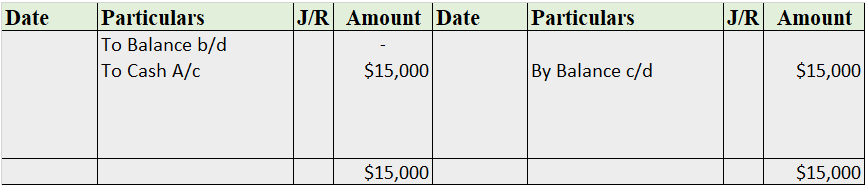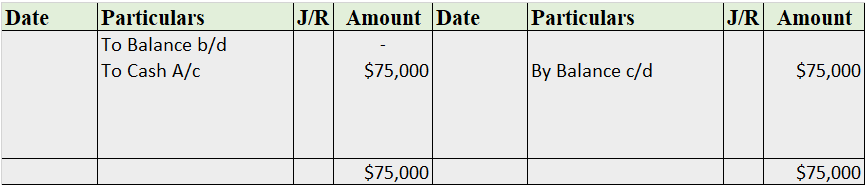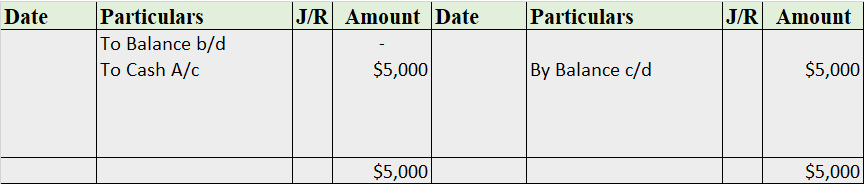Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Bonnie
BonnieCurious
In: 1. Financial Accounting > Partnerships

How to make a partnership deed?

  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on August 3, 2021 at 7:27 pm
    This answer was edited.

    To proceed with how to make a partnership deed, let me explain to you in short what is partnership deed? A partnership deed is the written agreement between the partners who have agreed to share profits of a business carried on by them. This basically contains terms and conditions to be followed betRead more

    To proceed with how to make a partnership deed, let me explain to you in short what is partnership deed?

    A partnership deed is the written agreement between the partners who have agreed to share profits of a business carried on by them. This basically contains terms and conditions to be followed between the partners.

    Few contents of the partnership deed are as follows:

    • Name, address, and type of business of the partnership firm.
    • Name & address of all the partners
    • Profit-sharing ratio.
    • Rights, duties, and liabilities of all partners.
    • Date of commencement of the partnership
    • Method of settlement of dispute among the partners.
    • Treatment of loss in case of insolvency of one or more partners.


    Generally, a partnership deed contains all those matters which can affect the relationship between the partners. However, if there is no such agreement the partnership should follow the provisions mentioned under The Partnership Act, 1932.

    Now coming to the main question how to make a partnership deed? See the process is not so complicated. The partnership deed may be oral or written, but as the oral agreement has no value for obtaining tax benefits, a partnership firm always prefers a written agreement.

    To prepare the same the partnership deed must be prepared on a stamp paper and signed by all the partners as per Indian Stamp Act and copies of the same should be with all the partners and also must be filed by the registrar of the firm.

    A deed may vary depending on the nature of the partnership they are engaged in. Generally, partnerships are of three types

    • General partnership
    • Limited partnership
    • Limited liability partnership

    the process of making deed is same for all but, the content of deed may vary depending on the liability of partners in the partnership.

    Further to know more about the registration process of partnership firm you can refer the following link https://www.mca.gov.in/Ministry/actsbills/pdf/Partnership_Act_1932.pdf

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Miscellaneous

Can accounts payable have a debit balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Kajal
    Added an answer on September 27, 2023 at 12:23 am
    This answer was edited.

    Yes, Accounts Payable can have a Debit balance. Accounts payable is a liability and thus, has a credit balance but can have a debit balance in case the creditor is overpaid or when there is purchase return (for already-paid goods)   ACCOUNTS PAYABLE Accounts payable refers to all short-term liaRead more

    Yes, Accounts Payable can have a Debit balance. Accounts payable is a liability and thus, has a credit balance but can have a debit balance in case the creditor is overpaid or when there is purchase return (for already-paid goods)


    ACCOUNTS PAYABLE

    Accounts payable refers to all short-term liabilities of the business that are to be paid. These are usually paid within a duration of  90 days. It includes both Trade payable (goods and services purchased on credit) as well as expenses payable (used but payment not made yet) like rent payable, electricity bill, etc.

    Businesses cannot make every payment on the spot. There can be cases when the business is facing a shortage of funds, can have funds but doesn’t have enough cash (or liquid funds) to make payment or simply doesn’t want to make payment on the spot to reduce its capital requirement.

    So, like us businessmen also purchase goods on credit or use services for which payment is to be made soon. All these are liabilities for the business.

    However, they must be related to the business to be considered as accounts payable.


    DEBIT BALANCE OF ACCOUNTS PAYABLE 

    Debit balance of accounts payable means money owed by others. There is Debit balance when

    OVERPAYMENT is made to the creditors or the supplier. It happens when the wrong amount is paid or payment is made twice for the same transaction.

    Suppose you need to pay $10,000 as rent within 30 days. After 25 days you mistakenly made a payment of $12,000.

    In this case,

    • Firstly, you will record the transaction by crediting Accounts payable (as liability increased) by $10,000
    • When payment is made after 25 days, Accounts Payable is debited by $12,000 (as liability decreased)
    • So, there will be a debit balance of $2,000 (which means the creditor owes you) till the creditor returns the excess amount.


    PURCHASE RETURN of already paid goods also result in debit balance of Accounts Payable.

    Suppose you bought goods worth $50,000 from Mr A on credit and paid for the same. Later, you returned all the goods because they were defective. Now, there will be Debit balance of Accounts Payable till there is a full refund of $50,000 by Mr A.


    How is Accounts Payable Treated Normally?

    Accounts Payable are the current liabilities of the firm and are shown under the head Current Liabilities in the Balance Sheet. Its liability, thus has a credit balance which represents the amount owed by the firm to others. It is credited when increases and debited when decreases.

    For example – Suppose you purchased goods worth $30,000 and agreed to pay after 30 days. So, Accounts payable will be credited by $30,000 and purchases will be debited by $30,000.

    Purchases A/c – $30,000 (debit)

    To Accounts Payable A/c – $30,000

    After 30 days payment is made in cash, which means the liability decreased. So, Accounts Payable A/c will be debited.

    Accounts Payable A/c – $30,00

    To Cash – $30,000

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What are non debt capital receipts?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 6, 2022 at 6:41 pm
    This answer was edited.

    Non-debt capital receipts As we're aware, there are two main sources of the government’s income — revenue receipts and capital receipts. Revenue receipts are all those receipts that neither create any liability nor cause any reduction in assets for the government, whereas, capital receipts are thoseRead more

    Non-debt capital receipts

    As we’re aware, there are two main sources of the government’s income — revenue receipts and capital receipts. Revenue receipts are all those receipts that neither create any liability nor cause any reduction in assets for the government, whereas, capital receipts are those money receipts of the government that either create a liability for a government or cause a reduction in assets.

    Revenue receipts comprise both tax and non-tax revenues while capital receipts consist of capital receipts and non-debt capital receipts. Non-debt capital receipt is a part of capital receipt.

    Definition

    Non-debt capital receipts, also known as NDCR, are the taxes and duties levied by the government forming the biggest source of its income. Those receipts of the government lead to a decrease in assets, and not an increase in liabilities. It accounts for just 3% of the central government’s total receipts.

    The union government usually lists non-debt capital receipts in two categories:

    • Recovery of loans – Recovery of loans means the amount recovered when a loan defaults.
    • Other receipts – Other receipts basically mean disinvestment proceeds from the sale of the government’s share in public-sector companies.
    • Money accrued to the union government from the listing of central government companies and the issue of bonus shares.


    For Example – Disinvestment and recovery of loans are non-debt creating capital receipts.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Miscellaneous

Can you give types of reserves and surplus?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on November 24, 2021 at 7:16 pm

    ‘Reserve and surplus’ is a heading under ‘Equities and Liabilities’ in which various reserves and surplus of profit of an enterprise appear. Reserve are the amount set aside to meet with uncertainties of the future. They have credit balance as they are internal liabilities of an enterprise. While ‘sRead more

    ‘Reserve and surplus’ is a heading under ‘Equities and Liabilities’ in which various reserves and surplus of profit of an enterprise appear. Reserve are the amount set aside to meet with uncertainties of the future. They have credit balance as they are internal liabilities of an enterprise. While ‘surplus’ generally means the surplus amount in the profit and loss A/c or the operating surplus in case of a non-profit organisation, reserves are of many types:

    1. Revenue reserve
    2. Specific reserves
    • Reserves created from shareholder’s contribution
    1. Capital reserve
    2. Secret reserves

    Let’s discuss each of the above:

    1. Revenue reserves:

    Revenue reserve has two different definitions.

    First – Revenue reserves are the reserves that are created out of the profit made by an enterprise in the ordinary course of business. As per this definition, the examples of revenue reserves are:

    • General reserve: There is no restriction on the purpose for which this reserve can be used. It is a free reserve. Generally, this reserve is used to pay dividends.
    • Debenture Redemption Reserve: This reserve is mandatory to be created by law. The purpose is to ensure the timely redemption of debentures.
    • Dividend Equalisation Reserve: This reserve is created to maintain a steady rate of dividend every year even if the enterprise reports loss in any financial year.
    • Capital Redemption Reserve: This reserve can be solely used to issue bonus shares to fill the void created in total capital by redemption of preference shares.
    • Workmen Compensation Reserve: This reserve is created to pay for uncertain compensation that an enterprise may be liable to pay to its employees.
    • Investment Fluctuation Reserve: This reserve is created out of the profit of


       Second: Revenue reserve is a reserve from which can be used to any use. It can be the payment of dividends, creation of other reserves or reinvestment in the business. It is another name for general reserve.

    1. Specific reserves

    These are the reserves that are restricted to specific purposes only. These reserves are not free reserves i.e. dividends cannot be declared out of these reserves. However, if in case such reserve is not a statutory reserve, an enterprise can very well use such reserves for other purposes too. Specific reserves can be further classified into two types:

    • Statutory specific reserves: These are reserves that are mandatory to be created to comply with legal provisions applicable to an enterprise. Use of such reserves is restricted to some specific purposes.

    If such reserves are not created whenever applicable or if the amount in such reserves is used for a purpose other than the purpose for which it is created, the enterprise can invite face legal consequences. The examples of statutory reserves are as follows:

    • Capital Redemption Reserve
    • Debenture Redemption Reserve
    • Securities Premium Reserve
    • Non – Statutory specific reserves: It is not mandatory to create such reserves. They are created to meet with specific uncertainties of the future.
    • Workmen Compensation Reserve
    • Investment Fluctuation Reserve

    Important Note: Statutory reserve in the context of insurance companies means the minimum amount of cash and marketable securities to be set aside to comply with legal requirements.

    • Reserves created from shareholder’s contribution

    This is a reserve that is created out of a shareholder’s contribution. Securities premium reserve is the only such reserve that is created out of such shareholder’s contribution.


    Securities Premium Reserve: It is a reserve that is created when securities of a company such as shares or debentures are issued at a premium. The share or debenture premium money is created for this reserve. The purposes of which this reserve may be used as per section 52 of the Companies Act, 2013 are as follows:

    • For the issue of fully paid bonus shares.
    • For meeting preliminary expenses incurred by the company
    • For meeting the expense, commission or discount allowed on the issue of securities of the company.
    • In providing premium payable on the redemption of preference shares.
    • For the purchase of its own shares or other securities under section 68.
    1. Capital Reserve:

    Capital reserve is a reserve that is created out of the profit made by an enterprise from its non-operating activities like

    • selling of capital assets(fixed assets) at a profit
    • buying a business at profit (where net assets acquired is more than the purchase consideration)

    This reserve is used to finance long term projects of a company like buying or construction of fixed assets, writing off capital losses( selling of fixed assets at loss).

    1. Secret Reserve:

    A secret reserve is a reserve that exists but its existence is not shown in the balance sheet of an enterprise. An enterprise creates such reserves to hide from its competitor that it is in a better financial position than it appears in its balance sheet. Although the creation of secret reserves is prohibited by law, there are provisions for banking companies to create such reserves.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 1. Financial Accounting > Ledger & Trial Balance

How do you record journal entries in ledger?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 24, 2022 at 8:40 pm
    This answer was edited.

    Journal entries in the ledger What is a Journal Entry? Journal entry is a form of bookkeeping. All the economic or non-economic transactions in the business are recorded in the journal entries showing a company's debit or credit balances. It is a double-entry accounting method and requires at leastRead more

    Journal entries in the ledger

    What is a Journal Entry?

    Journal entry is a form of bookkeeping. All the economic or non-economic transactions in the business are recorded in the journal entries showing a company’s debit or credit balances. It is a double-entry accounting method and requires at least two accounts or more in a transaction.

    The journal entry helps to identify the transactions. We use journals to get a running list of business transactions. Each journal entry provides this specific information about a transaction:

    • Date of the transaction.
    • Accounts involved in it.
    • Payer, payee, receiver, etc.
    • Account name.
    • Debit and credit of money.


    General Ledger 

    After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. A ledger account contains information about a specific account. It contains the opening balance as well as the closing balances of an account. It summarizes the business transactions.

    Transferring the entries from journals to respective ledger accounts is called ledger posting or posting to the ledger accounts. Balancing of ledgers is carried out to find differences at the year’s end, it means finding the difference between the debit and credit amounts of a particular account.


    For instance,

    Suppose goods were bought for cash. While passing the journal entry, we’ll be debiting the purchases a/c and crediting the cash a/c by stating it as, ‘To Cash A/c’.

    Now, this entry will be affecting both the purchases account and the cash account. In the cash account, we’ll be debiting purchases. Whereas in the purchases account, we’ll be crediting the cash. That’s how it works in the double-entry bookkeeping system of accounting.


    Example

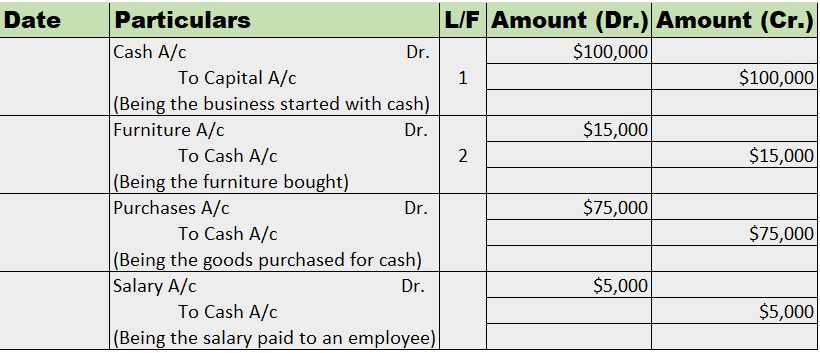
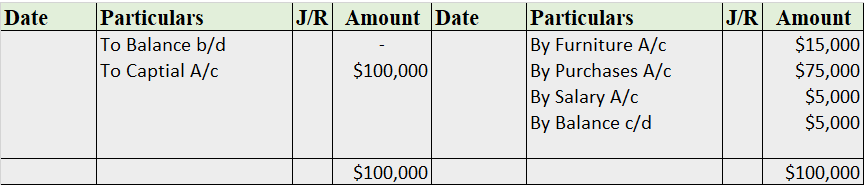
    Mr. Tony Stark started the business with cash of $100,000. He bought furniture for business for $15,000. He further purchased goods for $75,000. He hired an employee and paid him a salary of $5,000.

    Now, we’ll be journalizing the transactions and posting them into the ledger accounts.

    Journal Entries

    Recording into Ledger Account

    Cash A/c

    Capital A/c

    Furniture A/c

    Purchases A/c

    Salary A/c

    Note: The balance b/d is not applicable as this is the business’ commencement year.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Journal Entries

Can you tell me journal entry for provision for depreciation?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on August 7, 2021 at 4:23 pm
    This answer was edited.

    First, let us understand the meaning of a provision of depreciation. It is nothing but the total collection of all the depreciation over the years. This account is not like a normal account but a contra asset account. It is also called accumulated depreciation. Annual depreciation charged is an expeRead more

    First, let us understand the meaning of a provision of depreciation. It is nothing but the total collection of all the depreciation over the years. This account is not like a normal account but a contra asset account. It is also called accumulated depreciation.

    Annual depreciation charged is an expense for the business and hence has a debit balance. Whereas provision for depreciation as a contra asset account has a credit balance.

    The journal entry for provision for depreciation is

    Depreciation A/c                                                      ……….Dr XXX
               To Provision for depreciation XXX

    Explaining the credit nature of this account. As we know that the depreciation is an expense for the business hence as per modern rules “Debit all the expenses and losses and credit all incomes and gains” therefore it is debited whereas the provision of depreciation is contra account it has a credit balance as it reduces the value of assets. So according to modern rule, we know a decrease in assets has a credit balance, hence shown in a negative balance on the balance sheet under long-term assets.

    With the preparation of this account, we do not credit depreciation in the asset account but transfer every year to the accumulated depreciation account, and when assets are disposed of or sold we credit the ‘total’ of the provision on depreciation to the credit of the asset account just to calculate the actual profit or loss on a sale of the asset.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Partnerships

Can someone show profit and loss appropriation account example?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 21, 2021 at 7:37 pm
    This answer was edited.

    The profit and loss appropriation account is an account created in addition to the Trading & Profit and loss account in the case of partnership firms. It is a nominal account. The net profit or loss from the Profit and loss account is transferred to the Capital A/c when we do the accounting of sRead more

    The profit and loss appropriation account is an account created in addition to the Trading & Profit and loss account in the case of partnership firms. It is a nominal account.

    The net profit or loss from the Profit and loss account is transferred to the Capital A/c when we do the accounting of sole proprietors.

    But, while doing the accounting of partnership, there is a need to appropriate this profit or loss as there are two or more partners’ capital accounts. So, for this purpose, the Profit and loss appropriation account is created.

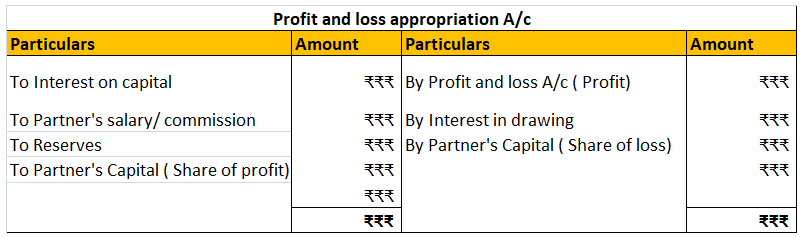
    The net profit or loss is appropriated among the partner’s capital after adjustment the items like partner’s salary, commission, interest on capital, interest on drawing etc. It consists of items related to the partner’s claim.

    The format of the profit and loss appropriation account is as below:

    Let solve a problem to sharpen our concept:

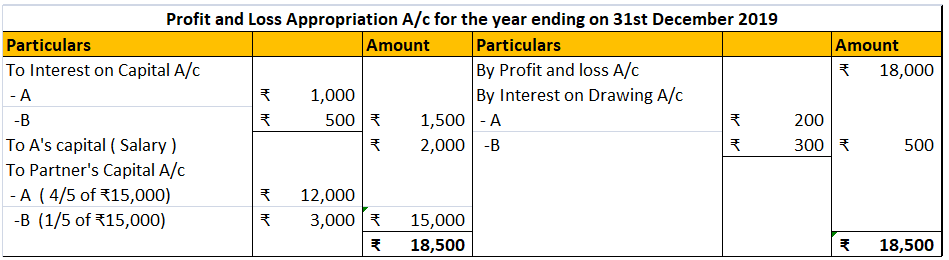
    A and B are partners in firm sharing profits and losses in the ratio of 4:1. On 1st January 2019, their capitals were ₹ 20,000 and ₹ 10,000 respectively. The partnership deed specifies the following:

    1. Interest on capital is to be allowed at 5% per annum.
    2. Interest on drawings charged to A and B are ₹ 200 and ₹ 300 respectively.
    3. The net profit of the firm before considering interest on capital and interest on drawings amounted to ₹ 18,000.
    4. A is to be paid an annual salary of ₹2000

    Prepare Profit and loss appropriation account for the year ending 31st December 2019.

    Solution:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.