Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Anushka Lalwani
Anushka Lalwani
In: 6. Software & ERPs > Tally

Can you share journal entries for tally practice?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on September 8, 2022 at 6:28 am
    This answer was edited.

    Introduction In Tally, journal entries are made in the vouchers. For each type of journal entry, there is a specific voucher. It is the vouchers where the transactions are recorded along with all the relevant details. Hence, when we speak of journal entries in tally, it is the vouchers which we haveRead more

    Introduction

    In Tally, journal entries are made in the vouchers. For each type of journal entry, there is a specific voucher. It is the vouchers where the transactions are recorded along with all the relevant details. Hence, when we speak of journal entries in tally, it is the vouchers which we have to master.

    In Tally, vouchers are of four types:

    1. Accounting vouchers
    2. Inventory vouchers
    3. Order voucher
    4. Payroll voucher

    The vouchers under the above voucher types are as shown below:

    To open the voucher creation menu follow these steps:

    In Tally ERP 9: Gateway of Tally→ Accounting Vouchers→ Voucher creation menu will open

    In Tally Prime: Gateway of Tally→ Vouchers→ Voucher creation menu will open

    Out of the above vouchers, the vouchers which I would suggest you practice are as follows (along with their short-cut keys):

    1. Contra Voucher – F4
    2. Payment Voucher – F5
    3. Receipt Voucher – F6
    4. Journal Voucher – F7
    5. Sales Voucher – F8
    6. Purchase Voucher – F9
    7. Credit note – Alt + F6
    8. Debit note – Alt + F5


    All of the above are accounting vouchers. You can simply press the short-cut keys to open the respective voucher while in the voucher creation menu

    If you are new to tally, I would suggest you practice only the accounting vouchers.

    Here, I have discussed only the accounting vouchers:

    Payment Voucher – F5

    A payment voucher is used to record payments of cash or by the bank. Payment can be to creditors or for expenses.

    There are two modes to this voucher which you can change by clicking the ‘Change Mode’ option on the right-hand side menu or simply pressing Ctrl + H. This menu will open.

    Select the ‘Double Entry’ mode for sake of simplicity. In this mode, the entry will be just like the conventional journal entry as in the double entry system of accounting.

    You have to just select the account you want debit which can be an expense, creditor etc. and you can credit only the cash or bank accounts as it is a payment voucher. Below there is a narration field which you can fill too. After entering all the necessary details you have to accept the voucher.

    Here, is a filled payment voucher in which I have recorded an expense payment entry.


     The journal entries which you can practice on payment vouchers are as follows:

    • Payment of expenses like rent, electricity, wages, salaries, carriage, interest etc
    • Payment to trade creditors.
    • Purchase of Assets


    Receipt Voucher – F6

    A receipt voucher is used for the recorded receipt of cash in the business. Just like a payment voucher, I recommend you to use it in Double Entry mode. In Tally prime, it looks this:


    The receipt voucher given above is already filled. I have passed a ‘collection from the debtor’ entry here. 

    The journal entries you can practice in the receipt voucher are as follows:

    • Receipt of cash from trade debtors.
    • Receipt of interest from the bank.
    • Commission received
    • Sale of Assets.

    Purchase Voucher – F7

    A purchase voucher is a voucher for exclusively recording purchase of goods entries. Purchase whether cash or credit should be recorded in the purchase voucher only as it allows recording of additional details related to purchase as well as tracking with purchase order and receipt note.

    The purchase voucher looks like this:

    Here, the purchase voucher is opened in ‘Item invoice’ mode. Item invoice is easier to understand hence I advise you to this mode to use the purchase voucher. You can change the mode by pressing Ctrl + H.

    If you wish to record transactions like journal entries then you can choose the ‘As Voucher’ mode.

    The details which you have to fill in are as follows:

    • Reference number or Bill number
    • Party A/c Name or the name of the creditor. (If the creditor is not created, press Alt + C to create)
    • Name of item purchased ( Press Alt + C to create the stock item if not created)
    • Enter the quantity and rate of the item and the total amount will be auto-populated.
    • The accounting details menu will open asking for the account to be debited for the purchase. Select the purchase account you want to debit or create a purchase account by pressing Alt + C if not created.

    • Enter a narration if you want and accept the voucher.

    Below is a complete purchase voucher where a credit sale transaction is passed:

    Sales Voucher – F8

    A sales voucher is a voucher for exclusively recording sales of goods entries. Sales, whether cash or credit, should be recorded in the sales voucher only as it allows recording of additional details related to sales as well as tracking with Sales orders and Delivery notes.

    Here also, I recommend you to use the sales voucher in Invoice mode

    Filling up of details in sales voucher is same as in purchase voucher. The difference here is that in the ‘Accounting details’ section you have selected a sales account to be credited.

    Here is a completed sales voucher where I have recorded a credit sale transaction:

    Contra Voucher – F4

    A Contra voucher is used to record contra transactions. Contra transactions are those transactions which take place between:

    • A Bank account and cash account
    • Two different bank accounts 

    The journal entries which can be practised on contra voucher are as follows:

    1. Withdrawal of cash from the bank.
    2. Deposit from cash into the bank.
    3. Transfer of amount from one bank to another.

    Given below is a completed Contra voucher in which ‘cash deposited into bank’ transaction is recorded:

    Journal Voucher – F7

    There are many transactions which cannot be passed in any of the vouchers discussed above. The examples of such transactions or journal entries are as follows:

    1. Depreciation of assets
    2. Entries related to the provision
    3. Prepaid Expenses
    4. Outstanding expenses
    5. Rectification of error entries
    6. Accrued income entries
    7. Any other entry which cannot be passed in any other voucher.

    It is an important voucher in Tally as many crucial entries are recorded in it.
    The journal voucher looks like this:

    It looks like a journal book and it does not have any different mode like voucher discussed above:

    The journal entries to practice on journal vouchers are many. You can refer to the examples of transactions I have mentioned above.


    Debit Note Voucher – Alt + F5

    A debit note voucher is to record purchase return transactions in Tally. Hence, the only transaction you can record here is of purchase return. The debit note voucher looks like this:


    Credit Note Voucher– Alt + F5

    In credit note vouchers, the sale return transactions are recorded. The credit note voucher looks like this:

    That’s all.  These are vouchers I would recommend one to practice on Tally.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

What is a non-current asset?

  • 1 Answer
  • 0 Followers
Answer
  1. Akash Kumar AK
    Added an answer on November 26, 2022 at 8:06 am
    This answer was edited.

    Generally, Assets are classified into two types. Non-Current Assets Current Assets   Non-Current Asset Noncurrent assets are also known as Fixed assets. These assets are an organization's long-term investments that are not easily converted to cash or are not expected to become cash within an acRead more

    Generally, Assets are classified into two types.

    1. Non-Current Assets
    2. Current Assets


    Non-Current Asset

    Noncurrent assets are also known as Fixed assets. These assets are an organization’s long-term investments that are not easily converted to cash or are not expected to become cash within an accounting year.

    In general terms, In accounting, fixed assets are assets that cannot be converted into cash immediately. They are primarily tangible assets used in production having a useful life of more than one accounting period. Unlike current assets or liquid assets, fixed assets are for the purpose of deriving long-term benefits.

    Unlike other assets, fixed assets are written off differently as they provide long-term income. They are also called “long-lived assets” or “Property Plant & Equipment”.


    Examples of Fixed Assets

    • Land
    • Land improvement (e.g. irrigation)
    • Building
    • Building (work in progress)
    • Machinery
    • Vehicles
    • Furniture
    • Computer hardware
    • Computer software
    • Office equipment
    • Leasehold improvements (e.g. air conditioning)
    • Intangible assets like trademarks, patents, goodwill, etc. (non-current assets)


    Valuation of Fixed asset

    fixed assets are recorded at their net book value, which is the difference between the “historical cost of the asset” and “accumulated depreciation”.

    “Net book value = Historical cost of the asset – Accumulated depreciation”


    Example:

    Hasley Co. purchases Furniture for their company at a price of 1,00,000. The Furniture has a constant depreciation of 10,000 per year. So, after 5 years, the net book value of the computer will be recorded as

    1,00,000 – (5 x 10,000) = 50,000.

    Therefore, the furniture value should be shown as 50,000 on the balance sheet.


    Presentation in the Balance Sheet

    Both current assets and non-current assets are shown on the asset side(Right side) of the balance sheet.
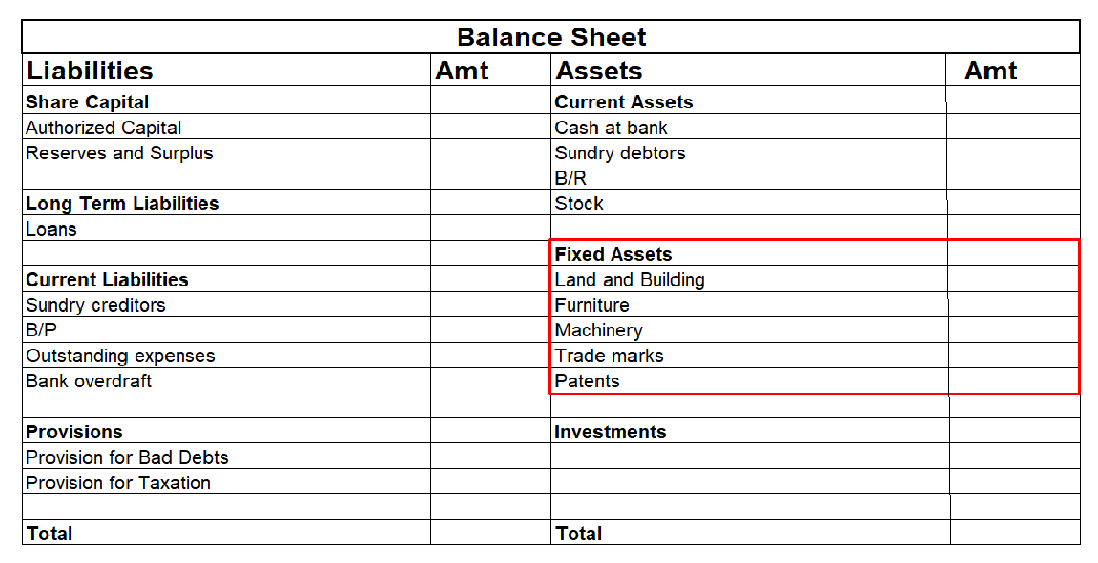
     

    Difference between Current Asset and Non-Current Asset

    Current assets are the resources held for a short period of time and are mainly used for trading purposes whereas Fixed assets are assets that last for a long time and are acquired for continuous use by an entity.

    The purpose to spend on fixed assets is to generate income over the long term and the purpose of the current assets is to spend on fixed assets to generate income over the long term.

    At the time of the sale of fixed assets, there is a capital gain or capital loss but at the time of the sale of current assets, there is an operating gain or operating loss.

    The main difference between the fixed asset and current asset is, although both are shown in the balance sheet fixed assets are depreciated every year and it is valued by (the cost of the asset – depreciation) and current asset is valued as per their current market value or cost value, whichever is lower.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Accounting Terms & Basics

What is Gross profit versus net profit?

  • 1 Answer
  • 1 Follower
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses. When the result of this computation is negative it is referred to as gross loss Formula : ToRead more

    Definition

    Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses.

    When the result of this computation is negative it is referred to as gross loss

    Formula :

    Total Revenues – Cost Of Goods Sold

    Net profit is defined as the excess of revenues over expenses during a particular period.

    When the result of this computation is negative it is called a net loss.

    Net profit may be shown before or after tax.

    Formula :

    Total Revenues – Expenses
    Or
    Total Revenues – Total Cost ( Implicit And Explicit Cost )

    The basic difference between gross profit and net profit is that gross profit estimates the profitability of a company whereas net profit is to show the performance of the company.

    Key points of Gross Profit

    Some of the key points of as for gross profits follows :

    • Stage of calculation: Gross Profit is calculated in the first stage of the Final Account.

    • Purpose of calculation: It is calculated to know the total profit earned during the particular accounting

    • Type of balance: Gross Profit shows the credit balance of the Trading Account.

    • Dimension: It is a narrow concept as it is a part of Net Profit.

    • Treatment: It is not treated directly in the balance sheet. It is transferred to the Profit And Loss Account.

    Key points of Net Profit

    Some of the key points of as for gross profits follows :

    • Stage of calculation: Net Profit is calculated in the second stage of the Final Account.

    • Purpose of calculation: It is calculated to know the net profit earned during the particular accounting

    • Type of balance: Net Profit shows the credit balance of the Profit And Loss Account.

    • Dimension: It is a wider concept as it includes Gross Profit.

    • Treatment: It is treated directly in the balance sheet by adding or subtracting from the capital.

    Examples

    Now let me explain to you by taking an example which is as follows :

    In a business organization there were the following data given as purchases made Rs 73000, inventory, in the beginning, was Rs 10000, direct expenses made were Rs 7000, closing inventory which was Rs 5000, revenue from operation during the period was Rs 100000.
    Then,
    COST OF GOODS SOLD = Purchases + Opening Inventory + Direct Expenses – Closing Inventory.
    = Rs ( 73000 + 10000+ 7000- 5000)
    = Rs 85000

    GROSS PROFIT = REVENUE – COST OF GOODS SOLD
    = Rs ( 100000 – 85000 )
    = Rs 15000

    Now from the above question keeping the gross profit same if the indirect expenses of the organization are Rs 2000 and the other income is Rs 1000.
    Then,

    NET PROFIT = GROSS PROFIT – INDIRECT EXPENSES + OTHER INCOMES
    = Rs ( 15000 – 2000 + 1000)
    = Rs 14000

    Conclusion

    So here I conclude that gross profit is the difference between revenues from sales and/or services rendered and its direct cost.

    Whereas net profit is after the deduction of total expenses from the total revenues of the enterprise.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Goodwill

Why don’t we record self-generated goodwill in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. Mehak
    Added an answer on January 9, 2025 at 4:39 pm
    This answer was edited.

    To understand why we do not record self-generated goodwill in accounting, let us first understand what goodwill is and its accounting treatment. What is Goodwill? Goodwill is an intangible asset of a business.  It represents the reputation and brand value of a business built over time. It is a valueRead more

    To understand why we do not record self-generated goodwill in accounting, let us first understand what goodwill is and its accounting treatment.

    What is Goodwill?

    Goodwill is an intangible asset of a business.  It represents the reputation and brand value of a business built over time. It is a value over and above the tangible assets of the business.

    Goodwill often arises when a business purchases another business and pays a premium, which means a price higher than the fair value of the business.

    Characteristics of Goodwill

    Goodwill has the following characteristics:

    1. It is an Intangible asset, meaning it has no physical existence and cannot be seen or touched.
    2. It is generally recognized during transactions in mergers and acquisitions.
    3. It is the value attributed to the brand value and reputation of the business.
    4. It adds value to a business beyond its tangible assets.

    Example of Goodwill

    Let us take an example to understand the concept of goodwill better.

    Suppose there is a company ABC Ltd. It is planning to acquire XYZ Ltd. The fair value of the assets of XYZ is calculated to be 600,000. However, ABC has agreed to pay a sum of 650,000 to acquire the company. This difference of 50,000 is goodwill.

    Impact on Financial Statements

    Goodwill is shown under the assets side of the Balance Sheet.

    What is self-generated goodwill?

    Self-generated goodwill in simple words means the positive reputation or trust that a business earns over time through their own hard work and decisions. It’s not something bought or inherited but something built from scratch internally, like a brand’s reputation, loyal customers, strong relationships, or unique ideas.

    For example, a small business that goes the extra mile to offer great customer service or always delivers high-quality products over the years will naturally build goodwill.

    It is also known as internally generated goodwill.

    Why do we not record sef-generated goodwill?

    Self-generated goodwill is not recorded in the financial statements because of the following reasons:

    1. Measurement may not be reliable: The measurement of self-generated goodwill is majorly based on the judgment of the managers. It is based on the value creation because of a good reputation or consumer base of the business, which might not be measured accurately.
    2. Conservatism principle: As per the conservatism principle, a business shall not overstate its assets or liabilities. However, self-generated goodwill might be overstated.
    3. Lack of market transaction: There is a lack of a market transaction that ensures verification of the value of goodwill as in the case of purchased goodwill.
    4. Manipulation: There are higher chances of manipulation of financial statements through self-generated goodwill.

    Conclusion

    On a concluding note, self-generated goodwill is something that adds real value to a business, but it’s not something that can easily be measured or captured in financial statements. Accounting is all about providing clear, reliable information, and including goodwill would make things murky and open to manipulation. Even though it doesn’t show up on the books, you can still see its effects in a company’s reputation and success. Maybe in the future, businesses will find a way to highlight it better, but for now, leaving it out helps keep financial reports honest and straightforward.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

Is Land a Current Asset?

Current Assets
  • 2 Answers
  • 0 Followers
Answer
  1. Bonnie Curious MBA (Finance)
    Added an answer on June 27, 2021 at 5:34 am
    This answer was edited.

    Similarly, someone asked Are loose tools current assets

    Similarly, someone asked Are loose tools current assets

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Accounting Terms & Basics

Accounting information should be comparable do you agree with this statement give two reasons?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on July 11, 2021 at 12:51 pm
    This answer was edited.

    Yes, I agree with your statement that accounting information should be comparable. Comparability is one of the qualitative characteristics of accounting information. It means that users should be able to compare a company's financial statements across time and across other companies. Comparability oRead more

    Yes, I agree with your statement that accounting information should be comparable.

    Comparability is one of the qualitative characteristics of accounting information. It means that users should be able to compare a company’s financial statements across time and across other companies.

    Comparability of financial statements is crucial due to the following reasons:

    1. Intra-Firm Comparison:

    Comparison of financial statements of two or more periods of the same firm is known as an intra-firm comparison.

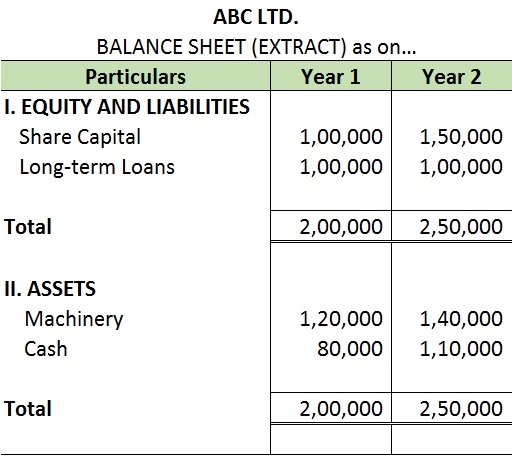
    Comparability of accounting information enables the users to analyze the financial statements of a business over a period of time. It helps them to monitor whether the firm’s financial performance has improved over time.

    The intra-firm analysis is also known as Time Series Analysis or Trend Analysis.

    To understand intra-firm analysis, I have provided an extract of the balance sheet of ABC Ltd. for two accounting periods.

    2. Inter-Firm Comparison:

    Comparison of financial statements of two or more firms is known as an inter-firm comparison.

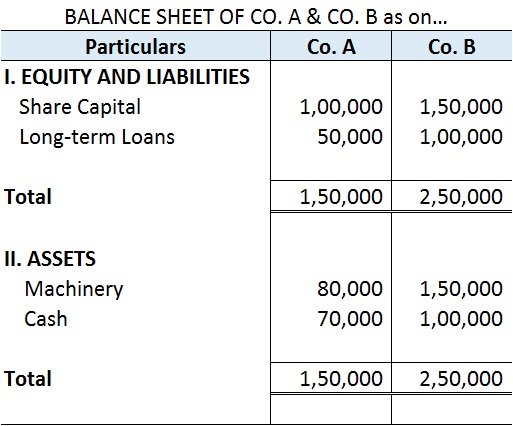
    Inter-firm comparison helps in analyzing the financial performance of two or more competing firms in an industry. It enables the firm to know its position in the market in comparison to its competitors.

    Inter-firm comparison is also known as Cross-sectional Analysis.

    I’ve provided the balance sheets of Co. A and Co.B to make an inter-firm comparison.

    Here is a piece of bonus information for you,

    Sector Analysis – it refers to the assessment of economical and financial conditions of a given sector of a company/industry/economy. It involves the analysis of the size, demographic, pricing, competitive, and other economic dimensions of a sector of the company/industry/economy.

    One more important thing to note here is that comparability can only be achieved when the firms are consistent in the accounting principles and standards they adopt. The accounting policies and standards must be consistent across different periods of the same firm and across different firms in an industry.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Ledger & Trial Balance

How to show sales return in trial balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 28, 2021 at 3:34 pm
    This answer was edited.

    Sales Return is shown on the debit side of the Trial Balance. Sales Return is also called Return Inward. Sales Return refers to those goods which are returned by the customer to the seller of the goods. The goods can be returned due to various reasons. For example, due to defects, quality differenceRead more

    Sales Return is shown on the debit side of the Trial Balance.

    Sales Return is also called Return Inward.

    Sales Return refers to those goods which are returned by the customer to the seller of the goods. The goods can be returned due to various reasons. For example, due to defects, quality differences, damaged products, and so on.

    In a business, sales is a form of income as it generates revenue. So, when the customer sends back those goods sold earlier, it reduces the income generated from sales and hence goes on the debit side of the trial balance as per the modern rule of accounting Debit the increases and Credit the decreases.

    For Example, Mr. Sam sold goods to Mr. John for Rs 500. Mr. John found the goods damaged and returned those goods to Mr. Sam.

    So, here Sam is the seller and John is the customer.

    The journal entry for sales return in the books of Mr. Sam will be

    Particulars Amt Amt
    Sales Return A/c 500
         To Mr John 500

    Treatment in Trial Balance

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.