

To begin with, let me give you a brief explanation of both the terms i.e. Accounting policies and accounting principles- In order to maintain the financial statements, the company’s management adopts various Accounting Policies of its own. This generally includes the rules, the directions as to howRead more
To begin with, let me give you a brief explanation of both the terms i.e. Accounting policies and accounting principles-
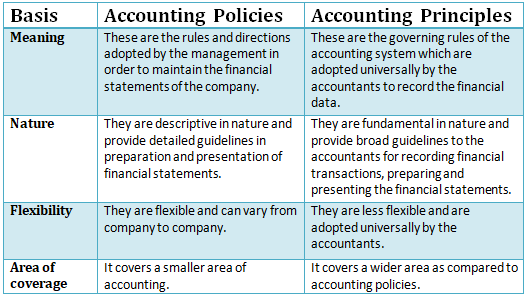
In order to maintain the financial statements, the company’s management adopts various Accounting Policies of its own. This generally includes the rules, the directions as to how the financial statements will be prepared or how the valuation of depreciation would be done, and so on. These are flexible in nature and vary from company to company.
For Example 1, Johnson Co. uses FIFO (first in first out) method to value the inventory. That is to say that, while selling its product, it sells those goods or products which it has acquired or produced first.
It does not consider the LIFO or weighted average cost. The other company may adopt the other method as per its wish.
Example 2, Johnson Co. uses the straight-line method of depreciating an asset, whereas the other company can opt for a written down value method depending upon the need of the company.
So what I am trying to explain from this is that the accounting policies are flexible and can be adopted as per the needs of the company.
Accounting Principles are the rules which the accountants adopt universally for recording and reporting the financial data. It brings uniformity in accounting throughout the practice of accounting. These are generally less flexible in nature.
For Example, “Cost” is a principle. According to this accounting principle, an asset is recorded in the books at the price paid to acquire it and this cost will be the basis for all the subsequent accounting for the asset. However, asset market value may change over time, but for the accounting purpose, it continues to be shown at its book value i.e. at which it is acquired.
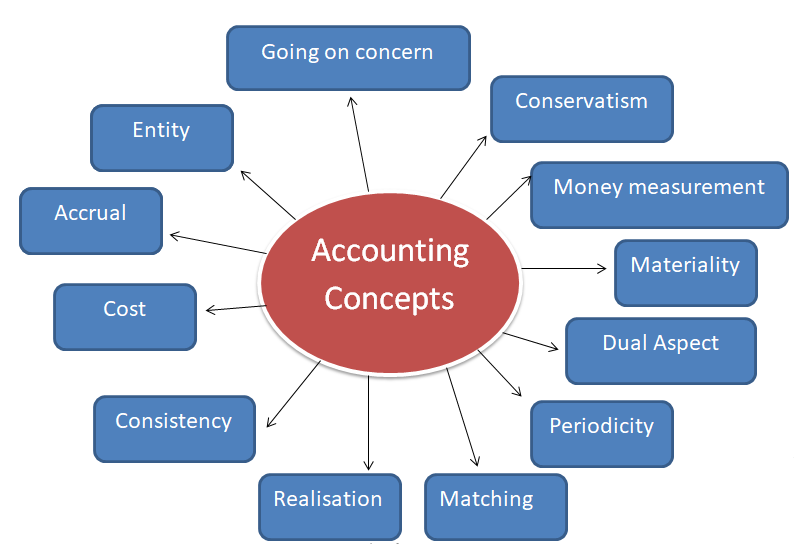
Some more examples would be of Matching principle, Consistency principle, Money measurement principle, etc.
Differences
Conclusion
The point is Accounting Principles are the broad direction to reach a goal and to reach that goal helps the accounting policies.
See less






Revenue and income are two accounting terms that are often used interchangeably. However, it is important to understand that these two terms are different. Let us know the difference between the two through the discussion below: What is Revenue? Revenue is the total amount of a business's sales. ItRead more
Revenue and income are two accounting terms that are often used interchangeably. However, it is important to understand that these two terms are different. Let us know the difference between the two through the discussion below:
What is Revenue?
Revenue is the total amount of a business’s sales. It is the total amount earned by a business before deducting any expenses. Revenue is recognized in accounting as soon as a sale happens, even if the payment hasn’t been received yet.
For example, XYZ Ltd sold 100 pens at a selling price of 10 per pen. The total revenue of the business is hence 1,000.
What is Income?
Income is the amount earned by a business after deducting any direct or indirect expenses. It is the amount that is left after subtracting all expenses, taxes and other costs from Revenue.
Which is a broader term between the two?
Revenue is a broader term as it includes the total earnings a business generates before deducting any expenses. It includes all sales of goods or services during a specific period.
On the other hand, income is calculated after deducting certain expenses like taxes, interest, etc. This makes it more specific and refined than revenue.
Revenue provides a measure of a company’s ability to generate sales and income reflects the efficiency in managing costs and generating profits.
See less