

Capital maintenance is a principle that states profit should not be recorded until its cost or capital has been maintained. In other words, profit should not be recognized unless net assets have been maintained. Capital maintenance states that profit recognized is the increase in the value of net asRead more
Capital maintenance is a principle that states profit should not be recorded until its cost or capital has been maintained. In other words, profit should not be recognized unless net assets have been maintained.
Capital maintenance states that profit recognized is the increase in the value of net assets. However, there are two exceptions to it:
- Cash increased because of sale of stock to shareholders
- Cash decreased because of dividend payout to its shareholders
It is important because:
- It protects the interest of shareholders
- It protects the interest of creditors
- Accurately analyzing the performance of the company
Capital maintenance is of two types:
- Financial Capital Maintenance
It is measured by the value of assets at the beginning and end of the financial year.
- Physical Capital Maintenance
It is measured by the production capacity at the beginning and end of the financial year.
Capital maintenance is concerned with keeping proper account balances of assets and not the physical assets.
Inflation is the increase in the economic value of goods due to the lower purchasing power and not an actual increase in the value of assets. So, if the value of an asset is increased due to inflation it does not depict the right picture for the company.
Hence, if the value of assets increases due to inflation, companies need to adjust the value of assets to assess if capital maintenance has occurred.
See less










Definition Debit balance may arise due to timing differences in which case income will be accrued at the year's end to offset the debit. The amount is shown in the record of a company s finances, by which its total debits are greater than its total credits. The account which has debit balances are aRead more
Definition
Debit balance may arise due to timing differences in which case income will be accrued at the year’s end to offset the debit.
The amount is shown in the record of a company s finances, by which its total debits are greater than its total credits.
The account which has debit balances are as follows:
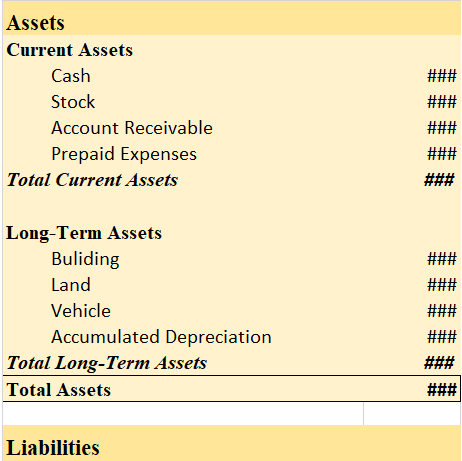
• Assets accounts
Land, furniture, building machinery, etc
• Expenses accounts
Salary, rent, insurance, etc
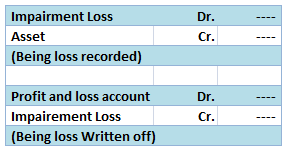
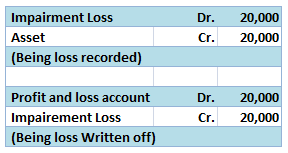
• Losses
Bad debts, loss by fire, etc
• Drawings
Personal drawings of cash or assets
• Cash and bank balances
Balances of these accounts
In class 11th, we learned about all these accounts that have debit balances.
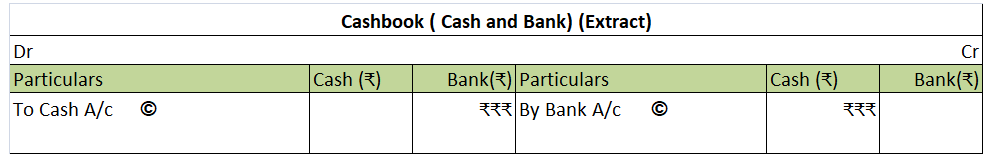
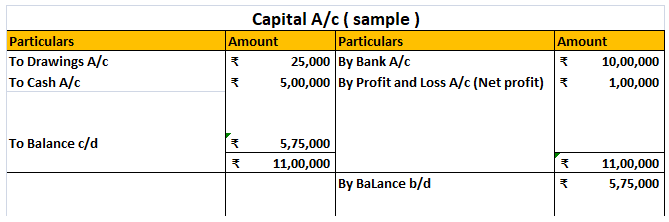
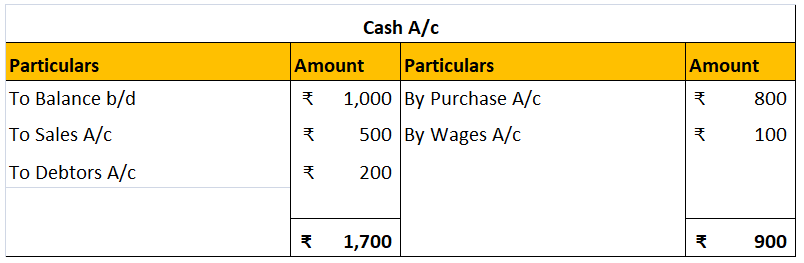
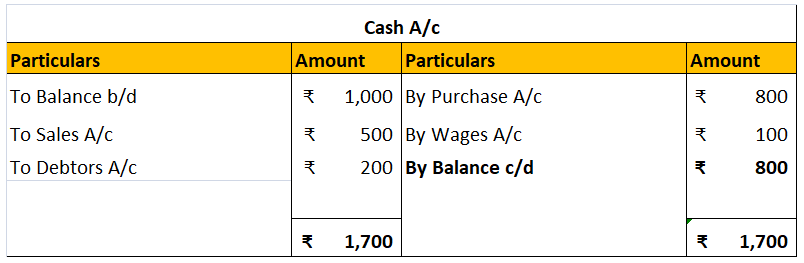
Where the total of the debit side is more than the credit side therefore the difference is the debit balance and is placed credit side as “ by balance c/d “
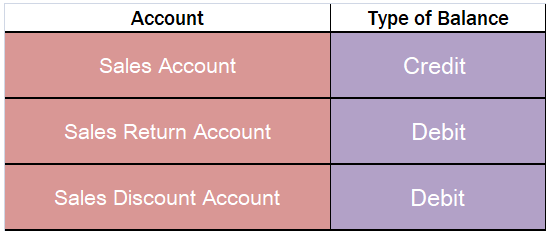
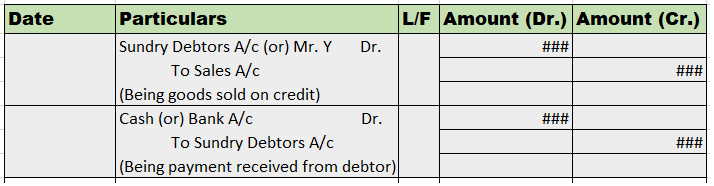
Here are some examples showing the debit balances of the accounts :

See less