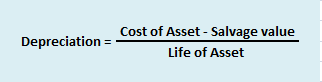
Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Karan
Karan
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation on solar panels as per income tax act?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on July 26, 2021 at 2:11 pm
    This answer was edited.

    As per the Income-tax act, solar panels are categorized under the heading renewal energy devices. The rate of depreciation for these devices is mentioned below. As per the act, the rate of depreciation for solar panels is given as 40% as per the WDV method. Generally, these devices are treated as inRead more

    As per the Income-tax act, solar panels are categorized under the heading renewal energy devices. The rate of depreciation for these devices is mentioned below.

    As per the act, the rate of depreciation for solar panels is given as 40% as per the WDV method. Generally, these devices are treated as investments in fixed assets. Therefore they are treated accordingly like other fixed assets and are depreciated periodically in an organized and regular time period. The useful life of such solar devices is taken to be 5 years.

    Giving you a small example of the depreciation on solar panels.

    Solar panels were purchased by Agro Farm ltd. for installing them to be used for electricity generation. These panels were bought for Rs 2,00,000. Therefore depreciation to be charged as per income tax act over its useful life of 5 years is as follows:

    Depreciation as per WDV = (Cost of an asset – salvage value)* rate of depreciation

    Depreciation for 1st year = (2,00,000 – 0)* 40% = Rs 80,000

    WDV at the end of 1st year = (2,00,000 – 80,000) = Rs 1,20,000

    Depreciation for 2nd year = (1,20,000 – 0)* 40% = Rs 48,000

    the same process will continue till the useful life of an asset.

    The depreciation amount will be written off from the book value as shown below:

    Useful life Value at the beginning of the year Depreciation amount Value at the end of the period
    1 2,00,000 80,000 1,20,000
    2 1,20,000 48,000 72,000
    3 72,000 28,800 43,200
    4 43,200 17,280 25,920
    5 25,920 10,368 15,552


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Depreciation & Amortization

What is straight line depreciation journal entry?

  • 1 Answer
  • 0 Followers
Answer
  1. Mitika
    Added an answer on November 24, 2022 at 5:49 pm

    Straight Line Depreciation Journal Entry Straight-line depreciation refers to the diminishing value of assets over the life of the asset. In other words, the cost of the asset spreads evenly over the useful life of the assets. The salvage value or Residual value of an asset means the estimated valueRead more

    Straight Line Depreciation Journal Entry

    Straight-line depreciation refers to the diminishing value of assets over the life of the asset. In other words, the cost of the asset spreads evenly over the useful life of the assets.

    The salvage value or Residual value of an asset means the estimated value of the asset at the end of its useful life.

    The depreciation can also be charged with another method like Written Down Value (WDV) Method.


    Formula

    Depreciation per annum = ( Cost of asset – Salvage Value) / Useful Life


    The journal entry for the depreciation is:

    JOURNAL ENTRIES

     
    Depreciation on Asset A/C                               DR.
                                To Asset A/C
    (Being depreciation charged on asset)


    Now let us understand this with an example, suppose XYZ Ltd. has an asset of value 90,000 with a useful life of 3 years. The company uses the straight-line method of depreciation to depreciate the asset in its book.


    So, the depreciation per annum would be calculated as:-

    = 90,000/3

    = 30,000


    In Year 1, the depreciation will be charged as 30,000 for this year. It will be debited to the  depreciation account and credited to the asset account. Thus, the value of the asset at the end of year 1 will be 60,000 (90,000-30,000).

    JOURNAL ENTRIES

     
      DR CR
    Depreciation on Asset A/C                                                   30,000
              To Asset A/C                                                                                                              30,000
    (being depreciation charged on asset)


    In Year 2, the depreciation will be charged as  30,000. The entry would be the same as the previous year. The value of the asset at the end of year 2 will be 30,000 (60,000-30,000).

    JOURNAL ENTRIES  
      DR CR
    Depreciation on Asset A/C                                                   30,000
              To Asset A/C                                                                                                                  30,000
    (being depreciation charged on asset)


    At last in Year 3, the depreciation will be charged 30,000. The entry would be the same. The value of the asset at the end of year 3 will be Nil (30,000- 30,000).

    JOURNAL ENTRIES

     
      DR

    CR

    Depreciation on Asset A/C                                                30,000
              To Asset A/C                                                                                                            30,000
    (being depreciation charged on asset)


    The depreciation will be charged to the profit and loss account for the year as it is an expense for the company.


    The entries will be posted into depreciation account as mentioned:

    DEPRECIATION A/C  
    Date Particulars Amount Date Particulars Amount
    Year 1 To Asset A/C 30,000   By Profit and Loss A/C 30,000
        30,000     30,000
               
    Year 2 To Asset A/C 30,000   By Profit and Loss A/C 30,000
        30,000     30,000
               
    Year 3 To Asset A/C 30,000   By Profit and Loss A/C 30,000
        30,000     30,000


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Sandy
Sandy
In: 1. Financial Accounting > Depreciation & Amortization

What are the different methods of charging depreciation?

Depreciation
  • 1 Answer
  • 0 Followers
Answer
  1. Nistha Pursuing B.COM H (B&F) and CMA
    Added an answer on June 27, 2021 at 3:14 pm
    This answer was edited.

    Depreciation refers to that portion of the value of an asset that is written off over the useful life of the asset due to wear and tear. Now, when we talk about depreciation, there are multiple methods to calculate depreciation such as: Straight Line Depreciation Method Diminishing Balance Method OrRead more

    Depreciation refers to that portion of the value of an asset that is written off over the useful life of the asset due to wear and tear.

    Now, when we talk about depreciation, there are multiple methods to calculate depreciation such as:

    • Straight Line Depreciation Method
    • Diminishing Balance Method Or Written Down Value Method
    • Sum of Years’ Digits Method
    • Double Declining Balance Method
    • Sinking Fund Method
    • Annuity Method
    • Insurance Policy Method
    • Discounted Cash Flow Method
    • Use Based Methods
      • Output Method
      • Working Hours Method
      • Mileage Method
    • Other Methods
      • Depletion Method
      • Revaluation Method
      • Group or Composite Method

    The most commonly used methods are discussed below:

    1. Straight Line Depreciation Method: This is the simplest method for calculating depreciation where a fixed amount of depreciation is charged over the useful life of the asset.

    Formula:

    Suppose a company Bear Ltd purchases machinery costing 8,00,000 with useful life of 10 years and salvage value 1,00,000. Then depreciation charged to the machinery each year would be:

    Depreciation = (8,00,000 – 1,00,000)/10 = 7,00,000/10 = 7,000 p.a.

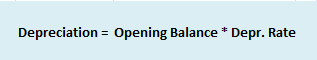
    2. Diminishing Balance Method Or Written Down Value Method: Under this method, a fixed rate of depreciation is charged every year on the opening balance of the asset which is the difference between the previous year’s opening balance and the previous year’s depreciation. Here the book value of asset reduces every year and so does the depreciation amount.

    Formula:

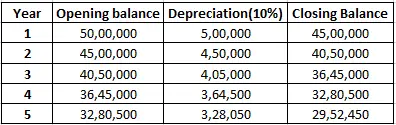
    Suppose a company Moon ltd purchases a building for 50,00,000 with a useful life of 5 years and decides to depreciate it @ 10% p.a. on Diminishing Balance Method. Then depreciation charged to the machinery would be:

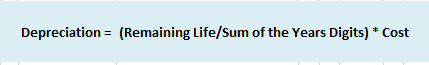
    3. Sum of Years’ Digits Method: In this method, the life of asset is divided by the sum of years and multiplied by the cost of the asset to determine the depreciating expense. This method allocates higher depreciation expense in the early years of the life of the asset and lower depreciation expense in the latter years.

    Formula:

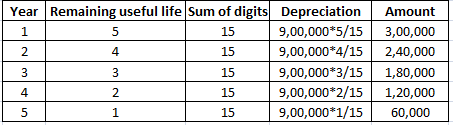
    Suppose a company Caps Ltd purchases machinery costing 9,00,000 having a useful life of 5 years. Then the depreciation cost would be:

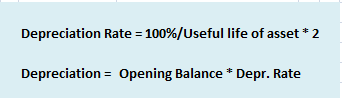
    4. Double Declining Balance method: This method is a mixture of straight-line method and diminishing balance method. A fixed rate of depreciation is charged on the reduced value of the asset at the beginning of the year. This rate is double the rate charged under straight-line method.

    Formula:

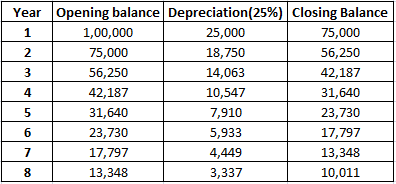
    Suppose a company Paper Ltd purchases machinery for 1,00,000 with an estimated useful life of 8 years. Then the depreciation rate would be:

    Straight line = 100%/8 = 12.5%

    Double declining method = 2*12.5% = 25%

    5. Sinking Fund Method: Under this method, the amount of depreciation keeps on accumulating till the asset is completely worn out. Depreciation is the same every year. Profits equal to the amount of depreciation is invested each year outside the company. At the time of replacement of the asset the investments and sold and the proceeds thereof are used to purchase the new asset.

    6. Annuity Method: This method calculates depreciation by calculating its internal rate of return (IRR). Depreciation is calculated by multiplying the IRR with an initial book value of the asset, and the result is subtracted from the cash flow for the period.

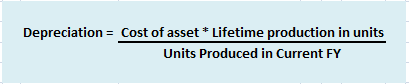
    7. Use Based Methods: Depreciation, under these methods, is based on the total estimated machine hours or total estimated units produced during the life of the machine. It is calculated by dividing the cost of the machine by the estimated total machine hours or estimated lifetime production in units and multiplying by the units produced or machine hours worked.

    Formula:

    Suppose a company Box Ltd purchases machinery for 25,000 (estimated life 5 years) whose estimated life production is 5,000 units. If it produces 700 units in the first year of operation then depreciation cost would be:

    Depreciation = 25,000/5,000*700 = 3,500

    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Depreciation & Amortization

What is depreciation on tools and equipment?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 18, 2022 at 2:00 pm
    This answer was edited.

    Depreciation on Tools and Equipment Tools and Equipment are the instruments that are used for producing any product, machine, or service. Also, tools and equipment are a part of plants and machinery, making them a major fixed asset. Therefore, a certain percentage of depreciation is charged on ToolsRead more

    Depreciation on Tools and Equipment

    Tools and Equipment are the instruments that are used for producing any product, machine, or service. Also, tools and equipment are a part of plants and machinery, making them a major fixed asset. Therefore, a certain percentage of depreciation is charged on Tools and Equipment.

    As we’re aware, depreciation refers to a process in which assets lose their value over time until it becomes obsolete or zero. It is chargeable on the fixed assets and it ultimately results in depreciation of the value of fixed assets except, land. The land is an exception in fixed assets as where all the fixed assets are depreciated, the land’s value is appreciated over time.

    The rate of depreciation as per the Income Tax Act on tools and equipment (plant and machinery) is 15%.

    Example

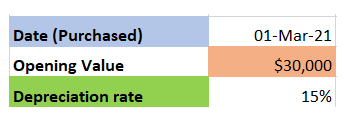
    Suppose given below are the details regarding the tools and equipment:

    And, we’re required to calculate the value of the tools and equipment as on 1-Mar-22

    In this, as we can see the business’ accounting period starts in March and ends in April. Therefore, we can easily deduct the depreciation amount and get the desired result.

    Solution: Opening Value = $30,000

    Depreciation = 15% of $30,000 = $4,500

    Value of tools and equipment as on 1-Mar-22 = $30,000 – $4500 = $25,500


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Depreciation & Amortization

What is vehicle depreciation journal entry?

  • 1 Answer
  • 0 Followers
Answer
  1. Poorvi_*
    Added an answer on November 24, 2022 at 4:11 pm
    This answer was edited.

    When the Accumulated depreciation account is not maintained, the journal entry for vehicle depreciation shall be                              Particulars     Debit   Credit Depreciation a/c                                              Dr.      (xxx)      To Vehicle a/c      (xxx) (Being DepreciationRead more

    When the Accumulated depreciation account is not maintained, the journal entry for vehicle depreciation shall be

                                 Particulars     Debit   Credit
    Depreciation a/c                                              Dr.      (xxx)
         To Vehicle a/c      (xxx)
    (Being Depreciation charge on Vehicle made)

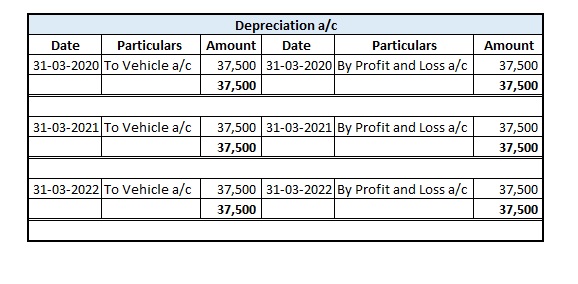
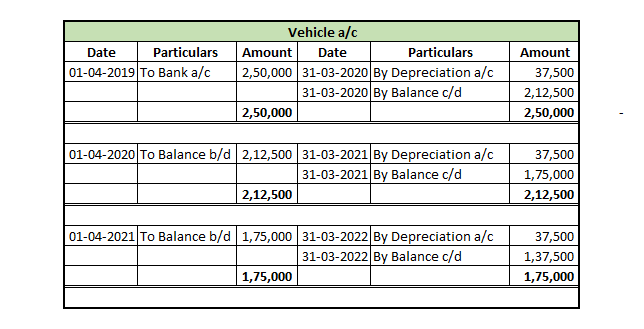
    For example, let us assume that a vehicle (Bike) was purchased on 1st April 2019 with INR. 2,50,000, the rate of depreciation is 15% and also the Company follows the straight-line method of calculating depreciation.

    Then the journal entries shall be,

    The depreciation charge for the 1st Year 

            Date                                Particulars  Debit  Credit
    31-03-2020 Depreciation a/c Dr.  37,500
        To Vehicle a/c  37,500
    (Being Depreciation made on Vehicle)

    The depreciation charge for the 2nd Year 

            Date                                Particulars  Debit  Credit
    31-03-2021 Depreciation a/c Dr.  37,500
        To Vehicle a/c  37,500
    (Being Depreciation made on Vehicle)

    The depreciation charge for the 3rd Year

            Date                                Particulars  Debit  Credit
    31-03-2022 Depreciation a/c Dr.  37,500
        To Vehicle a/c  37,500
    (Being Depreciation made on Vehicle)

    The respective ledger accounts for all three years are given below:

    When the Accumulated depreciation account is maintained, the journal entry for vehicle depreciation shall be

                                 Particulars   Debit   Credit
    Depreciation a/c                                              Dr.    (xxx)
         To Accumulated depreciation a/c    (xxx)
    (Being Depreciation charge on Vehicle made)

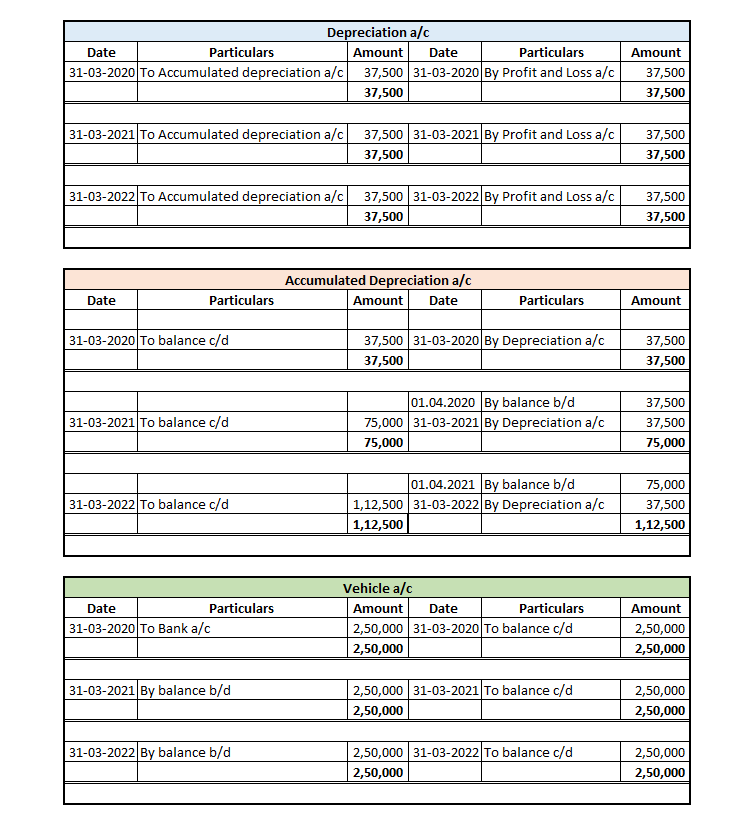
    Taking the above said example,

    The depreciation charge for the 1st Year 

            Date                                Particulars  Debit  Credit
    31-03-2020 Depreciation a/c Dr.  37,500
        To accumulated depreciation a/c  37,500
    (Being Depreciation made on Vehicle)

    The depreciation charge for the 2nd Year 

            Date                                Particulars  Debit  Credit
    31-03-2021 Depreciation a/c Dr.  37,500
        To accumulated depreciation a/c  37,500
    (Being Depreciation made on Vehicle)

    The depreciation charge for the 3rd Year

            Date                                Particulars  Debit  Credit
    31-03-2021 Depreciation a/c Dr.  37,500
        To accumulated depreciation a/c  37,500
    (Being Depreciation made on Vehicle)

    The respective ledger accounts for all three years are given below:


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.