

Software is not depreciated but amortized, as it is an intangible asset. As per companies act the useful life of software is 3 years. The treatment of depreciation is the same as computers. Following are the software depreciation rates as per the companies act: As of 2021 Nature of Asset Useful LifeRead more
Software is not depreciated but amortized, as it is an intangible asset. As per companies act the useful life of software is 3 years. The treatment of depreciation is the same as computers. Following are the software depreciation rates as per the companies act:
As of 2021
| Nature of Asset | Useful Life | Depreciation | |
| WDV | SLM | ||
| Servers and networks | 6 years | 39.30% | 15.83% |
| End-user devices such as desktops, laptops, etc. | 3 years | 63.16% | 31.67% |
For example, XYZ Ltd purchased a new accounting software on 1 October for Rs.50,000. As per the Companies Act, the useful life of software is 3 years. Hence, the software will be amortized for 3 years and the company amortizes on the straight-line method.
Amortization amount = 50,000*31.67%
For full year = Rs.15,835
As the software was purchased on 1 October hence it will be amortized for 6 months.
For 6 months = 15,835*6/12
= Rs.7,917.50
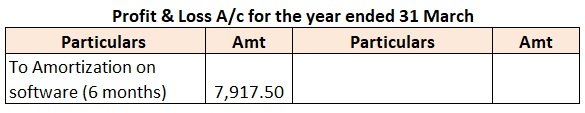
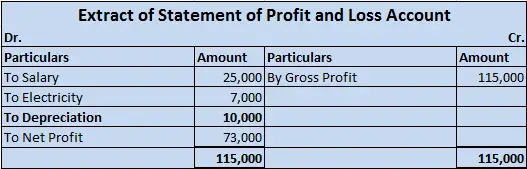
Amortization is the same as depreciation. Hence, treatment will also be the same. The amortization amount will be transferred to the Profit & Loss A/c on the debit side as a non-cash expense.
See less







Plant and Machinery are the equipment attached to the earth that supports the manufacturing of the company or its operations. These are tangible non-current assets to the company and as a result, have a debit balance. Depreciation is the decrease in the value of an asset that is spread over the expeRead more
Plant and Machinery are the equipment attached to the earth that supports the manufacturing of the company or its operations. These are tangible non-current assets to the company and as a result, have a debit balance.
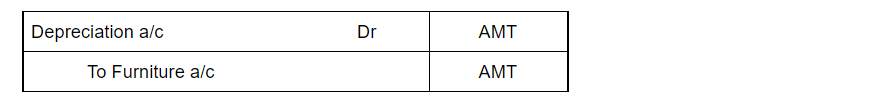
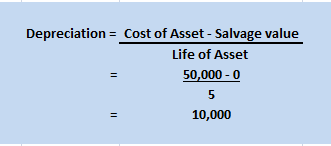
Depreciation is the decrease in the value of an asset that is spread over the expected life of the asset. Not depreciating an asset presents a false image of the company as the asset is recorded at a higher value and profit is overstated as depreciation expense is not provided for.
There are two ways that a company provide depreciation:
For most of the depreciation methods, we need a rate to provide for depreciation every year. Now, for accounting purposes, the management can use a rate they think is suitable depending on the use and expected life of the machinery.
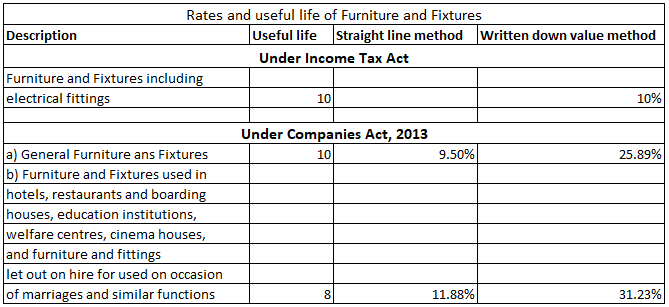
Depreciation is calculated on the basis of the Companies act, 2013 for the purpose of book-keeping. According to Schedule 2 of the Companies Act, depreciation on plant and machinery is calculated on the basis of either SLM or WDV.
Plant and machinery for those special rates are not assigned useful life is considered to be 15 years and depreciation is calculated @ 18.10% on WDV and @6.33% on SLM.
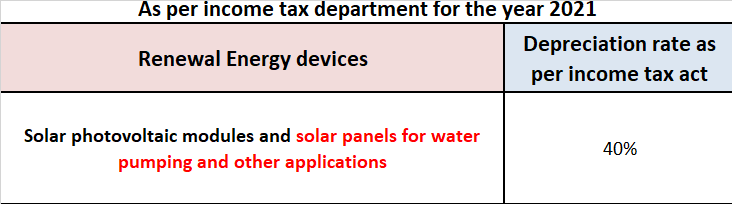
According to the Income Tax Act, 15% depreciation is provided every year on Plant and Machinery and, an additional 20% depreciation is provided in the first year of installation of machinery.
Depreciation on Machinery is charged on the basis of usage of such machinery. if it is used for 180 days or more then full depreciation is allowed and if it is used for less than 180 days then only 50% depreciation is allowed.
See less