Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Ledger & Trial Balance

How to treat sundry debtors in trial balance?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 29, 2022 at 10:15 pm
    This answer was edited.

    Sundry Debtors in Trial Balance The debtor is a company's asset, and assets are always debited in the trial balance. The trial balance is a statement maintained at the end of an accounting period, listing the ending balances in each general ledger account. There are two sides to this account, debit,Read more

    Sundry Debtors in Trial Balance

    The debtor is a company’s asset, and assets are always debited in the trial balance.

    • The trial balance is a statement maintained at the end of an accounting period, listing the ending balances in each general ledger account.
    • There are two sides to this account, debit, and credit and they include all the transactions done in the business over a particular accounting period.


    As we know, assets, expenses, and drawings are always debited. That applies not only in journals but here as well, hence, all of your assets are to be debited.

    Trial Balance Statement


    As we can see here, the sundry debtors (on the 4th) are debited like all the other assets, expenses, and losses. In the end, if the basic accounting equation i.e. assets=capital+liability is violated, a mismatch arises which in the balancing figure is shown under the name of suspense account. Such errors must not be found and corrected to avoid any mismatch in the balance sheet of the company.

    Total Assets = Capital + Other Liabilities.

    Therefore, this is how the sundry debtors are treated in the Trial Balance.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

Which account has a debit balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Saurav
    Added an answer on September 20, 2023 at 4:40 pm
    This answer was edited.

    Debit balance means excess of credit side over debit side. For Example- At the beginning of the year the debit balance of trade receivables is 3,000 and there is a decrease(credit) of trade receivables of 1,000 during the year and an increase(debit) of trade receivables of 4,000 then at the end therRead more

    Debit balance means excess of credit side over debit side.

    For Example- At the beginning of the year the debit balance of trade receivables is 3,000 and there is a decrease(credit) of trade receivables of 1,000 during the year and an increase(debit) of trade receivables of 4,000 then at the end there will be a debit balance of 6,000 of trade receivables at the end

    A Debit balance basically signifies all expenses and losses and all positive balances of assets. The debit balance increases when any asset increases and decreases when any asset decreases.

    Assets

    All the assets that appear in the balance sheet always have a debit balance. The debit balance under it will increase as it debits. Some of these assets can be illustrated below -:

    •  Cash and Bank Balance: Cash and Bank Balance means the amount that is held by a person in physical form or in a current/savings account.
    • Property, Plant, and Equipment-  Property Plant, and Equipment means assets that are used for the production of goods and services.
    • Account Receivables– Account Receivables means the amount that is due from debtors to whom goods were sold at credit for a specified time period.
    • Inventory – Inventory means goods that are used in the normal course of business.
    • Investments– Investments are the amount invested in other companies from which they were expecting returns in future periods.


    Expenses and Losses

    All expenses that appear on the debit side of the P&L account have a debit balance in their accounts.

    For eg-: A rent of 10,000 is given to the landlord under which the work has been done by the entity.

    For eg-: A depreciation of 10% is there on an asset of 12,000 will result in a debit balance under depreciation in the P&L Account.

    Some of the following expenses can be illustrated below

    • Rent- Rent means a property that an entity takes on lease for business purpose and pay a certain amount to the landlord for such lease.
    • Depreciation– Depreciation means a fall in the value of an asset due to its usage every year
    • Loss on Sale of an asset- Loss on the Sale of an Asset means the sale amount of the asset is less than its WDV
    • Printing and stationery– Printing and Stationery means the paperwork or anything related to stationery used for business purposes
    • Audit fees– Audit fees are the amount which is given to an auditor for auditing the financials of an entity
    • Salaries and Wages– Salaries and Wages are the amount given to employees for the work they have done for the entity
    • Insurance– Insurance means a premium given by an entity for insurance done by them
    • Advertising– Advertising means any promotion that a company does of its product to increase its revenue

    So after seeing all the above points we can conclude that the debit balance includes all the expenses that are in the P&L account and all the assets that are there in the Balance sheet. So its balance increases when there is an increase in its account.


    CREDIT BALANCE

    Credit balance means excess of credit side over debit side.

    For example, At the beginning of the year, the credit balance of trade payable is 3,000 and there is a debit of trade payable of 1,000 during the year and an increase(credit) of trade payable of 4,000 then at end there will be a credit balance of 6,000 for trade payable at the end

    .A Credit balance signifies all income and gains and all liabilities and capital that is there in business.

    Liabilities

    • Account Payables
    • Bank Overdraft
    • Bonds
    • Income Tax Payables
    • Notes Payable
    • Deferred Tax Liability


    Income and Gains

    • Interest Received
    • Dividend Received
    • Rent Received
    • Gains on Sale of Capital Gains


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Ledger & Trial Balance

How to post a compound entry in ledger account?

Compound EntryLedger
  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on June 17, 2021 at 2:40 pm
    This answer was edited.

    When in a single transaction two or more accounts are involved, such kinds of transactions are termed as Compound entries. Example 1, Johnson Co. purchased goods worth 5,000, and half of the amount was paid in cash and the other half by cheque. So here three accounts are involved: Purchase account-Read more

    When in a single transaction two or more accounts are involved, such kinds of transactions are termed as Compound entries.

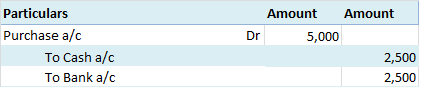
    Example 1, Johnson Co. purchased goods worth 5,000, and half of the amount was paid in cash and the other half by cheque.

    So here three accounts are involved:

    Purchase account- That is to be debited.

    Cash account- That is to be credited.

    Bank account- That is to be credited.

    Journal entry:

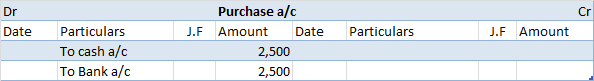
    Now posting the above journal entry in a ledger account.

    In the Journal, the Purchase account has been debited. So in the ledger, the purchase account will also be debited. Since the purchase account is debited in the ledger, the corresponding two credit accounts of this entry i.e. the cash and the bank will be written on the debit side in the particulars column. So while posting, the amount to be considered would be the amount individually paid in cash and bank as shown in the journal entry.

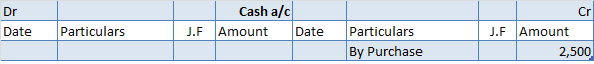
    Cash a/c is credited with the purchase account.  In the ledger, purchase a/c will be posted on the credit side. So while posting, the amount to be considered would be the amount individually paid in cash.

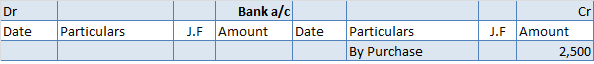
    Bank a/c is credited with the purchase account. In the ledger, purchase a/c will be posted on the credit side. So while posting, the amount to be considered would be the amount individually paid in Bank a/c.

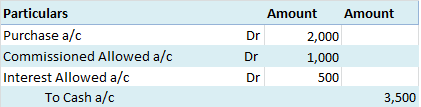
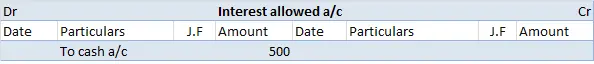
    Example 2,  Johnson Co purchased goods and made payment in cash 2,000. Along with it, it also paid commission and interest of 1,000 and 500 respectively.

    So here four accounts are involved:

    Purchase account- That is to be debited.

    The commission allowed account- That is to be debited.

    Interest allowed account- That is to be debited.

    Cash account- That is to be credited.

    Journal Entry:

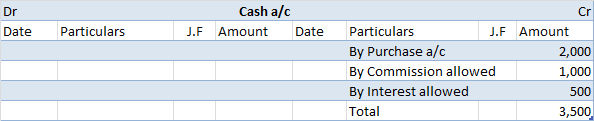
    Now posting the above journal entry in a ledger account.

    In the journal entry, the cash account has been credited. So in the ledger, the cash account will also be credited. Since the cash account is credited in the ledger, the corresponding three accounts will also be credited in the particulars column. As in the journal entry the three debit accounts viz. Purchase, the commission allowed, and interest allowed, the amounts written against them shall be entered in the respective accounts in the amount column on the credit side of the cash account.

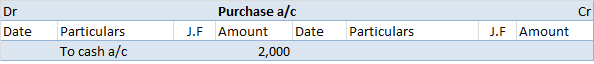
    Purchase a/c is debited with a cash account.  In the ledger, Cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in the Purchase account.

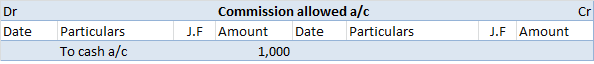
    The commission allowed a/c is debited with a cash account.  In the ledger, cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in Commission allowed a/c.

    Interest allowed a/c is debited with a cash account.  In the ledger, cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in Interest allowed a/c.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Ledger & Trial Balance

Which errors are revealed by trial balance?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 18, 2022 at 8:24 pm
    This answer was edited.

    Errors revealed by Trial Balance Trial balance, as we know, is a statement prepared after the ledger, followed by a journal. It has a list of all the general ledger accounts contained in the ledger of a business. Each nominal ledger account either holds a debit balance or credit. It is primarily useRead more

    Errors revealed by Trial Balance

    Trial balance, as we know, is a statement prepared after the ledger, followed by a journal. It has a list of all the general ledger accounts contained in the ledger of a business. Each nominal ledger account either holds a debit balance or credit.

    It is primarily used to identify the balance of debits and credits entries from the transactions recorded in the general ledger in a certain accounting period. The debit and credit sides total are equal in a trial balance.

    Classification of errors in the trial balance

    • Errors of Commission: Errors arising due to wrong posting of a journal entry, a ledger account, wrong totaling of a subsidiary book, or even wrong recording of accounts. Therefore, resulting in trial balance error. E.g business receives an amount on goods sold on credit but it is instead posted to additional capital a/c.
    • Errors of Omission: This occurs when some transactions are fully or partially omitted from books of accounts. A complete omission is a case when the transaction is completely omitted but a partial omission is seen when the transaction is entered in the journal but not posted to the ledger. E.g a cheque worth $4,100 was received from ABC Ltd. but completely omitted. Then the rectification entry shall be passed later on.
    • Compensating Errors: It occurs when the errors are equal in amount and opposite to each other so and so that they cancel each other which further creates no difference in the Trial Balance. E.g Harry’s account is debited to $300 wrongly instead of $400. On the other hand, Liam’s account is credited by $700 instead of $800.
    • Errors of Principles: These are the errors occurring when the entries that are posted are incorrect, violating the accounting policy. E.g when receiving money from debtor then debiting debtor and crediting the amount of money received.

    Some of the common errors

    Some more (commonly seen) errors while preparation of the trial balance:

    Errors of Commission

    1. Addition or totaling mistakes in the trial balance, debit, and credit side.
    2. Wrong totaling of subsidiary books.
    3. Error in the sum total of subsidiary book.
    4. Posting in the wrong account.
    5. Recording a transaction incorrectly in a journal.
    6. Balance wrote on the wrong side of the trial balance.
    7. Error in posting a journal to a ledger.
    8. Posting on the wrong side of the account.

    Errors of Omission

    1. Goods purchased and returned to the supplier may be entered in the purchase returns book but not posted in the debit of the supplier account.
    2. Cash paid to creditors was completely omitted from the recording.

    Compensating Errors

    • Wrong posting of the same amount in another account, which may not be affecting the equalizing of trial balance.

    Errors of Principles

    1. Posting twice to a ledger account.
    2. Balance c/d or balance b/d is written on the wrong side of the ledger account.
    3. Reversal of a journal entry by mistake like, crediting cash and debiting debtor’s a/c.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.