Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Recent Questions
  • Most Answered
  • Answers
  • Most Visited
  • Most Voted
  • No Answers

AccountingQA Latest Questions

Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

Is Land a Current Asset?

Current Assets
  • 2 Answers
  • 0 Followers
Answer
  1. Bonnie Curious MBA (Finance)
    Added an answer on June 27, 2021 at 5:34 am
    This answer was edited.

    Similarly, someone asked Are loose tools current assets

    Similarly, someone asked Are loose tools current assets

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Journal Entries

Started business with cash 50000 entry?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 24, 2022 at 9:51 am
    This answer was edited.

    There are three types of businesses that can be commenced, they are sole proprietorship, partnership, and joint-stock company. As we all know, to start any business a certain sum of money has to be invested by the owner which is known as the capital of the business in terms of accounting. In companiRead more

    There are three types of businesses that can be commenced, they are sole proprietorship, partnership, and joint-stock company. As we all know, to start any business a certain sum of money has to be invested by the owner which is known as the capital of the business in terms of accounting.

    In companies, commencement is a declaration issued by the company’s directors with the registrar stating that the subscribers of the company have paid the amount agreed. In a sole proprietorship, the business can be commenced with the introduction of any asset such as cash, stock, furniture, etc.

    Journal entry

    In the journal entry, “Started business with Cash”

    As per the golden rules of accounting, the cash a/c is debited because we bring in cash to the business, and as the rule says “debit what comes in, credit what goes out.” Whereas the capital a/c is credited because “debit all expenses and losses, credit all incomes and gains”

    As per modern rules of accounting, cash a/c is debited as cash is a current asset, and assets are debited when they increase. Whereas, on the increment on liabilities, they are credited, therefore, capital a/c is credited.

    Therefore, the entry we’ll be passing is-
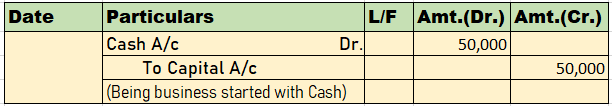


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Partnerships

What is not included in Realisation account?

  • 1 Answer
  • 0 Followers
Answer
  1. Kajal
    Added an answer on September 29, 2023 at 12:29 am

    A Realisation account is prepared at the time of dissolution of the Partnership firm to ascertain profit or loss from the sale of assets and payment of liabilities of the firm. All assets that can be converted into cash (i.e. from which any value can be realised) and all external liabilities to be pRead more

    A Realisation account is prepared at the time of dissolution of the Partnership firm to ascertain profit or loss from the sale of assets and payment of liabilities of the firm. All assets that can be converted into cash (i.e. from which any value can be realised) and all external liabilities to be paid are transferred to the Realisation A/c.

    So, Cash and Bank (already in liquid form), fictitious assets (doesn’t have any value to be realised), Partner’s Loan (internal liability) and Undistributed profits (not something that can be realised) are not included in the Realisation account.


    DISSOLUTION OF PARTNERSHIP FIRM

    It means the firm closes down its business and comes to an end. Simply, it means the firm will cease to exist in the future. As the firm is closing down, its assets are sold, liabilities are paid off, and the remaining amount (if any) is distributed among the partners.


    REALISATION ACCOUNT

    This account is prepared only once, at the time of dissolution of the Partnership firm. It is opened to dispose of all the assets of the firm and make payments to all the external creditors of the firm.

    It ascertains the profit earned or loss incurred on the realisation of assets and payment of liabilities.


    Items not included in Realisation A/c


    1. ASSETS

    CASH AND BANK BALANCES are not included in the Realisation account as the purpose of the Realisation account is to sell assets to realise cash, but cash and bank are already in liquid form and thus, not included.

    These are directly used for the payment of liabilities and if there is any remaining amount, then that amount is distributed among the partners.


    FICTITIOUS ASSETS are huge expenses or losses that are written off over the years by writing off a portion of it every year for the next few years like accumulated losses, balance of Advertisement expenses, Preliminary expenses, Loss on the issue of Debentures, etc. They don’t have any physical existence or realisable value.

    Since nothing can be realised from these assets they are not included in the Realisation account. These are transferred to the Partner’s Capital A/c.


    2. LIABILITIES


    PARTNER’S LOAN refers to the loan given to the firm by any partner of the firm. 

    Suppose, there are three Partners A, B and C. ‘C’ gave the firm a loan of $5,000. This $5,000 will be recorded as a Partner’s Loan and not just as a normal loan taken from an external party.

    Since, Partner’s Loans are the internal obligation of the firm, they are not included in the realisation account instead a separate account is prepared to settle Partner’s Loan after all external liabilities are settled.

    So, we can say in the Realisation account only external liabilities are included and paid.


    UNDISTRIBUTED PROFITS  are the  Profits that are not distributed among the Partners like General Reserve, Reserve Fund, and Credit balance of P&L A/c.

    They are not included in the realisation account as they can’t be sold as an asset neither they are any liabilities that should be paid. Undistributed profits belong to the Partners of the firm and thus, are transferred to Partner’s capital A/c.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Partnerships

What are unrecorded assets?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on December 16, 2021 at 5:24 am
    This answer was edited.

    Unrecorded Assets are the assets that are completely written off but still physically available in the company or assets that are not shown in the books of the company. Unrecorded assets are generally recorded or recognized at the event of admission, retirement, death of a partner when all the assetRead more

    Unrecorded Assets are the assets that are completely written off but still physically available in the company or assets that are not shown in the books of the company.

    Unrecorded assets are generally recorded or recognized at the event of admission, retirement, death of a partner when all the assets and liabilities are revalued or dissolution of the firm.

    Since Accounting Standards require firms to record all the assets and liabilities in their books, it is therefore mandatory to record such unrecorded assets.

    There can be two cases for treatment of such unrecorded assets:

    • Unrecorded Asset entered into the business and recorded in books
    Unrecorded Asset A/c (Dr.) Amt
     To Revaluation A/c Amt

    The unrecorded asset is now debited since it has to be recorded in the books now and Revaluation Account is credited since it is again for the business which will eventually be transferred to Partners’ Capital Account.

    • Unrecorded Asset taken over by a partner and paid cash   
    Cash A/c (Dr.) Amt
     To Partners’ Capital A/c Amt

    If a partner decides to take over an unrecorded asset then his account is credited with that amount and since cash paid by the partner comes into business Cash Account is debited.

    • Unrecorded Asset discovered during Dissolution
    Cash/ A/c (Dr) Amt
     To Realization A/c Amt

    When an unrecorded asset is discovered during the dissolution of the firm, such an asset is sold directly to the outsider and as a result, cash A/c is debited since the cash is entering the business. The entry is made through the Revaluation A/c and it is hence credited.

    Example:

    At the time of revaluation, firms find a typewriter that has not been recorded in the books and is valued at Rs 10,000.  The journal entry to record that typewriter will be:

    Typewriter A/c (Dr.) 10,000
      To Revaluation A/c 10,000


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Journal Entries

What are 5 types of journal entries?

  • 1 Answer
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Journal Entry is an entry made in the journal is called journal entry. And the process of recording a transaction in a journal is called journalizing. Broadly journal entries are of two types : 1. Simple entry 2. Compound entry Otherwise, they are categorized into seven types which are asRead more

    Definition

    Journal Entry is an entry made in the journal is called journal entry. And the process of recording a transaction in a journal is called journalizing.

    Broadly journal entries are of two types :

    1. Simple entry
    2. Compound entry

    Otherwise, they are categorized into seven types which are as follows :

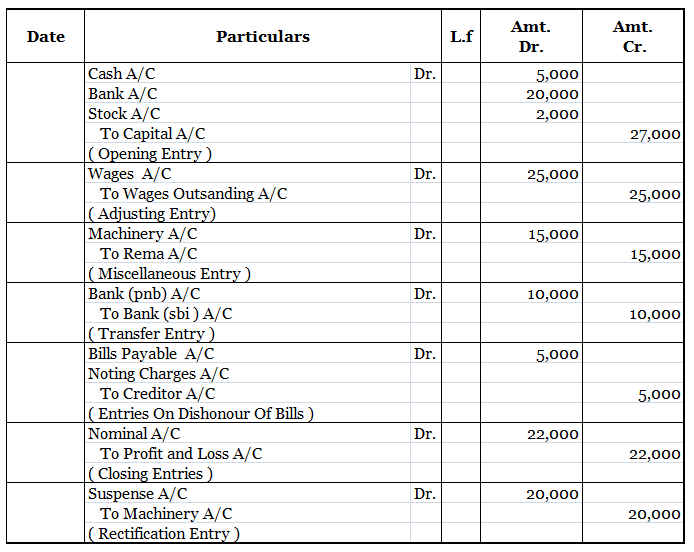
    1. Opening entries
    2. Closing entries
    3. Rectification entries
    4. Transfer entries
    5. Adjusting entries
    6. Entries on dishonor of bills
    7. Miscellaneous entries

    Explanation

    Now let me explain to you the above types of entries mentioned which are as follows ;

    Simple entry
    • Is a journal entry in which one account is debited and another account is credited with an equal amount.
    • For example, the purchase of goods of Rs 5000 cash. It will affect two accounts,i.e., purchase A/C and cash A/C with the amount of Rs 5000.

    Compound entry
    • Is a journal entry in which one or more accounts are debited and/or one or more accounts credited or vice versa.
    • For example the sale of goods to Sati for Rs 5000, Rs 2000 is received in cash, and the balance is to be received later.
    • This transaction of the sale has an effect on three accounts i.e cash or bank A/C, Sati A/C, and sales A/C.

    Opening entries
    • Are defined as when books are started for the new year, the opening balance of assets and liabilities are journalized. For example bills payable, short-term loans, etc.

    Closing entries
    • At the end of the year, the profit and loss account has to be prepared. For this purpose, the nominal accounts are transferred to this account. This is done through journal entries called closing entries.

    Rectification entries
    • If an error has been committed, it is rectification through a journal entry.

    Transfer entries
    • If some amount is to be transferred from one account to another, the transfer will be made through a journal entry.

    Adjusting entries
    • At the end of the year, the number of expenses or income may have to be adjusted for amounts received in advance or for amounts not yet settled in cash.
    • Such an adjustment is also made through journal entries. Usually, the entries pertain to the following :

    Outstanding expenses,i.e., expenses incurred but not yet paid;

    Prepared expenses,i.e., expenses paid in advance for some period in the future ;

    Interest on capital is the interest proprietor’s investment in the business entity investment; and

    Depreciation fall in the value of assets used on account of wear and tear. For all these, journal entries are necessary.

    Entries on dishonor of bills
    • If someone who accepts a promissory note ( or bill) is not able to pay in on the due date, a journal entry will be necessary to record the non–payment or dishonor.

    Miscellaneous entries
    The following entries will also require journalizing
    • Credit purchase of things other than goods dealt in or materials required for the production of goods e.g. Credit purchase of furniture or machinery will be journalized.
    • An allowance to be given to the customers or a charge to be made to them after the issue of the invoice.
    • Receipt of promissory notes or issue to them if separate bills books have not been maintained.
    • On an amount becoming irrecoverable, say, because, of the customer becoming insolvent.
    • Effects of accidents such as loss of property by fire.
    • Transfer of net profit to capital account.

    Here are some examples of journal entries showing the above types :

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Journal Entries

What is furniture journal entry?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on July 22, 2022 at 5:59 pm
    This answer was edited.

    Introduction   Furniture is treated as a fixed asset of an enterprise unless it deals in the manufacturing or the trade of furniture. As stock in trade, it will be treated as current assets. In both cases, they are real accounts. Hence, the golden rule of accounting will be the same. But, when it coRead more

    Introduction


    Furniture is treated as a fixed asset of an enterprise unless it deals in the manufacturing or the trade of furniture. As stock in trade, it will be treated as current assets.

    In both cases, they are real accounts. Hence, the golden rule of accounting will be the same.

    But, when it comes to journal entries, Furniture A/c will appear only when it is treated as a fixed asset.

    No journal entries are passed in the stock-in-trade account except for some balance transferring entries.

    Journal Entries on taking Furniture as a fixed asset

    Taking furniture as a fixed asset, we can pass various entries related to it. Since furniture is an asset, any increase is debited and the decrease is credited.

    Also, furniture is a real account which means the golden rule of accounting  applicable is, “Debit what comes in and credit what goes out”.

    Following are the basic entries related to furniture.

    Purchase of furniture

    The most common entry related to furniture is the purchase of furniture:

    Furniture A/c                                            Dr. Amt
    To Cash / Bank A/c Amt

    Here Furniture A/c is increased, hence debited.
    Cash or Bank being reduced is credited.

    Sale of furniture


    Cash / Bank A/c                                       Dr. Amt
    Profit and Loss A/c *                               Dr. Amt
    To Furniture A/c Amt
    To Profit and Loss A/c  ** Amt

     *In case of loss

    **In case of profit

     On the sale of furniture, its balance gets reduced, hence credited.
    Cash or Bank is debited as cash comes in hand or into the bank.

    Also, profit or loss may arise due to the difference in sale value and the carrying amount of the furniture A/c.

    The difference is debited to Profit and Loss A/c in case of loss and credited in case of profit.


    Depreciation on Furniture

    Depreciation A/c                                         Dr. Amt
    To Furniture A/c Amt

    Here, furniture is credited as it is decreased by the amount of depreciation.

    Depreciation being a non-cash expense, is debited.

    Journal Entries on taking Furniture as stock in trade

    When furniture is stock of trade of a business, the journal entries will be like normal purchase and sales entries as below:


    Purchase A/c                                               Dr. Amt
    To Cash / Bank A/c Amt


    Cash / Bank A/c                                          Dr. Amt
    To Sales A/c Amt

    There will be no furniture account.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 6. Software & ERPs > Tally

How to delete company in tally?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on August 21, 2022 at 8:17 pm
    This answer was edited.

    Deleting a company in Tally Prime Tally prime is the latest version of Tally ERP software. In its functionality, it is slightly different from its previous version Tally ERP 9.  Hence, the process of deleting a company in Tally Prime is different from that in Tally ERP 9. To delete a company in TallRead more

    Deleting a company in Tally Prime

    Tally prime is the latest version of Tally ERP software. In its functionality, it is slightly different from its previous version Tally ERP 9.  Hence, the process of deleting a company in Tally Prime is different from that in Tally ERP 9.

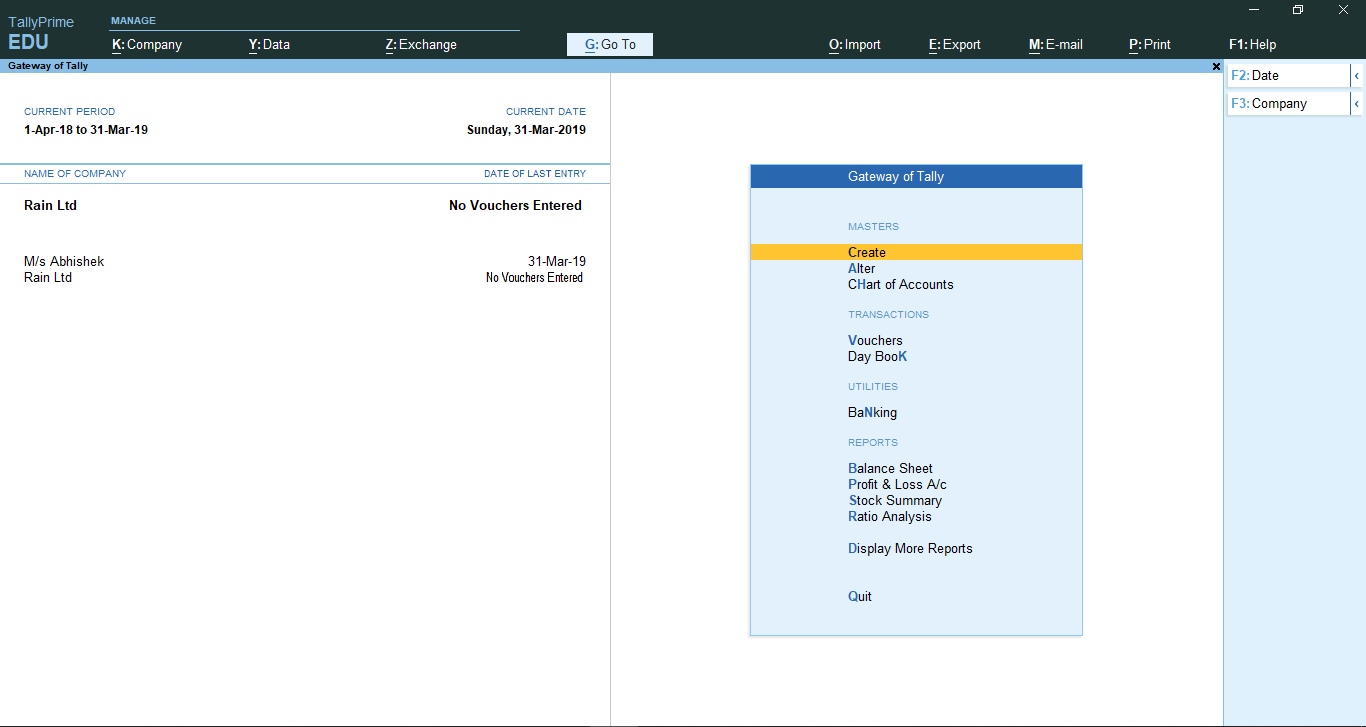
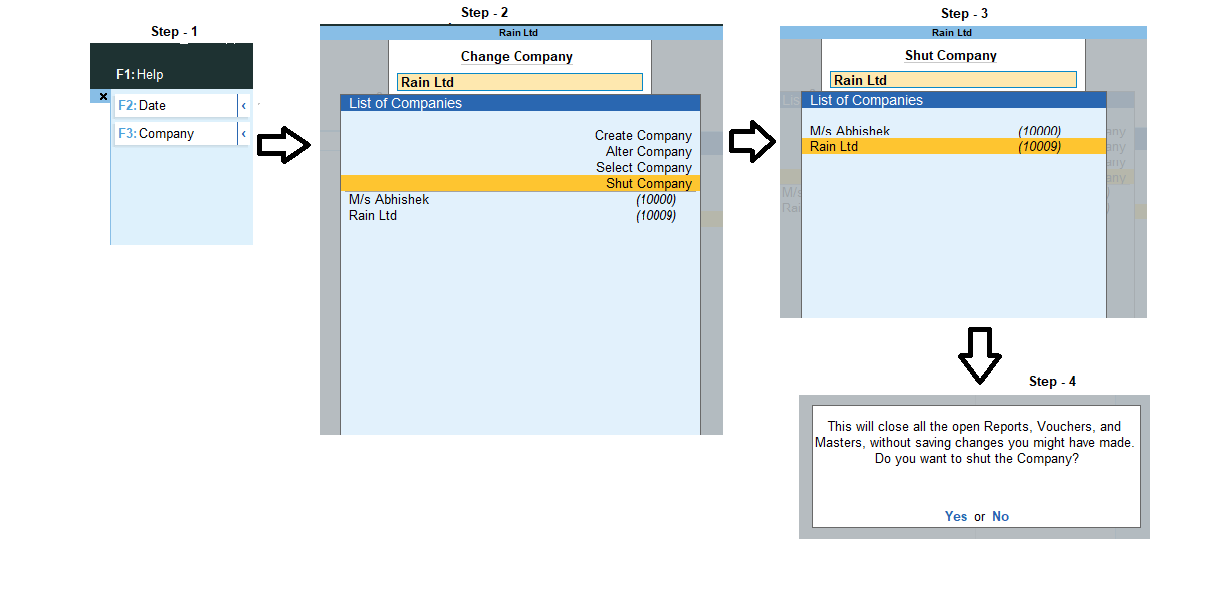
    To delete a company in Tally Prime, you need to be in the Gateway of Tally window which looks the following:

    On the right-hand side, there is a menu where is an option named ‘F3: Company’. You can either click on it or simply press F3.

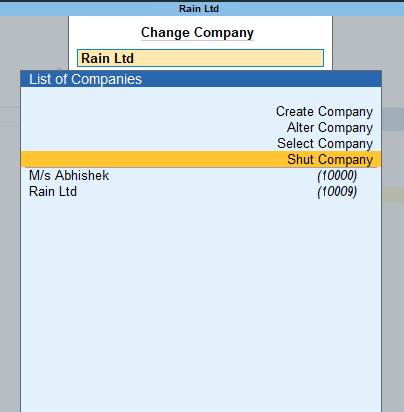
    After clicking on the option, the Company menu where a list of names of the companies created in the Tally is there, along with some options above the company name list.

    You have to select the option named, ‘Shut Company’. After clicking the option, the screen will display a ‘Shut Company’ menu.

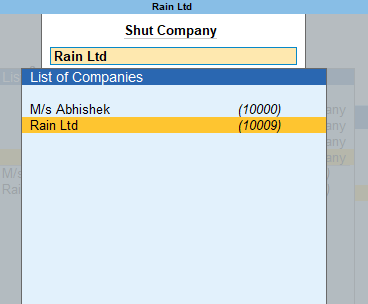
    From there, you have to select the company you want to delete. Like in the example given, I have selected the company named Rain Ltd.

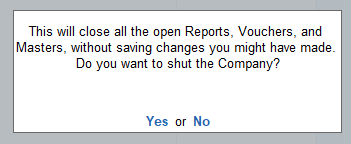
    After selecting the name of the company you want to delete, a confirmation dialog box will appear.

    You have to click OK and the company will be shut down or deleted.

    In short, the steps to delete a company in Tally Prime are as follows:

    Gateway of Tally –> Press F3 –> Select ‘Shut Company’ option –> Select the name of the company –> Confirm and press OK

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Load More Questions

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.