Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of sundry debtors?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 13, 2022 at 4:19 pm
    This answer was edited.

    Sundry debtor refers to either a person or an entity that owes money to the business. If someone buys some goods/services from the business and the payment is yet to be received, a group of such individuals or entities is called sundry debtors. Sundry debtors are also referred to as trade receivableRead more

    Sundry debtor refers to either a person or an entity that owes money to the business. If someone buys some goods/services from the business and the payment is yet to be received, a group of such individuals or entities is called sundry debtors. Sundry debtors are also referred to as trade receivables or account receivables.

    The term ‘Sundry’ means various or several, referring to a collection of miscellaneous items combined under one head. Sundry debtors typically arise from core business activities such as sales of goods or services. The business treats them as an asset.


    Example

    Suppose you run a business, ABC Ltd. Mr. Y bought goods from you on credit. Therefore, Mr. Y will be recorded as Debtor (current asset) in your books of accounts. Similarly, a collection of such debtors is viewed as sundry debtors from the business’ point of view.

    Journal Entry

    Rules

    As per the golden rules of accounting, we ‘debit the receiver and credit the receiver’. That’s how in this journal entry we’ll be debiting the sundry debtor’s account. Also, ‘debit what comes in and credit what goes out.’ That’s why sales a/c is credited and cash a/c is debited.

    As per the modern rules of accounting, ‘debit the increase in asset and credit the decrease in asset’. That’s why we debit sundry debtors and cash a/c. And credit sales a/c when goods are sold and inventory decreases.


    Why debtor is an asset?

    As we know, a debtor refers to a person or entity who owes money to the business which means, the money is to be received by them in the future, making them an asset. On the other hand, creditors are a liability to the firm as we owe them money and it is to be paid by us in the near future, making it an obligation for the firm.


    Sundry Debtors in Balance Sheet

    Sundry debtors are shown under the current asset heading on the balance sheet. They are often referred to as account receivables.


    Balance Sheet (for the year ending….)

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

How is accounting income different from taxable income?

  • 0 Answers
  • 0 Followers
Answer
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Accounting Terms & Basics

Is goodwill real or nominal?

  • 1 Answer
  • 0 Followers
Answer
  1. Akash Kumar AK
    Added an answer on November 21, 2022 at 12:51 pm
    This answer was edited.

    Goodwill In Accounting Aspect, Goodwill refers to an Intangible asset that facilitates a company in making higher profits and is a result of a business’s consistent efforts over the past years which can be the business's prestige, reputation, good name, customer trust, quality service, etc. GoodwillRead more

    Goodwill

    In Accounting Aspect, Goodwill refers to an Intangible asset that facilitates a company in making higher profits and is a result of a business’s consistent efforts over the past years which can be the business’s prestige, reputation, good name, customer trust, quality service, etc.

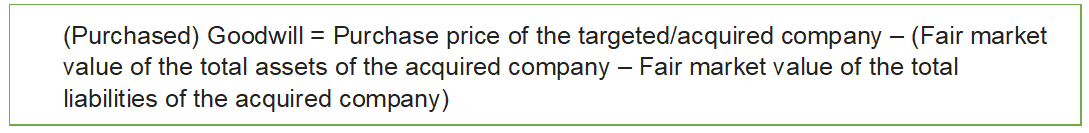
    Goodwill has no separate existence although the concept of goodwill comes when a company acquires another company with a willingness to pay a higher price over the fair market value of the company’s net asset in simple words the goodwill can be only realized while at the time of sale of a business.


    The formula for Goodwill
     

    Types of Goodwill

    there are two types of goodwill.


    1. Inherent Goodwill/Self-generated goodwill

    Inherent goodwill is the internally generated goodwill that was created or generated by the business itself. it is generally generated from the good reputation of the business.

    Inherent Goodwill or Self-generated goodwill is generally not shown in the books or never recognized in the books of Accounts and no journal entry for the inherent goodwill is passed.


    2. Purchased Goodwill/Acquired Goodwill

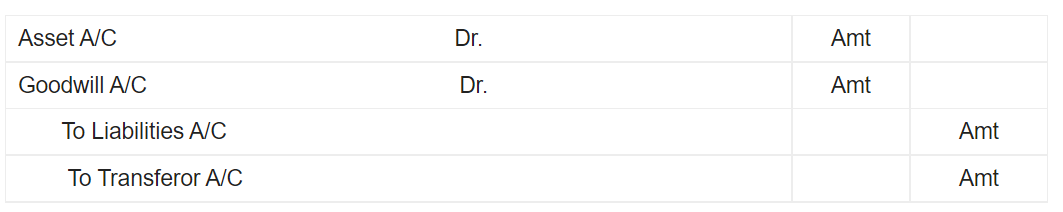
    At the time of acquisition of a business by another business, any amount paid over and above the net assets simply refers to the amount of Purchased Goodwill or Acquired goodwill.

    A Journal entry is passed in the case of the Purchase of goodwill.
     

    Type of Account

    generally, Goodwill is considered and recorded as an Intangible asset(long-term asset) due to its physical absence like other long-term assets.


    Modern rule of accounting:

    as per the Modern rule of accounting, all Assets or all possessions of a business are comes under the head Asset accounts.

    as Goodwill is treated as an Intangible asset it is an Asset Account.


    Journal entry for purchase of goodwill as per Modern rule

    Goodwill A/c Dr. – Amt

    To Cash/Bank A/c – Amt

    (The modern approach of accounting for the Asset account is: “Debit the increase in asset and Credit the decrease in the asset“)


    The golden rule of accounting

    As per the golden rule of accounting, all assets or possessions of a business other than those which are related to any person (debtor’s account) are considered Real accounts.

    Such accounts don’t close by the year-end and are carried forward.

    As Goodwill is an Intangible asset it is treated as a Real account as per the golden rule of accounting.


    Journal entry for purchase of goodwill as per Golden rule

    Goodwill A/c Dr. – Amt

    To Cash/Bank A/c – Amt

    (The golden rule of accounting for the Real account is: “Debit what comes in and Credit what Goes out“)

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

A ledger account is prepared from?

A. Events B. Transactions C. Journals D. None of These

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 14, 2021 at 5:38 pm
    This answer was edited.

    The correct option is Option C: Journal Entries. Journal entries are the primary entries in the books of accounts and they are passed when any transaction or event takes place. Every journal entry has a dual effect i.e. two or more accounts are affected. For example, When cash is introduced in the bRead more

    The correct option is Option C: Journal Entries.

    Journal entries are the primary entries in the books of accounts and they are passed when any transaction or event takes place. Every journal entry has a dual effect i.e. two or more accounts are affected.

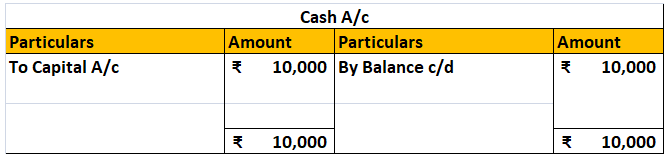
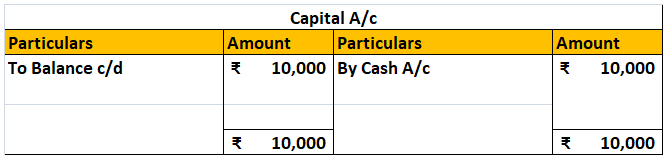
    For example, When cash is introduced in the business, the journal entry passed is:

    Cash A/c    Dr.      ₹10,000

    To Capital A/c  ₹10,000

    The accounts affected here are Cash A/c and Capital A/c.

    Cash A/c gets debited by ₹10,000,

    and Capital A/c get credited by ₹10,000.

    All the processes of accounting are conducted in an ordered manner known as the accounting cycle.

    The first step in an accounting cycle is to identify the transactions and events which are monetary in nature.

    The second step is to record the identified transactions in form of journal entries.

    And the third step is to make postings in the general ledger accounts as per the journal entries.

    Hence, the preparation of the ledger is the third step in the accounting cycle and is prepared from the journal entries.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Accounting Terms & Basics

What is accumulated profit meaning?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on November 20, 2021 at 8:43 pm

    Accumulated profit is the amount of profit left after the payment of dividends to the shareholders. It is also known as retained earnings. It is the profit that is not distributed as dividends to shareholders, hence called retained earnings. This accumulated profit is an important source of internalRead more

    Accumulated profit is the amount of profit left after the payment of dividends to the shareholders. It is also known as retained earnings. It is the profit that is not distributed as dividends to shareholders, hence called retained earnings. This accumulated profit is an important source of internal finance for a company. Accumulated profit or retained earnings can be ascertained using the following formula:

    Accumulated profit = Opening balance of accumulated profit + Net Profit/Loss (loss being in the negative figure) – Dividend paid

    Accumulated profit can be put to the following uses:

    • To reinvest into the business in form of capital assets or working capital.
    • To repay the debt of the company.
    • To pay dividends in future.
    • To set off the net loss made by the company.

    Accumulated profit and reserves are often considered the same. But in substance, they are not. The reserves are actually part of the accumulated profit, but the converse is not true. They are created by transferring amounts from the accumulated profit. While reserves are created for purpose of strengthening the financial foundation of a firm, the accumulated profit’s main purpose is to make reinvest in the business to increase its growth.

    The amount of accumulated profits depends upon the retention ratio and dividend payout ratio of a company.  The retention ratio is the opposite of the dividend payout ratio.

    The formula of dividend pay-out ratio = Dividend payable/Net Income

    And retention ratio = 1 – (Dividend payable/Net Income)

    If the retention ratio is more than the dividend payout ratio, the accumulated profit remains positive.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of “Contra” in accounting?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 25, 2021 at 4:25 pm
    This answer was edited.

    The term ‘contra’ means opposite or against. In financial accounting, we encounter the term ‘contra’ in: Contra accounts Contra entries The meaning of contra in the above mention terms is also the same as their general meaning. Contra accounts mean the account which is opposite of the account it corRead more

    The term ‘contra’ means opposite or against. In financial accounting, we encounter the term ‘contra’ in:

    • Contra accounts
    • Contra entries

    The meaning of contra in the above mention terms is also the same as their general meaning. Contra accounts mean the account which is opposite of the account it corresponds to.

    Contra entries are entries of the debit and credit aspects related to the same parent account.  Let’s discuss them in detail.

    Contra accounts

    Any account which is created with the purpose of reducing or offsetting the balance of another account is known as a contra account.

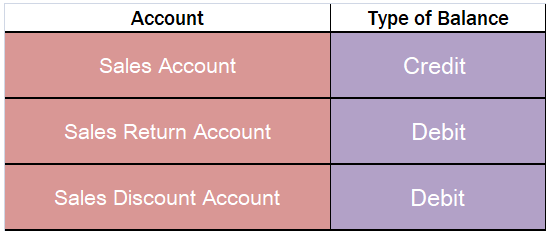
    A contra account is just the opposite of the account to which it relates. The most common examples are the sales discount account and sales return account which is the contra account of the sales account.  They are just the opposite of the sales accounts.

    Contra Entries

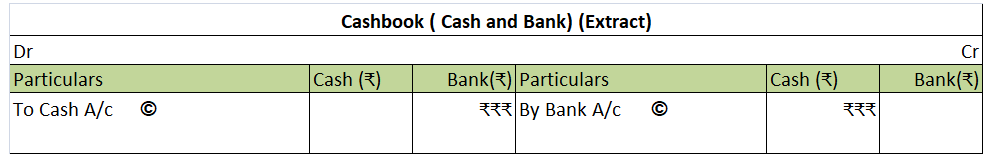
    Contra entries refer to the entries which show the movement of the amount within the same parent account. Here, the debit and credit entry is posted on the debit and credit side respectively of a single parent account.  Mainly, contra entries are the entries involving cash and bank accounts.

    The following transactions are recorded as contra entries:

    • Cash to Bank transactions: Deposit of cash into the bank account by the entity.
    • Bank to Cash transactions: Withdrawal of cash from the bank.
    • Cash to cash transactions: Transfer of cash to the petty cash account.
    • Bank to Bank transactions: Transfer of amounts from one bank account to other bank accounts of the same entity.

    Contra entries are marked by the letter ‘C’ beside the postings in the ledger. Deposit of cash in to bank will be posted in cashbook as below:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

What are biological assets? What is their accounting treatment?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 12, 2025 at 7:40 am

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture. IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity. Agricultural Activity- It is the management of biological transformatRead more

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture.

    IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity.

    • Agricultural Activity- It is the management of biological transformation by an entity and measuring the change in the quality and quantity of biological assets.
    • Biological Transformation- It comprises the process of growth, degeneration, production and procreation that cause qualitative or quantitative changes in a biological asset
    • Biological Asset – They are living plants or animals owned by an entity
    • Agricultural Produce- It is the harvested / detached product of the entity’s biological asset.

    IAS 41 does not apply to

    • Agricultural land
    • Intangible assets related to agricultural activity
    • Products that are the result of processing after the point of harvest, for example, yarn, carpet, rubber, wine, etc
    • The land on which the biological assets grow, regenerate, degenerate.


    Biological Assets

    Definition

    Biological assets are living plants or animals that go through biological transformation, owned by an entity to prepare agricultural produce for the purpose of agricultural activities only.

    Living plants include plants that are consumable within 1 year and are harvested. It also includes plants that are used for lumbering and wood-cutting activities.

    Examples

    Examples of biological assets are:

    Sheep, pigs, poultry, beef cattle, fish, dairy cows, plants for harvest etc

    Importance

    • Farming: They are key to agriculture and food production.
    • Income: They generate substantial income for businesses in industries such as vineyards, livestock, silviculture, etc.
    • Sustainability: Properly managing them helps the environment.


    Accounting & Presentation

    Recognition

    Under IAS 41 biological assets are recognised when

    • The business must have ownership over them from a past event.
    • The future economic benefits are expected to flow to the business from their ownership.
    • The cost or fair value of the asset can be measured reliably.

    Agricultural produce is recognised

    • It is recognised at the point of harvest or detachment.

    Agricultural produce is derecognised when

    • They enter the trading.
    • Enters the production process.

    Measurement

    • Biological assets are measured on initial recognition and at each balance sheet date at their fair value less costs to sell.
    • Costs to sell are incremental costs incurred in selling the asset.
    • Agricultural produce is measured at the point of harvest, at fair value less costs to sell at the point of harvest.
    • Agricultural produce after the point of harvest/ detachment is transferred and treated under the IAS 2 Inventory

    Gains & Losses

    • Gains and losses arising from the initial recognition of biological assets are reported in the statement of profit and loss.
    • The change in fair value less costs to sell of a biological asset between balance sheet dates is reported as gain or loss in the statement of profit and loss.
    • A gain or loss arising on initial recognition of agricultural produce at fair value less selling costs is included in profit or loss for the period in which it arises.

    Treatment

    • The sale of agricultural produce is treated as revenue in the statement of profit and loss.
    • Agricultural produce to be harvested for more than 12 months, livestock to be held for more than 12 months and trees cultivated for lumber are recorded as Biological assets under the Non-current assets head in the balance sheet.
    • Agricultural produce to be harvested within 12 months, livestock to be slaughtered within 12 months and annual crops like wheat, and maize are recorded as Biological assets under the head Current assets in the balance sheet.
    • Inventories produced from agricultural produce are presented as Inventory under the head Current assets in the balance sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is a contra revenue account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 7, 2021 at 7:55 pm
    This answer was edited.

    The term ‘contra’ means  'opposite'. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance. The purpose of the contra revenue account is to ascertain the actuaRead more

    The term ‘contra’ means  ‘opposite’. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance.

    The purpose of the contra revenue account is to ascertain the actual amount of sales and record the items which have reduced the sales.

    These are the contra revenue accounts commonly seen in businesses:

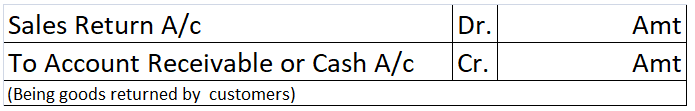
    • Sales return account: This account records the amount of goods sold returned by customers. The journal entry for recording sale return is as follow:

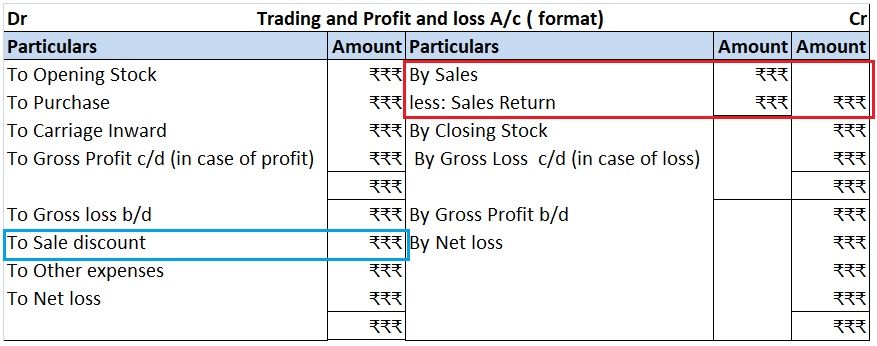
    The total sales return is deducted from the sales in the balance sheet. Though being opposite of the sales account, the sale return account is not an expense account. It is considered an indirect loss as it reduces sales.

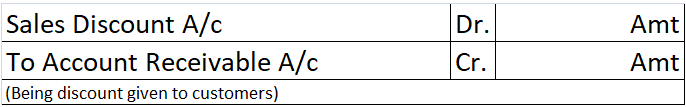
    • Sale Discount account: This account records the amount of discount allowed to customers. The journal entry for recording sale discounts is as follows:

    Sales discount is an expense hence it is debited to the profit and loss account.

    Sales returns and sales discounts are shown in the trading and profit and loss account in the following manner:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of sundry creditors?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on August 13, 2022 at 7:47 am
    This answer was edited.

    Meaning The term ‘Sundry creditors’ consist of two words:  ‘Sundry’ and ‘creditors’.  The word ‘sundry’ means the items which are not significant enough to be named separately. It also refers to a collection of miscellaneous items. Creditors are the person from whom money is borrowed or goods are puRead more

    Meaning

    The term ‘Sundry creditors’ consist of two words:  ‘Sundry’ and ‘creditors’. 

    The word ‘sundry’ means the items which are not significant enough to be named separately. It also refers to a collection of miscellaneous items.

    Creditors are the person from whom money is borrowed or goods are purchased on credit by a business or a non-business entity. They have to be repaid after a period of time which is usually less than or up to one year.

    By combining the meaning of both words, ’sundry’ and ‘creditor’, the term ‘sundry creditor’ will refer to the collection of insignificant creditors of an entity.

    Back in the days when accounting records were maintained on paper, only the records of those creditors were maintained separately, from whom goods are purchased regularly and in large amounts. 

    But there used to be numerous other creditors with whom the transactions were occasional and insignificant. To reduce the paperwork, records of all such creditors were maintained on a single page or book under the head ‘Sundry Creditors’

    Nowadays, as accounting records are maintained digitally, hence maintaining records of each and every creditor is not a problem. 

    Hence, every creditor whether small or big, is grouped under the head ‘Sundry creditor’ or ‘Trade Creditor’.


    Accounting Treatment 

    Sundry creditors are the persons to whom a business owes money. 

    Hence, as per golden rules of accounting, Sundry creditor is a personal account and the golden rule for personal account is, ‘Debit the receiver and credit the giver’ 

    We know sundry creditors are liabilities, hence, as per modern rule of accounting, sundry creditors are credited in case of increase and debited in case of decrease.

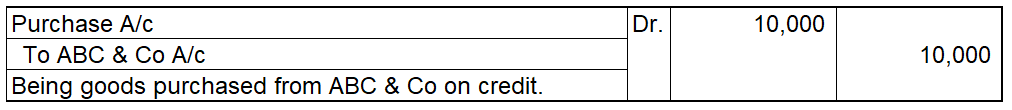
    Example, a business purchased goods for Rs. 10,000 from ABC & Co. The journal entry will as follows:

    Here, ABC & Co is the creditor. It is credited as it is a personal account and the creditor has given the goods to the business, hence the giver is credited.

    From point of view of modern rules of accounting, ABC & Co. is a creditor, a liability. On purchase of goods on credit, a liability is created. Hence, ABC & Co A/c is credited.


    Balance sheet

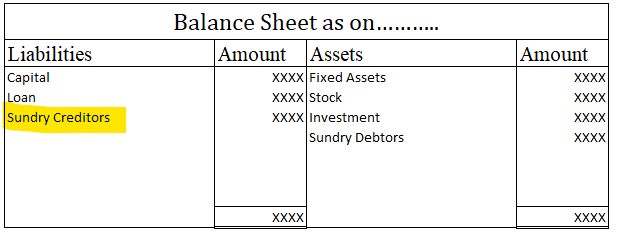
    Sundry creditor is a current liability, so it is shown on the liabilities side of a balance sheet. Trade payable and accounts payable mean sundry creditors only.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is a valuation account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on January 11, 2022 at 7:07 pm
    This answer was edited.

    Meaning A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value. The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the mainRead more

    Meaning

    A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value.

    The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the main ledger account.  This is a conservative approach to use valuation accounts to present the value of the concerned asset or liability at a reduced value.

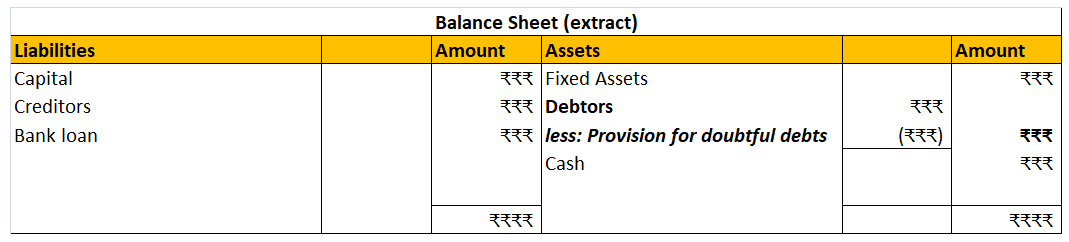
    The most common example of a valuation account is the ‘Provision for doubtful debts account’. It appears in the balance sheet as a reduction from the debtors’ accounts. Also when the amount is transferred to this provision, it appears in the statement of profit and loss account. But it doesn’t appear in the debtors’ account ledger.

    Treatment

    A valuation account appears only in the balance sheet. Sometimes, it also appears in the profit and loss account when any amount is transferred to it.

    Valuation accounts are only used in accrual accounting. They cannot be used in cash-based accounting as there is no flow of cash related to valuation accounts.

    They have a balance opposite of their paired accounts i.e. if their paired account is an asset then they will have a credit balance and if it is a liability then they will have a debit balance.

    Other Examples of valuation accounts are as follows:

    1. Provision for doubtful debts (offsets the account receivables or debtors’ account)
    2. Accumulated depreciation (report the assets net of depreciation)
    3. Discount on bonds payable (reduces the reporting balance of bond payable account)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.