

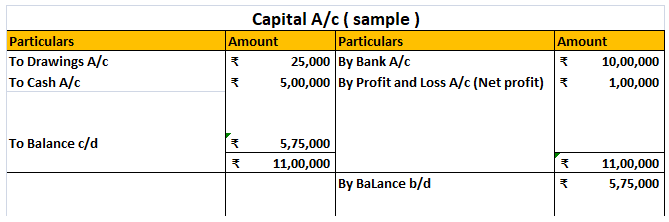
A Capital Account is an account that shows the owner's equity in the firm and a Partner's Capital Account is an account that shows the partner's equity in a partnership firm. Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are: CapitalRead more
A Capital Account is an account that shows the owner’s equity in the firm and a Partner’s Capital Account is an account that shows the partner’s equity in a partnership firm.
Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are:
- Capital introduced in the firm
- Capital withdrawn
- Interest on Capital
- Interest on Drawings
- Profit or loss in the financial year, etc.
When partners are given interest on their capital contribution in the firm, it is called on Interest on Capital.
In case the partnership firm does not have a Partnership Deed, the Partnership Act does not include a provision for Interest on Capital. However, if the partners want they can mutually decide the rate of Interest on Capital.
Interest on Capital is calculated on the opening capital of the partners and is only allowed when the firm makes a profit, that is, in case a firm incurs losses, it cannot allow Interest on Capital to its partners.
Example:
In a partnership firm, there are two partners A and B, and their capital contribution is Rs 10,000 and 20,000 respectively. Interest on capital is @ 10% p.a. The Interest on Capital for both the partners is:
Partner A- 10,000 * 10/100 = 1,000
Partner B- 20,000 * 10/100 = 2,000
The journal entry for Interest on Capital is an adjusting entry and is shown as:
| Interest on Capital A/c Dr. | 3,000 | |
| To A’s Capital a/c | 1,000 | |
| To B’s Capital A/c | 2,000 |
- Partner’s Capital Account is credited because it is credit in nature and interest on capital is an addition to the account.
- Interest on Capital Account is debited because it is an expense account.
See less









Fictitious assets On seeing or hearing ‘fictitious’, the words which come to our mind are ‘not true, ‘fake’ or ‘fantasy’. So, fictitious assets are those items that appear on the assets side of the balance sheet but are actually not assets. In substance, fictitious assets are the expenses and lossesRead more
Fictitious assets
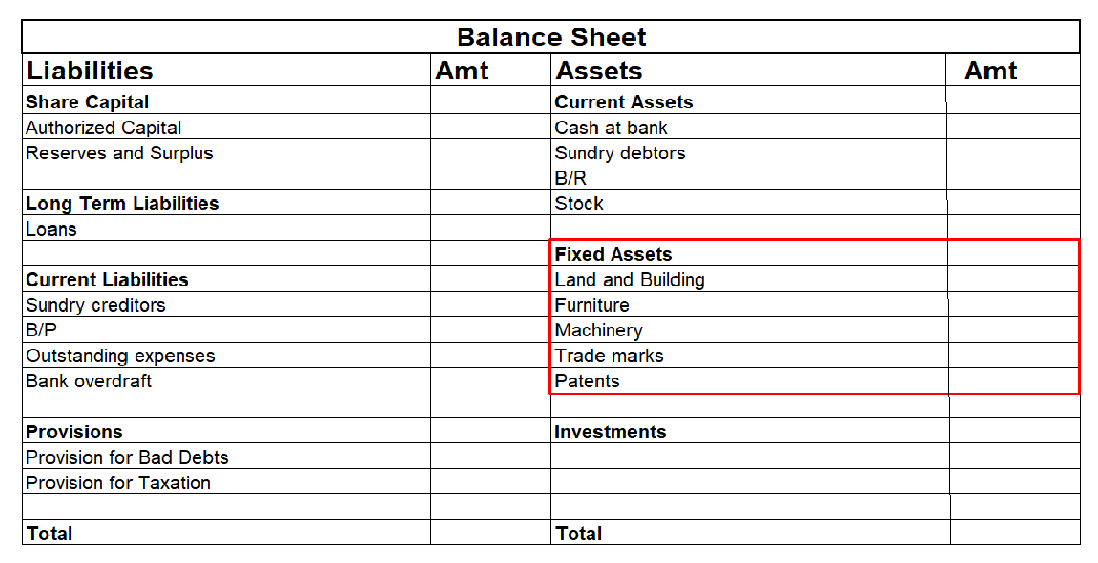
On seeing or hearing ‘fictitious’, the words which come to our mind are ‘not true, ‘fake’ or ‘fantasy’. So, fictitious assets are those items that appear on the assets side of the balance sheet but are actually not assets.
In substance, fictitious assets are the expenses and losses that are not completely written off in a financial year and are required to be carried forward to the next financial year.
The examples of fictitious assets are as follows:
Fictitious assets appear on the asset side of the balance sheet as expenses and losses have a debit balance.
*when the balance sheet is prepared as per Schedule III of Companies Act, the Net loss is shown as a negative figure under the head Reserve and Surplus.
Intangible Assets
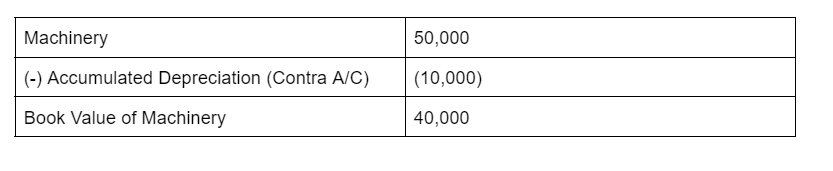
Intangible assets mean the assets which don’t have any physical existence. They cannot be seen or touched but are assets because they do provide future economic benefits to the business. Like tangible assets (like machinery and building), they can be also created, purchased or sold.
Like tangible assets are depreciated, intangible assets are gradually written over by amortization over their useful lifespan to account for the economic benefits provided by them.
Following are the examples of intangible assets:
Intangible assets which are created by the business-like goodwill or brand recognition do not appear in the balance sheet.
Only acquired intangible assets can be shown in the balance sheet. Like purchased goodwill, patents, trademarks etc.
Intangible assets also face impairment if their fair value is less than their carrying value after deducting amortization expense. The difference between carrying value and fair value is shown in the Profit and loss A/c as impairment charge and the asset is valued at fair value in the balance sheet.
See less