

A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnershiRead more
A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnership where the horizontal format is used.
COMPONENTS OF A BALANCE SHEET
The three main components of a balance sheet are Assets, Liabilities and Shareholders’ equity.
- Assets: They are divided into two main categories that are current assets and non-current assets. If an asset is expected to be realised within 12 months or is primarily held for being traded, or is cash or cash equivalent, then those assets are termed as current assets. All assets that are not current assets are grouped under non-current assets. They are normally realised after 12 months.
- Liabilities: They are categorised as current liabilities and non-current liabilities. If the amount owed by the company to an outside party is due to be settled in 12 months, then it can be termed as a current liability. The rest of the liabilities are referred to as non-current liability.
- Shareholders’ Equity: This is the money owed to the owners of the company, that is shareholders. It is also called net assets since it is equal to the difference between total assets and total liabilities. Their main categories are Shareholders’ Capital and Reserves and Surplus.
FORMAT OF BALANCE SHEET
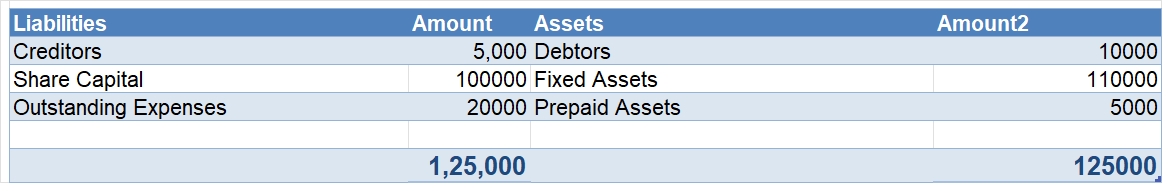
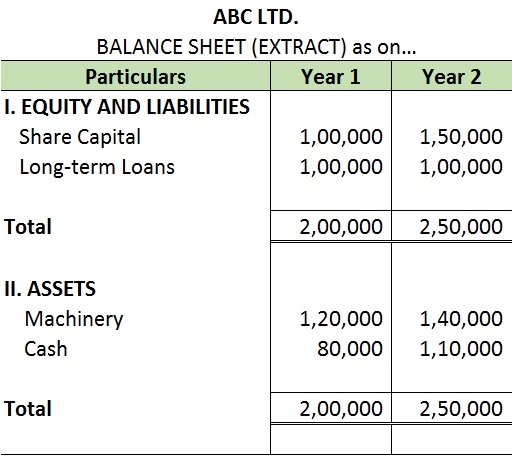
As per the Companies Act 2013, the following format should be used for preparing a balance sheet.
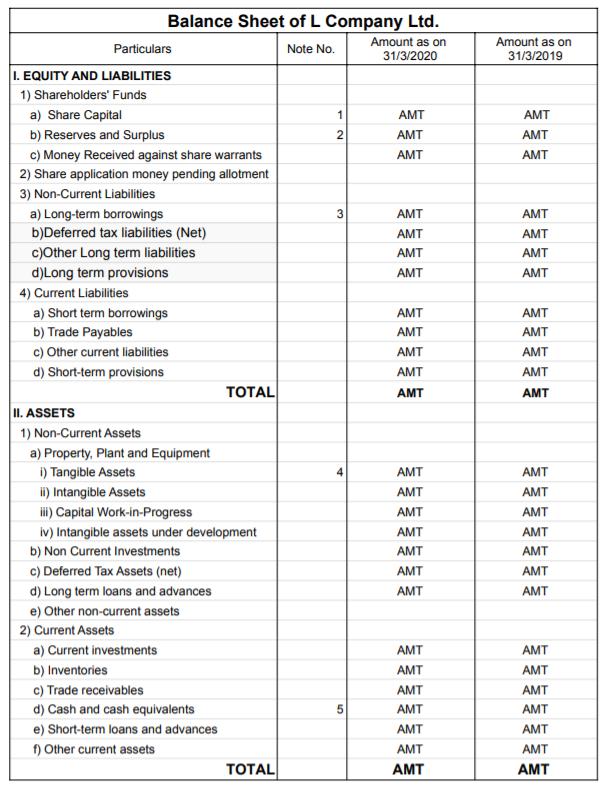
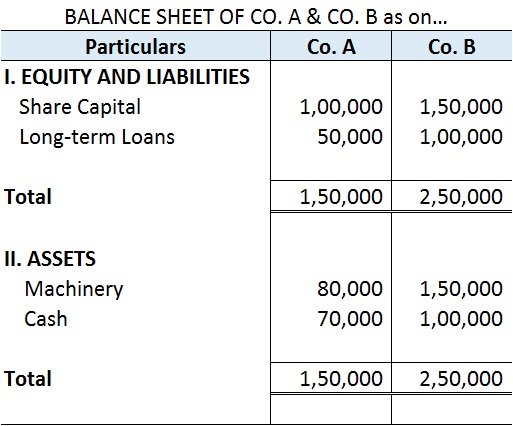
From the above Balance sheet, we should get:
Assets = Liabilities + Shareholders’ Equity
Relevant notes for each component should also be prepared when necessary.
See less










Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders. Therefore the cost of retained earnings is similar to theRead more
Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders.
Therefore the cost of retained earnings is similar to the cost of equity without tax and flotation cost. Hence, it can be calculated as
Kr = Ke (1 – t) (1 – f),
Kr = Cost of retained earnings
Ke = Cost of equity
t = tax rate
f = flotation cost
Here, flotation cost means the cost of issuing shares.
EXAMPLE
If cost of equity of a company was 10%, tax rate was 30% and flotation cost was 5%, then
cost of retained earnings = 10% x (1 – 0.30)(1 – 0.05) = 6.65%.
From the above example and formula, it is clear that the cost of retained earnings would always be less than or equal to the cost of equity since retained earnings do not involve flotation costs or tax.
A company usually acquires funds from various sources of finance rather than a single source. Therefore the cost of capital of the company will be the weighted average cost of capital (WACC) of each individual source of finance. The cost of retained earnings is thus an important factor in calculating the overall cost of capital.
Another important factor of WACC is the cost of equity. The cost of equity is sometimes interchanged with the cost of retained earnings. However, they are not the same.
See less