

To begin with, let me first give you a small explanation of what Contingent assets are A contingent asset is a potential asset or economic benefit that does not exist currently but may arise in the near future. Such an asset arises from an uncertain and unpredictable event. To make it clear with anRead more
To begin with, let me first give you a small explanation of what Contingent assets are
A contingent asset is a potential asset or economic benefit that does not exist currently but may arise in the near future. Such an asset arises from an uncertain and unpredictable event.
To make it clear with an example: String Co. filed a lawsuit against a competitor company Weave Tech Co. for infringing on company ABC’s patent. Even if it is probable (but not certain) that Strings Co. will win the lawsuit, it is a contingent asset.
As such, it will not be recorded in Strings Co. general ledger accounts until the lawsuit is settled.
At most the Strings Co. can do is, prepare a note disclosing the fact that it has filed the lawsuit the outcome of which is uncertain.
Disclosing Contingent Assets
- The probability of occurrence is virtually certain or probable: It will be disclosed as an asset in the balance sheet.
For Example, The court orders for reimbursement to Strings Co. say 1,00,000 for the damages, but it has not yet received the money. Although it is virtually certain that the company will receive the money in the near future, it will be treated as an asset and can be disclosed in the balance sheet on the assets side.
- The probability of occurrence is probable: It will be disclosed as notes to accounts below the balance sheet.
For Example, Strings Co. filed a lawsuit against a competitor company Weave Tech for infringing on Strings Co. patent. Even if it is probable (but not certain) that Strings Co. will win the lawsuit, it is a contingent asset.
As such, it will not be recorded in Strings company’s general ledger until the lawsuit is settled.
At most the Strings Co. can do is, prepare a note disclosing the fact that it has filed the lawsuit the outcome of which is uncertain.
- The probability of occurrence is remote or not probable: It will not be treated as a contingent asset.
In this case, the disclosure of it is not permitted.
See less






Deferred Tax Liability A deferred tax liability represents an obligation to pay taxes in the future. These taxes are owed by a company but are not due to be paid until a future date. Companies that incur such an obligation prepare and maintain two financial reports every year: a tax statement and anRead more
Deferred Tax Liability
A deferred tax liability represents an obligation to pay taxes in the future. These taxes are owed by a company but are not due to be paid until a future date.
Companies that incur such an obligation prepare and maintain two financial reports every year: a tax statement and an income statement.
This is because companies maintain their books as per book accounting rules (GAAP/IFRS), but they have to pay taxes according to tax accounting rules, and they each have to follow their own guidelines.
For example, a tax statement follows the cash basis of accounting, and an income statement follows the accrual basis of accounting.
Companies calculate their profit as per the accounting rules as well as tax laws known as accounting income and taxable income, respectively. Some differences arise due to the application of different provisions of law.
These temporary differences are accounted for, recognized, and carried forward in the books of accounts and create deferred tax.
Example
Here is an example of deferred tax liability.
In the given example, tax as per income statement is 70,000, whereas as per tax statement it is 56,000. This temporary difference is termed as deferred tax liability of 14,000.
When accounting income is more than taxable income, it creates Deferred Tax Liability. It will be adjusted in the books of accounts during one or more subsequent year(s).
How Does it Arise?
There are several instances under which a company creates a deferred tax liability. Some other instances are:
Depreciation Methods
Treatment of Revenue & Expenses
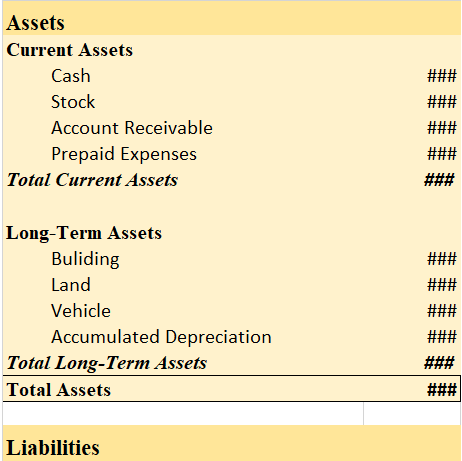
Impact on Financial Statements
Recognising deferred tax liability and its subsequent effect on the company’s financial statement is important as it simplifies the process of auditing and analysing financial reports.
Balance Sheet
Cash Flow Statement
- The deferred tax liability is added back to the net income in calculating cash flow from operating activities to show the actual cash flow.
See less