Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Aadil
AadilCurious
In: 1. Financial Accounting > Depreciation & Amortization

What is a provision for depreciation account?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 4, 2021 at 7:46 pm
    This answer was edited.

    You must have knowledge of what depreciation is. Depreciation is the process of allocating the value of an asset over its useful life. It reduces the carrying value of the asset year by year till it is scraped. It is an expense (expense of using the asset for business purposes) and it is charged toRead more

    You must have knowledge of what depreciation is. Depreciation is the process of allocating the value of an asset over its useful life. It reduces the carrying value of the asset year by year till it is scraped.

    It is an expense (expense of using the asset for business purposes) and it is charged to profit and loss account.

    Depreciation can be reported in the financial statement in two ways:

    1. Deduct depreciation from the asset account and show the asset at “depreciation less” value. See the journal entries below:

    1. Maintain a provision for depreciation account and show the asset account at original cost. In this method, no entry is passed through the asset account. See the journal entries below:


    Provision for depreciation account represents the collection of total depreciation till date on an asset. That’s why it is also called accumulated depreciation account. When an asset is sold, its accumulated depreciation is credited to the asset account. See the journal entry below:

    It is shown on the liabilities side of the balance sheet. It is a nominal account because it is shown as an expense in the statement of profit or loss.

    In case provision for depreciation account is not maintained then the balance sheet looks like this:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Financial Statements

What is the primary objective of cash flow statement?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on December 1, 2021 at 2:09 pm
    This answer was edited.

    A cash flow statement is a statement showing the inflow and outflow of cash and cash equivalents during a financial year. Cash Flow Statements along with Income statements and Balance Sheet are the most important financial statements for a company. The Cash Flow Statement provides a picture to the sRead more

    A cash flow statement is a statement showing the inflow and outflow of cash and cash equivalents during a financial year. Cash Flow Statements along with Income statements and Balance Sheet are the most important financial statements for a company.

    The Cash Flow Statement provides a picture to the shareholders, government, and the public of how the company manages its obligations and fund its operations. It is a crucial measure to determine the financial health of a company.

    The Cash Flow Statement is created from the Income Statement and the Balance Sheet. While Income Statement shows money engaged in various transactions during the year, the Balance Sheet presents information about the opening and closing balances.

    The primary objective of a Cash Flow Statement is to present a record of inflow and outflow of cash, cash equivalents, and marketable securities through various activities of a company.

    Various activities in a company can be broadly classified into three parts or heads:

    • Cash Flow from Operating Activities: it represents how money from regular business activities is derived and spent. It includes Net Profit from Income Statement after adjusting for tax and extra-ordinary activities. Items included in Operating Activities are adjustments in Working Capital. If current liabilities are paid or current assets are bought it means outflow of cash, hence it is deducted and if liabilities are increased or assets are sold it means the inflow of cash, hence it is added. Operating Activities take into account taxation, dividend, depreciation, and other adjustments.
    • Cash Flow from Investing Activities: it represents aggregate inflow or outflow of cash due to various investments activities that the company was engaged in. Purchase and sale of non-current assets like fixed assets and long-term investments are considered under this head. If there is an investment made, it means outflow of cash, hence it is deducted and if there is an investment sold it means the inflow of cash, and hence it is added.
    • Cash Flow from Financing Activities: it represents the activities that are used to finance a company’s operations, like, issue of cash or debentures, paying dividends and interest, long-term borrowing taken by a company, etc. If these are paid, it means outflow of cash and is hence deducted and if they are acquired, it means the inflow of cash and hence ae added.

    Cash Flow Statements also present a picture of the liquidity of the company and are therefore used by the management of a company to take decisions with the help of the right information.

    Cash Flow Statements are a great source of comparison between a company’s last year’s performance to its current year or with other companies in the same industry and hence, helps shareholders and potential investors to make the right decisions.

    It also helps to differentiate between non-cash and cash items; incomes and expenditures are divided into separate heads.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation in spirit is similar to?

Depletion Amortization Depression

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 20, 2021 at 2:51 pm
    This answer was edited.

    The correct option is 2. Amortization. Depreciation in spirit is similar to Amortization because both depreciation and amortization have the same characteristics except that depreciation is used for tangible assets and amortization for intangible assets. To make it clear, intangible assets are thoseRead more

    The correct option is 2. Amortization.

    Depreciation in spirit is similar to Amortization because both depreciation and amortization have the same characteristics except that depreciation is used for tangible assets and amortization for intangible assets.

    To make it clear, intangible assets are those assets that cannot be touched i.e. they are not physically present. For example, goodwill, patent, trademark, etc. Hence, these assets are amortized over their useful life and not depreciated.

    Example for Amortizing intangible assets: A manufacturing company buys a patent for Rs 80,000 for 8 years. Assuming that the residual value of the patent after 8 years to be zero.

    The depreciation to be written off will be

    Yearly Depreciation = Cost of the patent – Residual value / Expected life of the asset.

    = 80,000 – 0 / 8

    = Rs 10,000 every year.

    Whereas, tangible assets are those assets that can be touched i.e. they are physically present. For example, building, plant & machinery, furniture, etc. Hence, these assets are depreciated over their useful life and not amortized.

    Example of Depreciating tangible asset:  A manufacturing company bought machinery for Rs 8,10,000 and its estimated life is 8 years, scrap value being Rs 10,000.

    The depreciation to be written off will be

    Yearly Depreciation = Cost of machinery – Scrap value / Expected life of the asset.

    = 8,10,000 – 10,000 / 8

    = 8,00,000 / 8

    = Rs 1,00,000 every year.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation on car as per income tax act?

  • 1 Answer
  • 0 Followers
Answer
  1. Radha M.Com, NET
    Added an answer on July 22, 2021 at 5:48 pm
    This answer was edited.

    The rate of depreciation on a car as per the Income Tax Act depends upon the purpose for which it has been purchased and the year on which it was acquired. As per the Income Tax Act, cars come under the Plant and Machinery block of assets. The Act classifies cars into two categories, Group 1 - MotorRead more

    The rate of depreciation on a car as per the Income Tax Act depends upon the purpose for which it has been purchased and the year on which it was acquired.

    As per the Income Tax Act, cars come under the Plant and Machinery block of assets.

    The Act classifies cars into two categories,

    • Group 1 – Motor cars other than those used in the business of running them on hire.
    • Group 2 – Motor taxis used in the business of running them on hire.


    Group 1:

    1. If the motor car is acquired and put to use on or after 23rd August 2019 but before 1st April 2020, then the rate applicable is 30%.
    2. If the motor car is acquired and put to use on or after 1st April 1990, then the rate applicable is 15%. (All the cars which are not covered under the category (1) comes under this category.)


    Group 2:

    1. If the motor taxi is acquired and put to use on or after 23rd August 2019 but before 1st April 2020, then the rate applicable is 45%.
    2. The rate applicable for motor taxis not covered under category (1) is 30%.


    Here is a summarised version of the rates applicable to cars,


    The rates can also be found on the Income Tax India website.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Ledger & Trial Balance

What is the difference between ledger and trial balance?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on August 21, 2021 at 7:04 am
    This answer was edited.

    The difference between a ledger & a trial balance is as follows: Basis Ledger Trial Balance Meaning Ledger is a book/register in which all the accounts are put together. A Trial Balance is a statement showing the debit and credit balance of all the accounts to ascertain the arithmetical accuracyRead more

    The difference between a ledger & a trial balance is as follows:

    Basis Ledger Trial Balance
    Meaning Ledger is a book/register in which all the accounts are put together. A Trial Balance is a statement showing the debit and credit balance of all the accounts to ascertain the arithmetical accuracy of the books of accounts.
    Basis of preparation Journal is the basis for recording transactions in the ledger. The closing balances of different accounts in the ledger are the basis for preparing the trial balance.
    Objective It is prepared to see the net effect of various transactions affecting a particular account. It is prepared to check the arithmetical accuracy of the books of accounts.
    Format A ledger has four identical columns on the debit and credit sides: 1. Date, 2. Particulars, 3. Journal Folio, 4. Amount. A Trial Balance has five columns: 1. S.No, 2. Name of Accounts, 3. Ledger Folio, 4. Debit Balance, 5. Credit Balance.
    Stage of Recording A ledger is prepared after recording the transactions in the journal. A trial balance is prepared after posting the transactions in the ledger.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Miscellaneous

Give any three examples of revenue?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on July 9, 2021 at 3:35 am
    This answer was edited.

    Revenue also called income is nothing but the income generated by individuals or businesses from the sale of goods or investing capital or assets. Some examples of revenue are as follows:- Sales revenue Dividend received Interest earned Rent received Commission    1. SALES REVENUE Sales revenueRead more

    Revenue also called income is nothing but the income generated by individuals or businesses from the sale of goods or investing capital or assets. Some examples of revenue are as follows:-

    1. Sales revenue
    2. Dividend received
    3. Interest earned
    4. Rent received
    5. Commission


     1. SALES REVENUE

    Sales revenue is the income received by the individual or business by selling its product or provision of services. the words “sale” and “revenue” are used interchangeably to mean the same thing. It is to be noted that revenue does not necessarily mean it has been received in cash, it can be partly in cash or partly on credit also.

    How to calculate sales revenue?

    SALES REVENUE = NO. OF UNITS SOLD * AVERAGE PRICE PER UNIT

    For example:- Amazon sold 4000 units of shirts @ 500 each. Therefore sales revenue for amazon is

    Sales revenue = 4000 * 500

    = 20,00,000

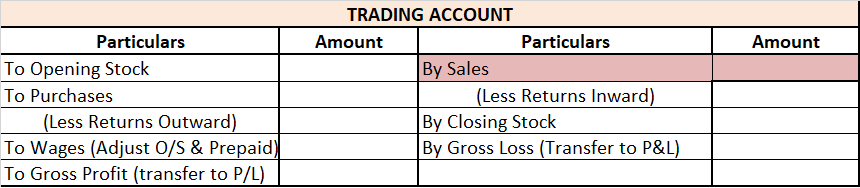
    Treatment of sales revenue in the financial statement, since sales are part of a trading account and appear on the credit side of the trading account.

    2. DIVIDEND RECEIVED

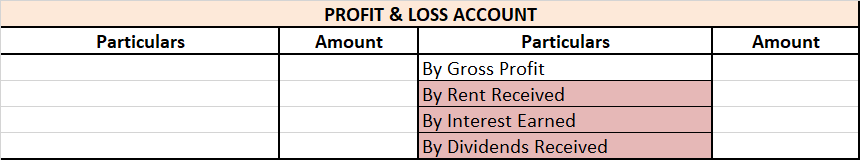
    Naina, this can be explained in simple terms. Suppose you own shares of a company which declares dividend so the dividend received is income for you. Since it does not reduce the assets of a company nor creates a liability it is shown as income and posted on the credit side of profit & loss A/c.

    Let me give you a short example of a dividend received, suppose you own 1000 shares of ABC.ltd. the company at the quarter-end calculate its earnings and decides to declare a dividend of Rs 5 per share. Therefore you would receive 1000* 5 i.e Rs 5000 as dividend income.

    3. INTEREST INCOME EARNED

    Interest income is the earnings the entity receives on any investments made. To be more precise it is money earned by an individual or business for lending their fund either by putting them as deposit in the bank. It is shown on the credit side of the profit & loss A/c.

    A very simple example for interest earned is when a business or an individual deposits money in the bank as savings and decided not to touch it for the coming years then such a depositor will gain interest on such savings by the bank. such type of income so received is treated as interest received and shown as income in the profit & loss A/c.

    3. RENT RECEIVED

    When money is received by the business for exchange of use of assets of the business by the other person, then it will be called rent received. Rent can be received by the business firm in respect of land, building, machinery, etc. As rent received is income for the business firm, it is shown on the credit side of profit & loss A/c.

    For example, X. ltd received Rs 20,000 via cash on one of its properties to Mr. Z. Then rent so received shall be treated as income in the books of ABC. ltd and same shall be treated as income and shown in the profit & loss statement.

    Summarised extract of profit & loss account is shown below for dividend received, Rent received and interest earned.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 1. Financial Accounting > Miscellaneous

Is building a current asset?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 16, 2022 at 9:07 pm
    This answer was edited.

    No, the building is not a current asset. Explanation Current assets are those in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting through normal day-to-day business operations. Examples: Cash and cash equivalent, stock, liquid assets, etRead more

    No, the building is not a current asset.

    Explanation

    Current assets are those in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting through normal day-to-day business operations.

    Examples: Cash and cash equivalent, stock, liquid assets, etc.

    The building is expected to have a valuable life for more than a year and is bought for a longer term by a company. The building is a fixed asset/non-current asset, those assets which are bought by the company for a long term and aren’t supposed to be consumed within just one accounting year.

    In order to understand it more clearly, let’s see the two types of assets in the classification of the assets on the basis of convertibility:

    In the classification of the assets on the basis of their convertibility, they are classified either as current assets or fixed assets. Also referred to as current assets/ non-current assets or short-term/ long-term assets.

    • Current Assets – As explained above, those assets in a business that is reasonably expected to be sold, consumed, cashed, or exhausted within one year of accounting.
    • Fixed Assets – Those assets which are not likely to be converted into cash quickly and are bought by the business for a long term.

    Building in the balance sheet

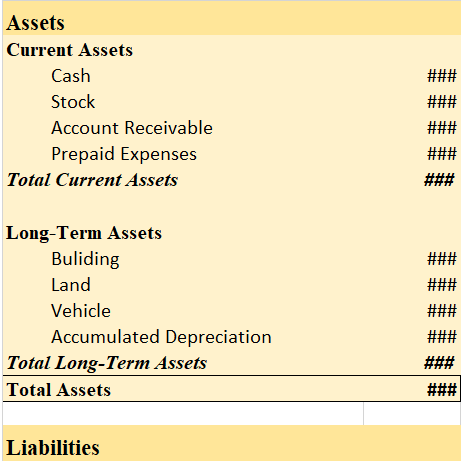
    Let us take a look at the balance sheet’s asset side and see where building and current assets are shown

    Balance Sheet (for the year ending…)


    As we can see, the building is shown on the long-term assets side and not in the current assets.

    Therefore, the building is not a current asset.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Subsidiary Books

What is sales return book format?

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on December 4, 2021 at 1:02 pm

    In accounting, sales returns are the goods returned by the customer to the seller. This can be due to goods delivered is damaged or defective. A return can also be due to late delivery, or the wrong items being sent to the buyer. Sales return is a subsidiary book in which all the details are recordeRead more

    In accounting, sales returns are the goods returned by the customer to the seller. This can be due to goods delivered is damaged or defective. A return can also be due to late delivery, or the wrong items being sent to the buyer.

    Sales return is a subsidiary book in which all the details are recorded for the goods returned which were sold on credit. It is also known as return inwards.

    Accounting for Sales Return

    Whenever there is a sale return, the seller will debit the sales return account and credit the debtor’s account. The total amount of sales returns is deducted from the gross sales for the period giving the figure for net sales. Debtor’s account is credited because the amount receivable from debtors will reduce.

    The sales return is a contra account to the sales.

    Format of sales return book:

    In the above format, a credit note is a statement prepared by the seller and sent to the buyer. In this statement, all the details are mentioned in respect of the goods sent by the buyer and are an indication that the buyer’s account is credited in respect of the goods received.

    For example, Mr. A sold goods to Mr. B costing Rs 50,000 on 1 December. On 5 December, goods amounting to Rs 15,000 were found defective and were returned immediately to Mr. A.

    Mr. A will account for this in the following way:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

what does a trial balance include?

  • 1 Answer
  • 4 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 14, 2023 at 2:55 am
    This answer was edited.

    Definition The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances. A trial balance is prepared on a particular date and not on a particular period. What does trial balRead more

    Definition

    The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances.

    A trial balance is prepared on a particular date and not on a particular period.

    What does trial balance include?

    As in each double-entry system, each account has two aspects debit and credit.

    Hence the following trial balance includes:
    • Debit or credit of the reporting period.
    • The amount which is to be debited or credited to each account.
    • The account numbers.
    • The dates of the reporting period.
    • The totaled sums of debits and credits entered during that time.

    When we prepare a trial balance from the given list of ledger balances, these need to be included which are as follows :

    The balance of all
    • Assets accounts
    • Expenses accounts
    • Losses
    • Drawings
    • Cash and bank balances
    Are placed in the debit column of the trial balance.

    • The balances of
    • liabilities accounts
    • income accounts
    • profits
    • capital
    Are placed in the credit column of the trial balance.

    Importance

    As the trial balance is prepared at the end of the year so it is important for the preparation of financial statements like balance sheets or profit and loss.

    The purpose of the trial balance is as follows:

    • To verify the arithmetical accuracy of the ledger accounts
    This means trial balance indicates that equal debits and credits have been recorded in the ledger accounts.
    It enables one to establish whether the posting and other accounting processes have been carried out without any arithmetical errors.

    • To help in locating errors
    There can be some errors if the trial balance is untallied therefore to get error-free financial statements trial balance is prepared.

    • To facilitate the preparation of financial statements
    A trial balance helps us to directly prepare the financial statements and then which gives us the right to not look or no need to refer to the ledger accounts.

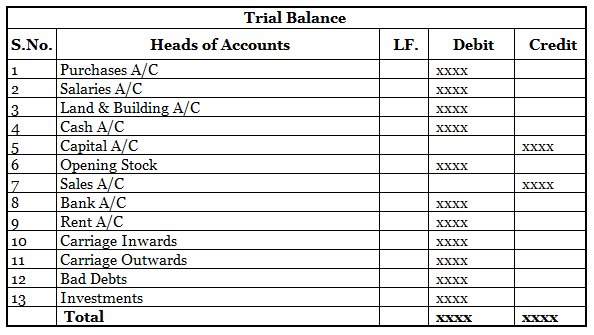
    Structure of trial balance

    See less
    • 10
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Miscellaneous

What is the meaning of negative working capital?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 8, 2021 at 6:26 pm
    This answer was edited.

    Negative working capital means the excess of current liabilities over current assets in an enterprise. Let’s understand what working capital is to get more clarity about negative working capital. Meaning of Working Capital Working Capital refers to the difference between current assets and current lRead more

    Negative working capital means the excess of current liabilities over current assets in an enterprise.

    Let’s understand what working capital is to get more clarity about negative working capital.

    Meaning of Working Capital

    Working Capital refers to the difference between current assets and current liabilities of a business.

    Working Capital = Current Assets – Current Liabilities

    It is the capital that an enterprise employs to run its daily operations. It indicates the short term liquidity or the capacity to pay off the current liabilities and pay for the daily operations.

    Items under Current Assets and Current Liabilities

    It is important to know about the items under current assets and current liabilities to understand the significance of working capital.

    Current assets include cash and bank balance, accounts receivables, inventories, short term investments, prepaid expenses etc.

    Current liabilities include accounts payable, short term loans, bank overdraft, interest on short term investment, outstanding salaries and wages etc.

    Types of working capital

    Since the working capital is just the difference between current assets and liabilities, the working capital can be one of the following:

    • Positive (Current assets > Current liabilities)
    • Zero  (Current assets = Current liabilities)
    • Negative (Current assets < Current liabilities)

    Hence, negative working capital exists when current liabilities are more than current assets.

    Implications of having negative working capital

    Having negative working capital is not an ideal situation for an enterprise. Having negative working capital indicates that the enterprise is not in a position to pay off its current liabilities and there may be a cash crunch in the business.

    An enterprise may have to finance its working capital requirements through long term finance sources if its working capital remains negative for quite a long time.

    The ideal situation is to have current assets two times the current liabilities to maintain a good short term liquidity of the business i.e.

    Current Assets  = 2(Current Liabilities)

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.