Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Rahul_Jose
Rahul_Jose
In: 1. Financial Accounting > Miscellaneous

What is the difference between bad debts and provision for doubtful debts ?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on December 29, 2021 at 9:10 am

    Any person, company, or organization that owes us money is a debtor. The amount that is owed to us is called debt. When you are unsure if a debtor is going to pay back the amount owed to you, then a provision for doubtful debts is created. Here, the debtor may or may not pay back the amount owed. WhRead more

    Any person, company, or organization that owes us money is a debtor. The amount that is owed to us is called debt. When you are unsure if a debtor is going to pay back the amount owed to you, then a provision for doubtful debts is created. Here, the debtor may or may not pay back the amount owed. When the debts owed to us is irrecoverable, it is termed as bad debts.

    Provision for doubtful debts may become a bad debt at some point. Usually, companies keep a small portion of their debtors as a provision for doubtful debts in accordance with the prudence concept that tells us to account for all possible losses. Provision for doubtful debts is a liability whereas bad debts are recorded as an expense.

    Journal entries for Doubtful debts and bad debts are as follows:

    EXAMPLE

    If the balance in the debtors’ account shows an amount of Rs 20,000 and 5% of debtors are treated as doubtful, then Rs 1,000 is recorded as a provision for doubtful debts. This amount is deducted from debtors in the balance sheet.

    Now if Rs 400 was recorded as actual bad debts, then it is deducted from the provision for doubtful debts instead of debtors. Further another 400 is added back to provision for doubtful debts to maintain the percentage.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Miscellaneous

What are the objectives of Financial Analysis?

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 25, 2021 at 4:04 pm
    This answer was edited.

    Financial analysis of a company means analyzing the previous data of the company and giving recommendations based on that whether the company will improve in the future on not. It is the process of evaluating the financial performance and stability of the company. There are various types of financiaRead more

    Financial analysis of a company means analyzing the previous data of the company and giving recommendations based on that whether the company will improve in the future on not.

    It is the process of evaluating the financial performance and stability of the company.

    There are various types of financial analysis. They are leverage, growth, cash flow, liquidity, profitability, etc.

    The main objectives of Financial analysis are

    1.Reviewing the current position: In order to know if the company is doing well, past analysis of data is required to be carried out. Regular recording of the transactions helps to understand the financial position of the company.

    For example, A company wants to generate a revenue of 2000 crores in the next 5 years. The last four years’ data shows revenue as 1100, 1300,1600, 1800 crores respectively.

    So from the above, we can say that the company is performing well and looks like it will reach the desired target in the fifth year or may perform better than the target desired.

    However, if the revenue declines, it will cause concern for the team but the team will get time to gear up and work efficiently to achieve the desired target.

    2. Ease in decision making: For Future decision-making, quarterly financials play an important role. Subsidiary books and accounts like the sales book, purchase orders, manufacturing a/c, etc. help in giving more reliable information.

    For example, If sales are increasing inconsistently in a quarter, and in the next quarter the level of sales decrease due to any reason then the management can analyze and change the strategy.

    3. Performance Comparison: It helps in comparing the performance of the business every month, quarterly, half-yearly, and yearly. Analyzing the data can help the management to compare if the company is proceeding in the right direction.

    4. Assessing the profitability: Financial statements are used to assess the profitability of the firm. The analysis is made through the accounting ratios, trend line, etc. Accounting ratios calculated for a number of years shows the trend of change of position i.e. positive, negative or static. The assessing of the trend helps the management to analyze if the company is making profits or not.

    5. Measure the solvency of the firm: Financial analysis helps to measure the short-term and long-term efficiency of the firm for the benefit of the Stakeholders.

    6. Helps the end-users: The owners are the end-users for whom the financial statements are prepared. Financial statements are the summaries that are prepared for providing various disclosures to the owners which helps them understand the statements in a better way. If the end-users arrive at the right decision with the help of financial statements that means the objective is achieved.

    7. Other objectives:

    • It helps to settle disputes among the parties.
    • It helps in the expansion decision of the firm.
    • It helps in analyzing the amount of tax to be paid.
    • It reduces the chances of fraud.
    • It provides information about resources.
    • It provides a true and fair view of financial position.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

Which of the following accounts have a debit balance?

A. Furniture B. Capital C. Sales D. Commission earned

  • 1 Answer
  • 5 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 14, 2023 at 2:55 am

    Definition Where the total of the debit side is more than the credit side therefore the difference is the debit balance and is placed credit side as “ by balance c/d “ A furniture account that is an asset has a debit balance. Debit balance may arise due to timing differences in which case income wilRead more

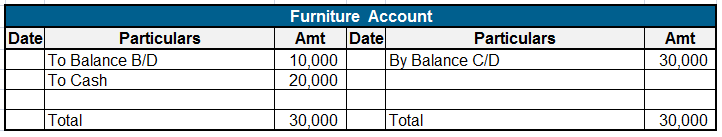
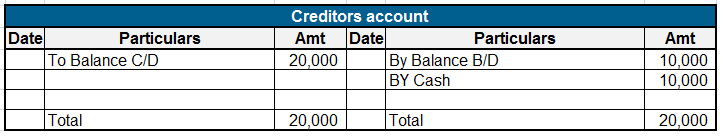
    Definition

    Where the total of the debit side is more than the credit side therefore the difference is the debit balance and is placed credit side as “ by balance c/d “

    A furniture account that is an asset has a debit balance.

    Debit balance may arise due to timing differences in which case income will be accrued at the year’s end to offset the debit.

    The amount is shown in the record of a company s finances, by which its total debits are greater than its total credits.

    The account which has debit balances are as follows:

    • Assets accounts

    Land, furniture, building machinery, etc

    • Expenses accounts

    Salary, rent, insurance, etc

    • Losses

    Bad debts, loss by fire, etc

    • Drawings

    Personal drawings of cash or assets

    • Cash and bank balances

    Balances of these accounts

    The account has credit balances as follows:

    • Liabilities accounts

    Creditors, bills payable, etc

    • Income accounts

    Salary received, interest received, etc

    • Profits

    Dividends, interest, etc

    • Capital

    Partners Capital


    Here are some examples showing the debit balances and credit balances of the accounts :

    See less
    • 5
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

What is the meaning of post to the ledger accounts?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 10, 2022 at 12:53 pm
    This answer was edited.

    Ledger posting As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting toRead more

    Ledger posting

    As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting to the ledger accounts. Balancing of ledgers is carried out to find differences at the year’s end.

    Posting to the ledger account means entering information in the ledger, and respective accounts from the journal for individual records. The accounts that are credited are posted to the credit side and vice versa.

    Ledger maintenance is done at the end of an accounting period and it’s maintained to reflect a permanent summary of all the journal accounts. In the end, all the accounts that are entered and operated in the ledger are closed, totaled, and balanced. Balancing the ledger means finding the difference between the debit and credit amounts of a particular account.

    While posting to the ledger account, suppose goods were bought for cash. While passing the journal entry, we’ll be debiting the purchases a/c and crediting the cash a/c by stating it as, ‘To Cash A/c’.

    Now, this entry will be affecting both the purchases account and the cash account. In the cash account, we’ll be debiting purchases. Whereas in the purchases account, we’ll be crediting the cash. That’s how it works in the double-entry bookkeeping system of accounting.

    Example

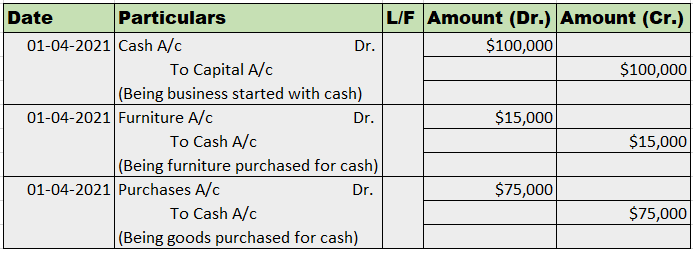
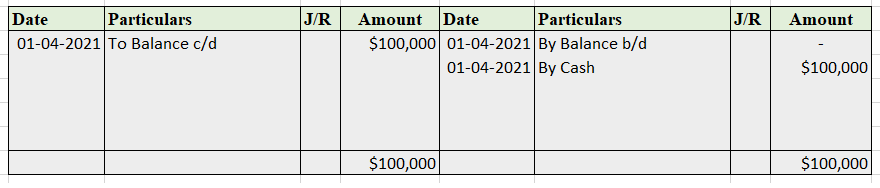
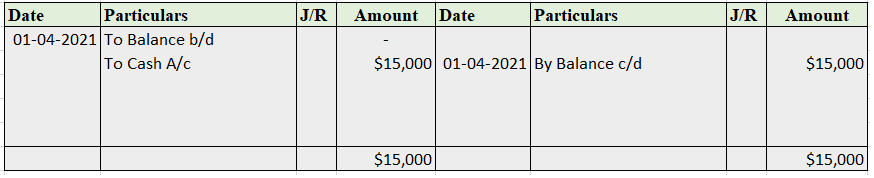
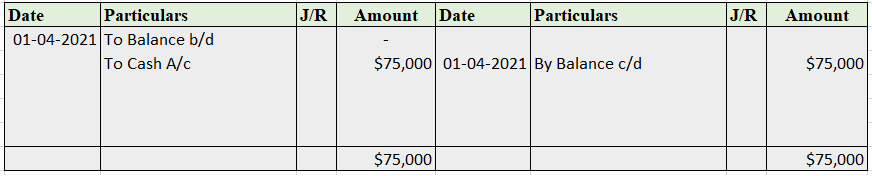
    Mr. Tony Stark started the business with cash of $100,000 on April 1, 2021. He bought furniture for business for $15,000. He further purchased goods for $75,000.

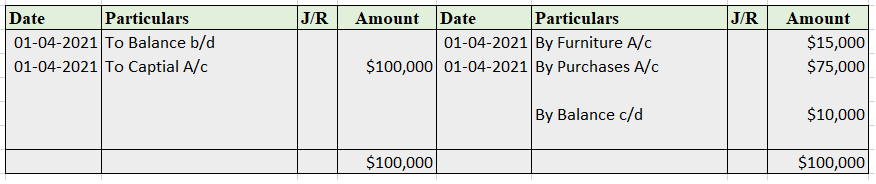
    Now, we’ll be journalizing the transactions and posting them into the ledger accounts.

    Journal Entries

    Posting to Ledger Account

    Cash A/c

    Capital A/c

    Furniture A/c

    Purchases A/c


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Atreya
AtreyaCurious
In: 1. Financial Accounting > Partnerships

What do you mean by LLP ?

  • 1 Answer
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on May 23, 2023 at 2:18 pm

    Definition A limited liability partnership (LLP)is a business vehicle like a partnership that features the partners ‘ liability is limited. Thus, it has elements of partnership and company. Another important feature of LLP is that each partner is not responsible or liable for another partner’s miscoRead more

    Definition

    A limited liability partnership (LLP)is a business vehicle like a partnership that features the partners ‘ liability is limited. Thus, it has elements of partnership and company.

    Another important feature of LLP is that each partner is not responsible or liable for another partner’s misconduct or negligence.

    LLP as constituted in INDIA:

    The limited liability partnership act, 2008 came into effect on 31st march, 2009. LLP is different from a partnership as it operates like a partnership, but in an LLP each partner is protected from personal liability, except to the extent of his capital contribution in the LLP.

    • LLP is subject to income tax like any other partnership firm.

    • A partner is not liable for independent or unauthorized actions of other partners, thus allowing individual partners to be shielded from joint liability created by another partner‘s wrongful business decisions or misconduct.

    • LLP is a body corporate and legal entity separate from its partners. It has perpetual succession like a limited liability company.

    Indian partnership act 1932 is not applicable to LLPs and also the limit on the number of partners in an LLP is not applicable, unlike an ordinary partnership firm where the maximum number of partners cannot exceed the number specified under SEC 464 of Companies Act 2013, which at present is 50.

    The LLP Act, 2008 specifies that a least one of the partners in the LLP is a citizen of India and an Indian national.

    • The Registrar Of Companies ( ROC) is authorized to register and control LLPs.


    Characteristics

    • Separate legal entity :

    Like a company, LLP also has a separate legal entity. Therefore partners and LLP are distinct from each other, like a company where the company has a legal entity separate from its shareholders.

    • Minimum capital :

    LLP is not required to maintain minimum capital. Thus partners in LLP decide how much capital will be contributed by each partner.

    • The Minimum number of members :

    An LLP can be established with at least two members who shall also be the designated partners and shall have Director Identification Number (DIN).

    There is no limit on the maximum number of partners. Members other than designated partners are required to have DIN.

    • Audit is not mandatory :

    All companies, whether private or public, are required to get their accounts audited. However, an audit of LLP‘s books of accounts is not mandatory except :

    • If the contribution of the LLP exceeds Rs 25 lakhs: or
    • If the annual turnover of the LLP exceeds Rs 40 lakhs.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

What is a non-current asset?

  • 1 Answer
  • 0 Followers
Answer
  1. Akash Kumar AK
    Added an answer on November 26, 2022 at 8:06 am
    This answer was edited.

    Generally, Assets are classified into two types. Non-Current Assets Current Assets   Non-Current Asset Noncurrent assets are also known as Fixed assets. These assets are an organization's long-term investments that are not easily converted to cash or are not expected to become cash within an acRead more

    Generally, Assets are classified into two types.

    1. Non-Current Assets
    2. Current Assets


    Non-Current Asset

    Noncurrent assets are also known as Fixed assets. These assets are an organization’s long-term investments that are not easily converted to cash or are not expected to become cash within an accounting year.

    In general terms, In accounting, fixed assets are assets that cannot be converted into cash immediately. They are primarily tangible assets used in production having a useful life of more than one accounting period. Unlike current assets or liquid assets, fixed assets are for the purpose of deriving long-term benefits.

    Unlike other assets, fixed assets are written off differently as they provide long-term income. They are also called “long-lived assets” or “Property Plant & Equipment”.


    Examples of Fixed Assets

    • Land
    • Land improvement (e.g. irrigation)
    • Building
    • Building (work in progress)
    • Machinery
    • Vehicles
    • Furniture
    • Computer hardware
    • Computer software
    • Office equipment
    • Leasehold improvements (e.g. air conditioning)
    • Intangible assets like trademarks, patents, goodwill, etc. (non-current assets)


    Valuation of Fixed asset

    fixed assets are recorded at their net book value, which is the difference between the “historical cost of the asset” and “accumulated depreciation”.

    “Net book value = Historical cost of the asset – Accumulated depreciation”


    Example:

    Hasley Co. purchases Furniture for their company at a price of 1,00,000. The Furniture has a constant depreciation of 10,000 per year. So, after 5 years, the net book value of the computer will be recorded as

    1,00,000 – (5 x 10,000) = 50,000.

    Therefore, the furniture value should be shown as 50,000 on the balance sheet.


    Presentation in the Balance Sheet

    Both current assets and non-current assets are shown on the asset side(Right side) of the balance sheet.


    Difference between Current Asset and Non-Current Asset

    Current assets are the resources held for a short period of time and are mainly used for trading purposes whereas Fixed assets are assets that last for a long time and are acquired for continuous use by an entity.

    The purpose to spend on fixed assets is to generate income over the long term and the purpose of the current assets is to spend on fixed assets to generate income over the long term.

    At the time of the sale of fixed assets, there is a capital gain or capital loss but at the time of the sale of current assets, there is an operating gain or operating loss.

    The main difference between the fixed asset and current asset is, although both are shown in the balance sheet fixed assets are depreciated every year and it is valued by (the cost of the asset – depreciation) and current asset is valued as per their current market value or cost value, whichever is lower.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Journal Entries

What is the journal entry for interest on capital?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on July 24, 2022 at 5:30 pm
    This answer was edited.

    Interest on capital Interest on capital is interest payable to the owner/partners for providing a firm with the required capital to commence the business. It's a fixed return that a business owner is eligible to receive. When the business firm faces a loss, the interest on capital will not be providRead more

    Interest on capital

    Interest on capital is interest payable to the owner/partners for providing a firm with the required capital to commence the business. It’s a fixed return that a business owner is eligible to receive.

    When the business firm faces a loss, the interest on capital will not be provided. It is permitted only when the business earns a profit. Such payment of interest is generally observed in partnership firms. It is provided before the division of profits among the partners in a partnership firm.

    If an owner or partner introduces additional capital to the business, it is also taken into account for providing interest on capital.

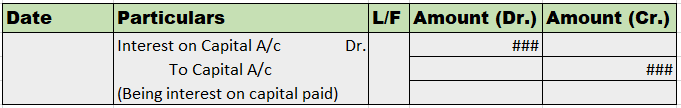
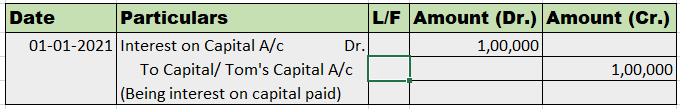
    Sample journal entry

    Interest on capital is an expense for business, thus, debited as per the golden rules of accounting, debit the increase in expense, and the owner/partner’s capital a/c is credited as per the rule, credit all incomes and gain.

    As per the modern rules of accounting, we debit the increase in expenditure and credit the increase in capital.

    As we know, as per the business entity concept, business and owner are two different entities and a business is a separate living entity. Therefore, the capital introduced by the owner/partners is the amount on which they’re eligible to receive a return.

    Example:

    Tom is the business owner of the firm XYZ Ltd. He has contributed ₹ 10,00,000 to the business with 10% interest provided to Tom at the end of the year.

    Solution:

    Here interest on capital will be calculated as,

    Interest on capital = Amount invested × Rate of interest × Number of Months/12

    = 10,00,000 × 10% × 12/12

    = ₹ 1,00,000

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

Is bad debt a nominal account?

  • 1 Answer
  • 0 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on January 13, 2023 at 7:12 am
    This answer was edited.

    Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who's ever returning the money is significantly low. Bad debt is a nominal account. A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profitRead more

    Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who’s ever returning the money is significantly low. Bad debt is a nominal account.

    A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profit or loss. The balances on nominal accounts are normally written off at the end of each financial year. For example, sales A/c, purchases A/c, interest income, loss from the sale of assets etc.

    Why are bad debts A/c classified as a nominal account?

    First of all, let us understand the other two types of accounts – personal accounts and real accounts.

    Personal accounts deal with the records of the business’ transactions with a particular person or entity. For example Mukesh A/c, Mahesh A/c, Reliance A/c, Suresh and Co. A/c etc.

    Real accounts deal with transactions and records related to assets. The balance in these accounts is normally carried forward from one period to another. For example “Furniture A/c “, ” Building A/c ” etc.

    Now that we have understood the basic definitions of all three types of accounts, we can discuss the reason behind the classification of bad debts as nominal accounts.

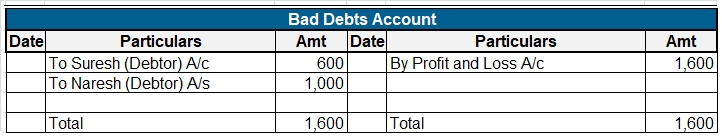
    A bad debt is a loss that the company has incurred. It may be due to bankruptcy of customers, customer fraud etc. The company isn’t going to receive that money. The bad debts are written off at the end of the year by transferring them to profit and loss A/c.

    Thus, bad debts relate to loss and are normally not carried forward from one period to another. Hence, they are classified as nominal accounts.

    Treatment of Bad Debts

    Bad debts are written off at the end of each year by debiting them to the profit and loss A/c. The amount of bad debts is reduced from the amount of debtors that the company has.

    A company may also choose to create a provision for bad debts for the balance amount of debtors that the company has after adjusting for bad debts. This provision represents a rough estimate of the amount due to debtors that the business expects to not receive. In other words, it is an estimate of customer bankruptcy that the business expects.

    Conclusion

    We can conclude that

    • There are primarily three types of accounts – real, personal and nominal.
    • Bad debts are a nominal account.
    • Bad debts is a loss that the business has incurred
    • It may be due to bankruptcy of customers, fraud etc
    • Bad debts are written off each year by transferring them to the income statement
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of balancing an account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on January 4, 2022 at 11:18 am
    This answer was edited.

    Meaning We know that an account in ledger format has two amount columns i.e. debit and credit amount columns. Now, most of the time, the total of debit and credit sides do not match.  The difference between their totals is called the balance of the account and it is posted on the shorter side. ThisRead more

    Meaning

    We know that an account in ledger format has two amount columns i.e. debit and credit amount columns. Now, most of the time, the total of debit and credit sides do not match.  The difference between their totals is called the balance of the account and it is posted on the shorter side. This result in equalling the total of both sides, hence this act is called ‘balancing an account.

    Types of balances

    Balancing an account is a very usual practice so that the balance of an account can be known. An account can have two types of balances:

    • Debit balance, where the debit side total is more than the credit side total.
    • Credit balance, where the credit side is more than the debit side total.

    The balance of an account is posted on the shorter side. It means:

    • The debit balance will be shown on the credit side as the credit side total is shorter. (posted as ‘By Balance c/d’)
    • The credit balance will be shown on the debit side as the debit side total is shorter (posted as ‘To Balance c/d’)

    Example

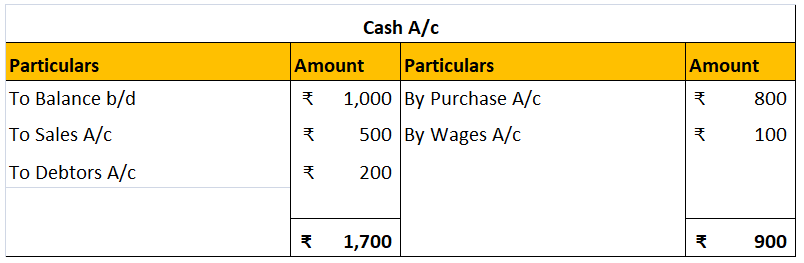
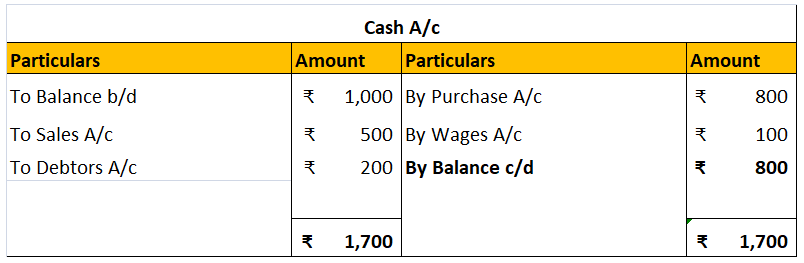
    The following is a cash account that is not balanced:


    We can see the debit side is ₹800 more than the credit side. It means there is a debit balance. It will be posted on the credit side as ‘By balance c/d’ to balance the account.

    Exceptions

    Balance of the income and the expense accounts (nominal accounts)are not computed. Instead, they are closed to trading account or profit and loss account to balance their amount totals. For example, the salaries account and sales accounts

    Only the balance of the following types of accounts are computed and carried forwarded to successive accounting years:

    • Assets
    • Liabilities
    • Capital

    The balance of these accounts is shown on the trial balance and balance sheet as well.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

The term current assets does not include?

Cash Stock in trade Furniture Advance Payment

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 6, 2022 at 3:49 pm
    This answer was edited.

    The correct option is 3.) The term current assets do not include furniture. Explanation A current asset is any asset that can reasonably be expected to be sold, consumed, or exhausted through the normal operations of a business within one accounting year. Thus, current assets don't have life for morRead more

    The correct option is 3.)

    The term current assets do not include furniture.

    Explanation

    A current asset is any asset that can reasonably be expected to be sold, consumed, or exhausted through the normal operations of a business within one accounting year. Thus, current assets don’t have life for more than a year.

    Example: Cash and cash equivalent, stock, liquid assets, etc.

    Furniture is expected to have a useful life for more than a year and they are bought for a long term by a company.

    Cash is a more liquid asset of a company making it a more “current” asset. It requires no conversion and is spendable as it is. Thus, making it a vital current asset.

    Stock in trade is a current asset because it can be converted into cash within one year and all the stock in trade of a company is expected to be sold within one accounting period and should not stick for a longer period.

    Advance payment, on the other hand, is an amount paid to an employee, essentially a short-term loan by the employer. It’s recorded on the asset side of the balance sheet and as these assets are used, they are expended and recorded on the income statement for the period in which they are incurred, making it a short-term asset ending within an accounting year.

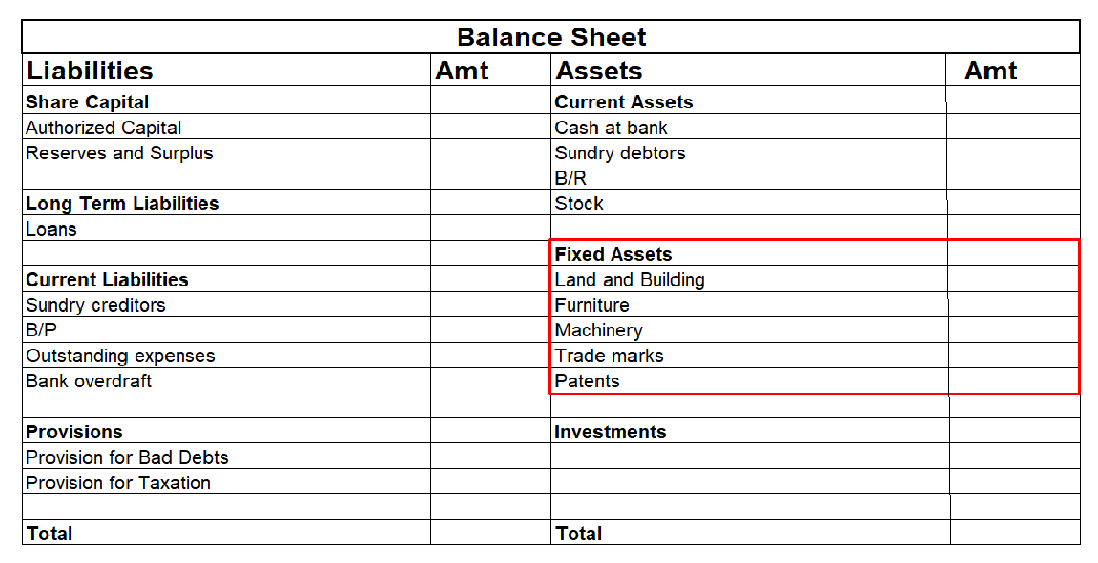
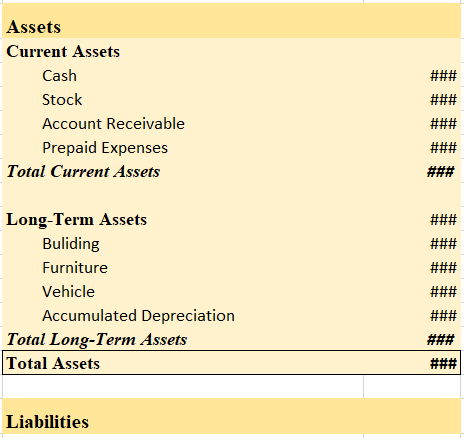
    Thus, on the asset side of the balance sheet, we can clearly see which current assets are and which are not included in the current asset

    Balance Sheet (As at…..)

    Therefore, (3) Furniture, won’t be included in current assets.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.