

In a partnership firm, the partners may withdraw certain amounts from the firm for their personal use. Such amounts withdrawn by the partners are called drawings. This amount is usually deducted from their capital. The partners are required to pay an amount as interest, based on the time period forRead more
In a partnership firm, the partners may withdraw certain amounts from the firm for their personal use. Such amounts withdrawn by the partners are called drawings. This amount is usually deducted from their capital. The partners are required to pay an amount as interest, based on the time period for which the money was withdrawn. This amount is called Interest on Drawings.
The journal entry for interest on drawings is as follows:
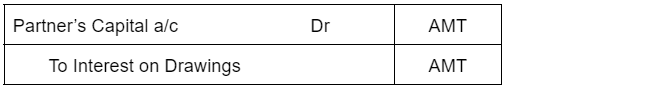
Since interest on drawings is an income to the firm, it is credited based on the rule that “increase in incomes are credited”. Since the partner has to bear the interest amount, his capital account is debited as a “ decrease in capital is debited”.
FORMULAS
The basic formula for interest on drawings is:
Interest on drawings = Amount of Drawings x Rate/100 x No. of months/12
- When equal amounts of drawings are withdrawn at the beginning of every month, then
Interest on Drawings = Total Drawings x Rate/100 x (12+1)/2 - When equal amounts of drawings are withdrawn at the end of every month, then the Interest on Drawings = Total Drawings x Rate/100 x (12-1)/2
- When the date of the drawing is not specified, it is assumed to be withdrawn evenly. Hence Interest on Drawings = Total Drawings x Rate/100 x 6/12
The calculations in 1,2 and 3 are done so that drawings can be calculated for the average period.
EXAMPLE
Jack is a partner who withdrew $20,000 on 1st April 2020. Interest on drawings is charged at 10% per annum. If we have to calculate interest on drawings as of 31st December, then
Interest on Drawings = 20,000 x 10/100 x 9/12 = $1,500
(Here, interest on drawings is outstanding for 9 months, that is from April to December)

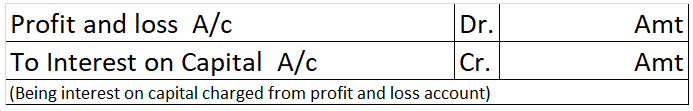



Definition Bad debts are a debt owed to an enterprise that is considered to be irrecoverable or we can say that it is owed to the business that is written off because it is irrecoverable. Sometimes debtors are unable to pay the amount due either partially or fully. the amount that is not receivableRead more
Definition
Bad debts are a debt owed to an enterprise that is considered to be irrecoverable or we can say that it is owed to the business that is written off because it is irrecoverable.
Sometimes debtors are unable to pay the amount due either partially or fully. the amount that is not receivable is a loss and is called bad debt.
Bad debts are neither assets nor liabilities they are expenses that are debited to the profit and loss account and reduced from debtors in the balance sheet.
For example loans from banks are declared as bad debt, sales made on credit and amounts not received from customers, etc.
Related terms
So there are a few related terms whose meanings you should know
Accounting methods
There are two methods for accounting for bad debts which are mentioned below:-
Accounting treatment
Now let me try to explain to you the accounting treatment for bad debts which is as follows :
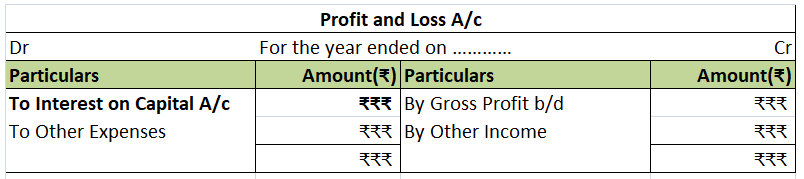
Now let me show you the extract of the profit and loss account and balance sheet showing bad debts and bad debts recovered which are as follows:-

See less