

Journal entries in the ledger What is a Journal Entry? Journal entry is a form of bookkeeping. All the economic or non-economic transactions in the business are recorded in the journal entries showing a company's debit or credit balances. It is a double-entry accounting method and requires at leastRead more
Journal entries in the ledger
What is a Journal Entry?
Journal entry is a form of bookkeeping. All the economic or non-economic transactions in the business are recorded in the journal entries showing a company’s debit or credit balances. It is a double-entry accounting method and requires at least two accounts or more in a transaction.
The journal entry helps to identify the transactions. We use journals to get a running list of business transactions. Each journal entry provides this specific information about a transaction:
- Date of the transaction.
- Accounts involved in it.
- Payer, payee, receiver, etc.
- Account name.
- Debit and credit of money.
General Ledger
After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. A ledger account contains information about a specific account. It contains the opening balance as well as the closing balances of an account. It summarizes the business transactions.
Transferring the entries from journals to respective ledger accounts is called ledger posting or posting to the ledger accounts. Balancing of ledgers is carried out to find differences at the year’s end, it means finding the difference between the debit and credit amounts of a particular account.
For instance,
Suppose goods were bought for cash. While passing the journal entry, we’ll be debiting the purchases a/c and crediting the cash a/c by stating it as, ‘To Cash A/c’.
Now, this entry will be affecting both the purchases account and the cash account. In the cash account, we’ll be debiting purchases. Whereas in the purchases account, we’ll be crediting the cash. That’s how it works in the double-entry bookkeeping system of accounting.
Example
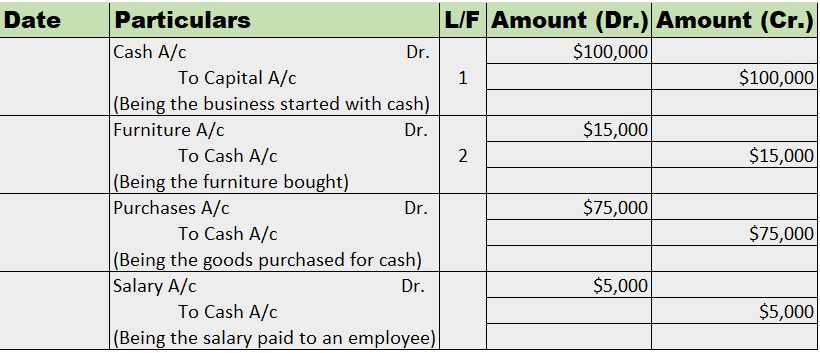
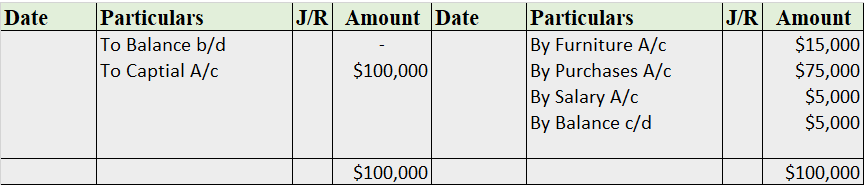
Mr. Tony Stark started the business with cash of $100,000. He bought furniture for business for $15,000. He further purchased goods for $75,000. He hired an employee and paid him a salary of $5,000.
Now, we’ll be journalizing the transactions and posting them into the ledger accounts.
Journal Entries
Recording into Ledger Account
Cash A/c
Capital A/c
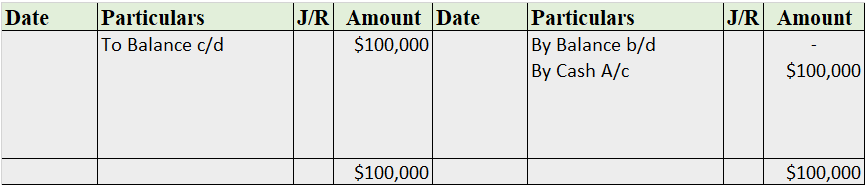
Furniture A/c
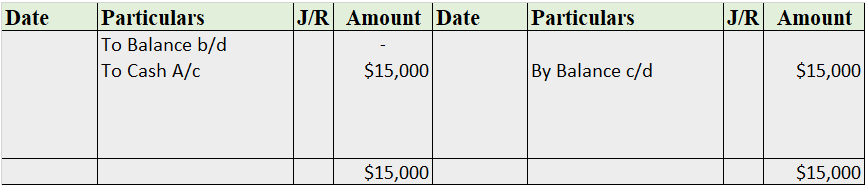
Purchases A/c
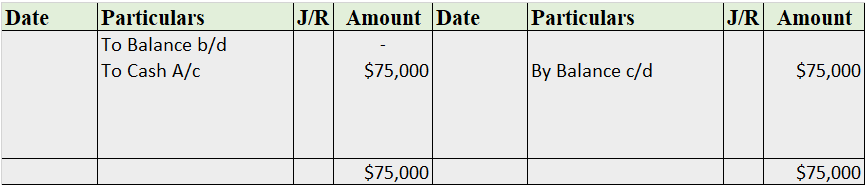
Salary A/c
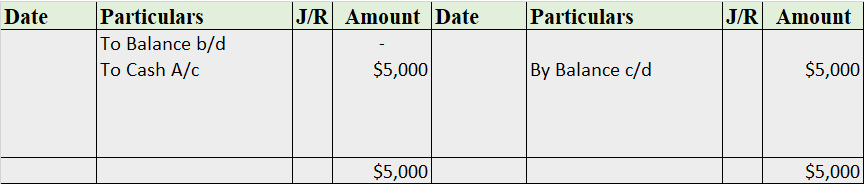
Note: The balance b/d is not applicable as this is the business’ commencement year.
See less








Yes, Accounts Payable can have a Debit balance. Accounts payable is a liability and thus, has a credit balance but can have a debit balance in case the creditor is overpaid or when there is purchase return (for already-paid goods) ACCOUNTS PAYABLE Accounts payable refers to all short-term liaRead more
Yes, Accounts Payable can have a Debit balance. Accounts payable is a liability and thus, has a credit balance but can have a debit balance in case the creditor is overpaid or when there is purchase return (for already-paid goods)
ACCOUNTS PAYABLE
Accounts payable refers to all short-term liabilities of the business that are to be paid. These are usually paid within a duration of 90 days. It includes both Trade payable (goods and services purchased on credit) as well as expenses payable (used but payment not made yet) like rent payable, electricity bill, etc.
Businesses cannot make every payment on the spot. There can be cases when the business is facing a shortage of funds, can have funds but doesn’t have enough cash (or liquid funds) to make payment or simply doesn’t want to make payment on the spot to reduce its capital requirement.
So, like us businessmen also purchase goods on credit or use services for which payment is to be made soon. All these are liabilities for the business.
However, they must be related to the business to be considered as accounts payable.
DEBIT BALANCE OF ACCOUNTS PAYABLE
Debit balance of accounts payable means money owed by others. There is Debit balance when
OVERPAYMENT is made to the creditors or the supplier. It happens when the wrong amount is paid or payment is made twice for the same transaction.
Suppose you need to pay $10,000 as rent within 30 days. After 25 days you mistakenly made a payment of $12,000.
In this case,
PURCHASE RETURN of already paid goods also result in debit balance of Accounts Payable.
Suppose you bought goods worth $50,000 from Mr A on credit and paid for the same. Later, you returned all the goods because they were defective. Now, there will be Debit balance of Accounts Payable till there is a full refund of $50,000 by Mr A.
How is Accounts Payable Treated Normally?
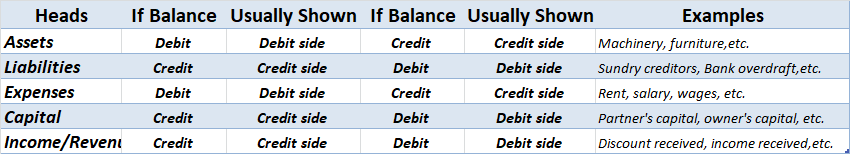
Accounts Payable are the current liabilities of the firm and are shown under the head Current Liabilities in the Balance Sheet. Its liability, thus has a credit balance which represents the amount owed by the firm to others. It is credited when increases and debited when decreases.
For example – Suppose you purchased goods worth $30,000 and agreed to pay after 30 days. So, Accounts payable will be credited by $30,000 and purchases will be debited by $30,000.
Purchases A/c – $30,000 (debit)
To Accounts Payable A/c – $30,000
After 30 days payment is made in cash, which means the liability decreased. So, Accounts Payable A/c will be debited.
Accounts Payable A/c – $30,00
To Cash – $30,000
See less