

When a manager provides services to a company, he is expected to receive some kind of compensation. This is given in the form of managerial remuneration. Section 197 of the Companies Act allows a maximum remuneration of 11% of the net profit of the company to the directors, managing directors and whRead more
When a manager provides services to a company, he is expected to receive some kind of compensation. This is given in the form of managerial remuneration. Section 197 of the Companies Act allows a maximum remuneration of 11% of the net profit of the company to the directors, managing directors and whole-time directors etc. This section is applicable for public companies and not private companies
Yes, a company can pay managerial remuneration in case of inadequacy of profits or losses, provided they follow the condition in Schedule V of the Companies Act 2013.
Conditions
In order to pay remuneration while the company is at a loss, it has to comply with the following:
- Pass a resolution at the board meeting
- The company has not defaulted in payments to any Banks, non-convertible debenture holders or any secured creditors. But in case of default, the company has obtained prior approval from such creditors or banks before obtaining approval from their general meeting.
- Ordinary resolution or special resolution (if the limit is exceeded)
The limit mentioned above refers to the maximum limit of Rs 60 lakhs when the effective capital is negative or less than Rs 5 Crore. Such remuneration can also only be paid if such a manager does not have any interest in the company and also possesses special knowledge and expertise along with a graduate-level qualification.
Effective capital is the aggregate of paid-up share capital, share premium, reserves and surplus, long term loans and deposits and after subtracting Investments, accumulated losses and preliminary expenses not written off.
Percentage of Remuneration
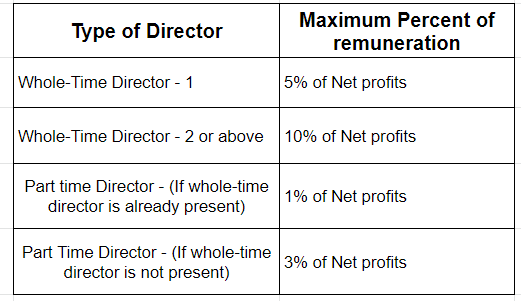
When the Company earns adequate profits, they are allowed to provide remuneration up to a certain per cent. The percentage of remuneration depends on whether the directors are working whole-time or part-time according to the Companies Act.






No, capital account is not a real account. Capital account represents the amount of money invested by the owner/owners of the business along with the retained earnings net of drawings or dividends. Capital account has a natural credit balance because it is an internal liability of the business. CapiRead more
No, capital account is not a real account.
Capital account represents the amount of money invested by the owner/owners of the business along with the retained earnings net of drawings or dividends. Capital account has a natural credit balance because it is an internal liability of the business.
Capital account is a personal account because, as discussed above, it represents the investment of the owner or owners. Personal account represents person or persons.
Whereas a real account represents the material assets of a business. Example:- Cash A/c, Fixed assets A/c etc. That’s why the capital account is not a real account.
Being a personal account, the following golden rule of accounting applies to capital account:-
“Debit the receiver and credit the giver”
Here, as the owner gives an amount as an investment into the business (owner and the business are separate entities), the capital account has a credit balance.

See less