Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Aadil
AadilCurious
In: 1. Financial Accounting > Ledger & Trial Balance

Write the process of preparing ledger from a journal?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on August 11, 2021 at 8:01 am
    This answer was edited.

    As you know all transactions occurring in a business are recorded in the journal (book of original entry) in chronological order. After recording them in the journal, they are posted to their respective ledger accounts. Here I've explained the steps involved in posting a journal entry to the ledger.Read more

    As you know all transactions occurring in a business are recorded in the journal (book of original entry) in chronological order. After recording them in the journal, they are posted to their respective ledger accounts.

    Here I’ve explained the steps involved in posting a journal entry to the ledger.

    Posting of an account debited in the journal entry:

    Step 1: Identify the account which has to be debited in the ledger.

    Step 2: Write the date of the transaction under the ‘Date Column’ of the debit side of the ledger account.

    Step 3: Write the name of the account which has been credited in the journal entry in the ‘Particulars Column’ on the debit side of the account as “To (name of the account)”.

    Step 4: Write the page number of the journal where the entry exists in the ‘Journal Folio (JF) Column’.

    Step 5: Enter the amount in the ‘Amount Column’ on the debit side of the ledger account.

    Posting of an account credited in the journal entry:

    Step 1: Identify the account which has to be credited in the ledger.

    Step 2: Write the date of the transaction under the ‘Date Column’ of the credit side of the ledger account.

    Step 3: Write the name of the account which has been debited in the journal entry in the ‘Particulars Column’ on the credit side of the account as “By (name of the account)”.

    Step 4: Write the page number of the journal where the entry exists in the ‘Journal Folio (JF) Column’.

    Step 5: Enter the amount in the ‘Amount Column’ on the credit side of the ledger account.

    I’ll explain the process of preparing a ledger A/c with a simple transaction.

    On 1st May ABC Ltd. purchased machinery for 5,00,000. In the Journal the following entry will be made.

    Machinery A/c   5,00,000
       To Bank A/c   5,00,000
    (Being machinery purchased for 5,00,000)

    Let’s assume that this entry appears on page no. 32 of the journal. Now we will open Machinery A/c and Bank A/c in the Ledger.

    On the debit side of the Machinery A/c “To Bank A/c” will be written. In the Bank A/c “By Machinery A/c” will be written on the credit side.

    An extract of both the accounts are as follows:

    Machinery A/c

    Date Particulars J.F. Amt. Date Particulars J.F. Amt.
    May-01 To Bank A/c 32   5,00,000


    Bank A/c

    Date Particulars J.F. Amt. Date Particulars J.F. Amt.
    May-01 By Machinery A/c 32   5,00,000
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Miscellaneous

What are direct expenses examples?

  • 1 Answer
  • 0 Followers
Answer
  1. Akash Kumar AK
    Added an answer on November 23, 2022 at 7:47 am
    This answer was edited.

    Expenses are of two types, are Direct Expenses Indirect Expenses   Direct Expenses Direct expenses are those expenses are which are directly related to the manufacturing or production of the final goods. These expenses are also known as Manufacturing expenses. Manufacturing or production of gooRead more

    Expenses are of two types, are

    1. Direct Expenses
    2. Indirect Expenses


    Direct Expenses

    Direct expenses are those expenses are which are directly related to the manufacturing or production of the final goods. These expenses are also known as Manufacturing expenses.

    Manufacturing or production of goods indicates the conversion of Raw material into finished goods. the expenses incurred in the stage of conversion are treated as Direct expenses or Manufacturing expenses.

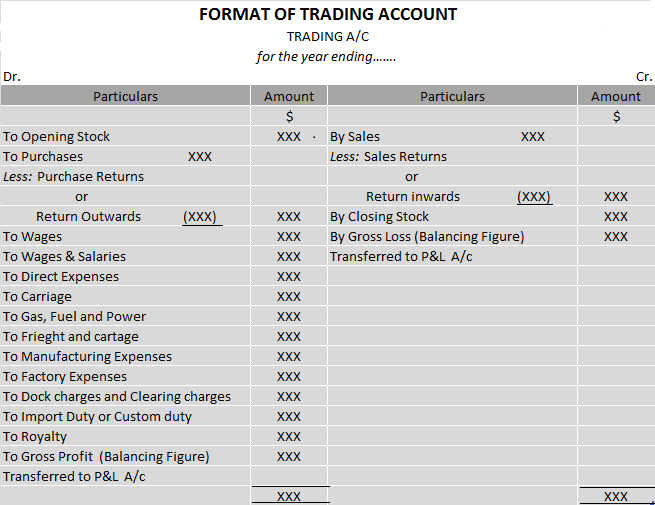
    Direct expenses are shown on the Debit side of the Trading Account.


    Indirect Expenses

    Indirect expenses are those expenses that are incurred to run a business day-to-day and maintenance of the company.  In other words, they are not directly related to making a product or service or buying a wholesale product to resell.

    Indirect expenses are classified into three types, which are

    1. Factory Expenses
    2. Administrative Expenses
    3. Selling & Distribution Expenses

    Indirect Expenses are shown on the Debit side of the Profit and Loss Account.


    Presentation of Direct Expenses in Trading Account
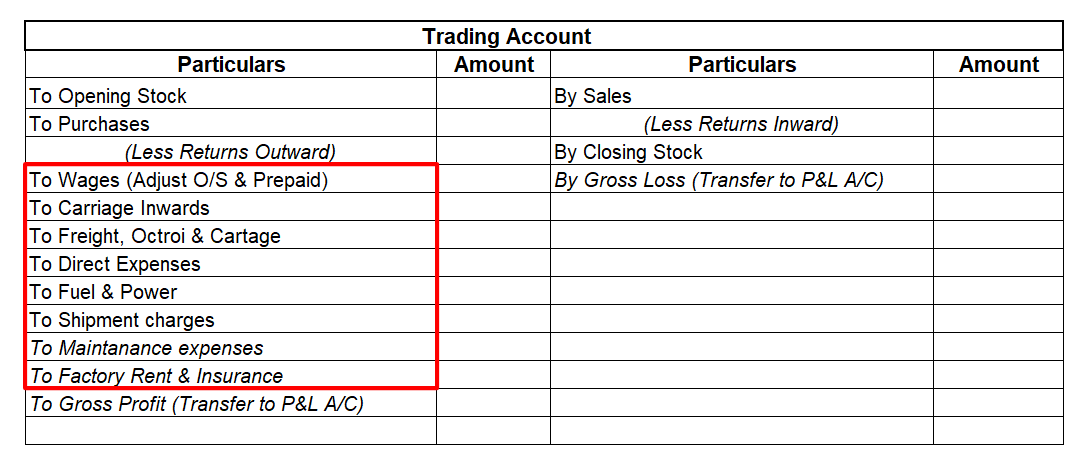
     

    Examples of Direct Expenses

    1. Gas, water, and Fuel: Gas, water, and fuel are the essentials to run a factory and are used in machinery to manufacture its final goods.
    2. Wages: Wages are the daily payments to the workers or Labours working in the factory premises on a daily or weekly payment basis.
    3. Freight and Carriage: Freight and Carriage are the expenses related to the importing of raw materials from the godown or from the outsiders to the Factory.
    4. Factory Rent: Rent paid for the factory area or any payment related to the place of the factory is known as factory rent.
    5. Factory Lighting: The expenses related to the uniform distribution of light over the working plane are obtained in the factory premises.
    6. Factory Insurance: The payment of insurance related to the factory will come under direct expenses.
    7. Manufacturing Expenses: Any other expenses related to the manufacturing process of finished goods are manufacturing expenses.
    8. Cargo Expenses: These are the expenses related to goods or freight being shipped or carried by the ocean, air, or land from one place to another.
    9. Upkeep and Maintenance: These are the expenses related to the maintenance of the factory for smooth running.
    10. Repairs on Machinery: The expenses related to any repair on machinery which is used in the production.
    11. Coal, Oil, and Grease: Coal, oil, and grease are the essentials to run machinery which results in the conversion of raw material to finished goods.
    12. Custom Charges: The expenses related to the payment of any Customs duty for the material imported.
    13. Clearing Charges: A clearing charge is a charge assessed on securities transactions by a clearing house for completing transactions using its own facilities.
    14. Depreciation on Machinery: Generally it is a nonmonetary expense but recorded in the trading account as a direct expense as per the accrual accounting.
    15. Import duty: any payment related to the importing of any machinery or any material from other countries is known as import duty.
    16. Octroi: this is the tax levied by a local political unit, normally the commune or municipal authority, on certain categories of goods as they enter the area.
    17. Shipping expenses: any expense related to the shipment charges of the raw material is known as shipping expenses.
    18. Motive power: Motive Power basically means any power, such as electricity or steam energy, etc, used to impart motion to any source of mechanical energy.
    19. Dock dues: a payment that a shipping company must pay for the use of a port.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Financial Statements

Where is land on a balance sheet?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 19, 2022 at 8:30 pm
    This answer was edited.

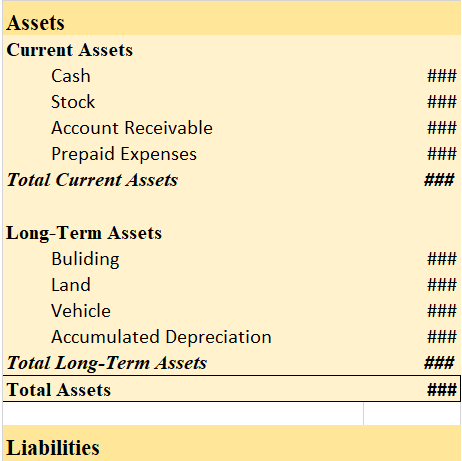
    Land in the balance sheet The land is an asset and hence it is shown on the asset side of the balance sheet. On the asset side of the balance sheet, the land is stated under the heading long-term assets. Balance Sheet (for the year…) Explanation The land is a fixed asset and is supposed not to be caRead more

    Land in the balance sheet

    The land is an asset and hence it is shown on the asset side of the balance sheet.

    On the asset side of the balance sheet, the land is stated under the heading long-term assets.

    Balance Sheet (for the year…)

    Explanation

    The land is a fixed asset and is supposed not to be cashed, consumed, last, sold, or written off within one accounting year and is purchased for long-term use. The fixed assets are also called non-current assets and the reason behind it is that current assets are easily converted into cash within one year and they are not.

    • The sole purpose of buying fixed assets like the land is that they are planned to be used for the long term in order to generate income.
    • Examples of fixed assets – Land, buildings, furniture, plants & equipment, etc.
    • Also called non-current assets and capital assets.


    Why is it shown on the asset side?

    The land is an asset, although it is not depreciable it is still considered to be an asset because just like other assets the business spends its own money to acquire it, and it gives them a long-term benefit while reselling it.

    Therefore, the land is shown on the asset side under the fixed asset heading.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

Journal is a book of which entry?

A. Original B. Duplicate C. Personal D. Nominal

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 12, 2021 at 4:57 pm

    The correct option is (A) Original. Journal entry is the book of the original entry. It is because every event or transaction which is of monetary nature is first recorded in the journal. The transactions recorded in the journal are known as journal entries. Journal follows the double-entry system oRead more

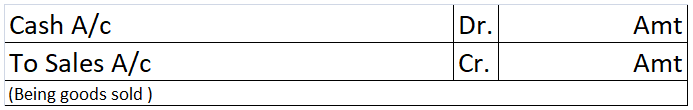
    The correct option is (A) Original. Journal entry is the book of the original entry. It is because every event or transaction which is of monetary nature is first recorded in the journal. The transactions recorded in the journal are known as journal entries.

    Journal follows the double-entry system of accounting. It means a journal entry affects at least two accounts. It is from the journal entries, the ledger accounts are prepared. For example, the transaction, ‘sale of goods for Rs 1000 for cash’ affects two accounts. The journal entry is:

    There are many special journals that record some special set of transactions which are called subsidiary journals or daybooks. Such special journals are not considered the books of original entry.

    Option (B) Duplicate is wrong. It is because the journal is the book where monetary events and transactions are recorded. It cannot be the book of duplicate entries. There is no such thing as ‘book of duplicate entry.’

    Option (C) Personal is wrong. Personal is a type of account under the golden rules of accounting. A personal account is a type of account that represents a person. But, the journal is not an account, it is a book. Also, there is no such thing as book of personal entry.

    Option (D) Nominal is wrong. Nominal is also a type of account under the golden rules of accounting. The nominal account is a type of account that represents an income, expense, gain or loss. Journal is a type of account but a book.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is a contra account?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on December 6, 2021 at 8:43 pm

    A contra account is a general ledger account that is used to reduce the value of the account related to it. Basically, a contra account is the opposite of its associated account. If the associated account has a debit balance, then the contra account would have a credit balance. They are used to mainRead more

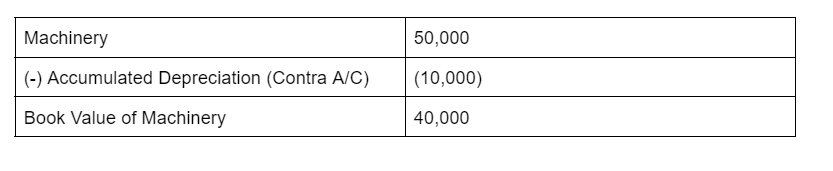
    A contra account is a general ledger account that is used to reduce the value of the account related to it. Basically, a contra account is the opposite of its associated account. If the associated account has a debit balance, then the contra account would have a credit balance. They are used to maintain the historical value of the main account while all the deductions are recorded in the contra account, which when clubbed together show the net book value.

    For example

    if the cost of machinery was Rs. 50,000 and the company wants to preserve its original cost, then the accumulated depreciation of such machinery is recorded separately. Let’s say Rs 10,000 was the accumulated depreciation. Then such amount is recorded in the contra account named accumulated depreciation account. This makes the net value of the machinery Rs 40,000.

    Types

    There are various types of contra accounts such as contra asset, contra equity, contra revenue, and contra liability.

    • Contra asset: these accounts have credit balances and are used to reduce the balance of an asset. Eg, Accumulated depreciation.
    • Contra Liability: These accounts have debit balances and are used to reduce the balance of liabilities. Eg, discount on notes.
    • Contra equity: These accounts have a credit balance and are used to reduce the number of shares outstanding which in turn reduces equity. Eg treasury stock.
    • Contra revenue: These accounts have a debit balance. They reduce gross revenue which results in net revenue. Eg sales return.

    Accountants make use of contra accounts instead of reducing the value of the actual account to keep the financial statements clean.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

What is a prepaid payable?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 14, 2022 at 2:55 pm
    This answer was edited.

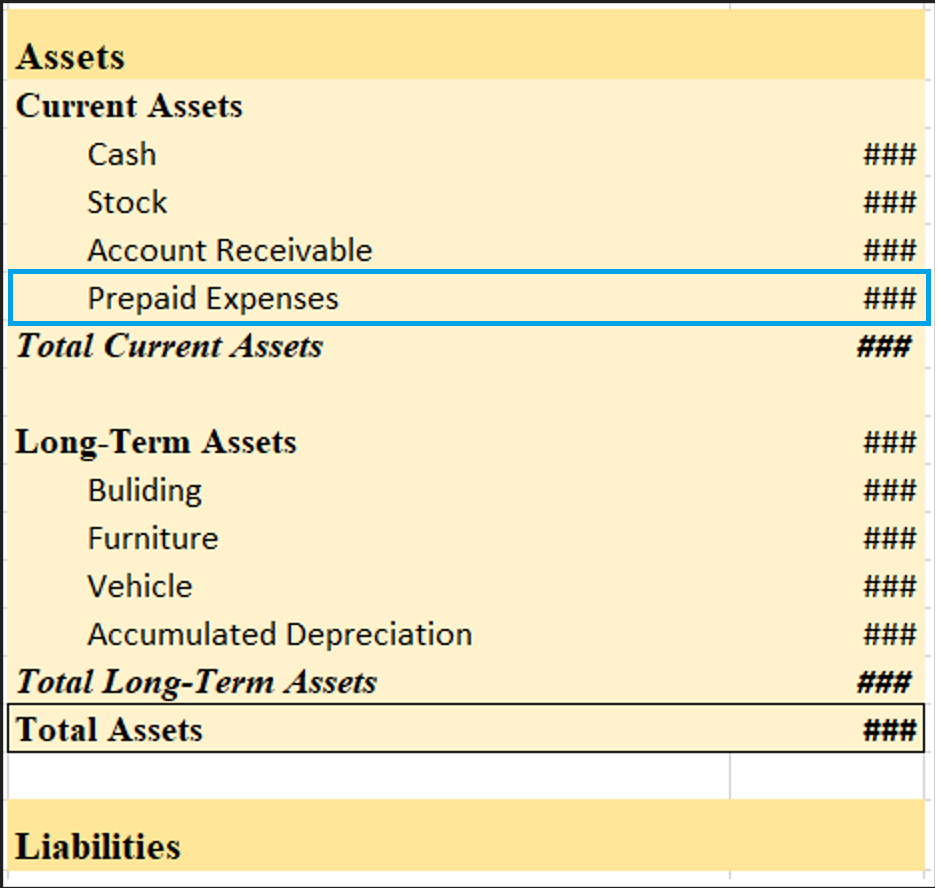
    Prepaid Payable Prepaid payable or prepaid expenses refer to the future expenses that have been paid in advance. It is an advance payment made by the business for the goods and services to be received by the business in the future. A prepaid expense is an asset on the balance sheet. The number of prRead more

    Prepaid Payable

    Prepaid payable or prepaid expenses refer to the future expenses that have been paid in advance. It is an advance payment made by the business for the goods and services to be received by the business in the future.

    A prepaid expense is an asset on the balance sheet. The number of prepaid expenses that will be used up within one year is reported on a company’s balance sheet as a current asset. According to generally accepted accounting principles (GAAP), expenses should be recorded in the same accounting period as the benefit generated from the related asset.

    Example

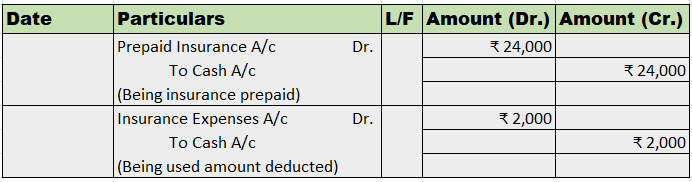
    ABC Ltd. purchases insurance for the warehouse. It was ₹2,000 per month. The company pays ₹24,000 in cash upfront for a 12-month insurance policy for the warehouse. Each month an adjusting journal entry will be passed, adjusting the amount of insurance used from the prepaid insurance.

    Journal Entry-

    Prepaid Expenses in Balance Sheet-

    Prepaid expenses are shown in the balance sheet under the current assets heading as it’s a short-term asset and to be consumed within one accounting year.

    Balance Sheet (for the year ending…)

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Miscellaneous

How are contingent assets different from contingent liabilities ?

  • 1 Answer
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Contingent Asset is an asset the existence, ownership, or value of which may be known or determined only on the occurrence or non-occurrence of one or more uncertain future events. However, the difference between Contingent assets is not disclosed whereas Contingent liabilities are discloRead more

    Definition

    Contingent Asset is an asset the existence, ownership, or value of which may be known or determined only on the occurrence or non-occurrence of one or more uncertain future events.

    However, the difference between Contingent assets is not disclosed whereas Contingent liabilities are disclosed by way of notes they do have different criteria for recognition which are discussed below.

    For example:– a claim that an enterprise is pursuing through the legal process, where the outcome is uncertain, is a contingent asset.

    Contingent liabilities are defined as obligations relating to existing conditions or situations which may arise in the future depending on the occurrence or non-occurrence of one or more uncertain events.

    For example:- Billis discounted but not yet matured, arrears of dividend on cum –preferences-shares, etc.

    Meaning as per AS – 29

    Now let me try to explain to you the meaning according to Accounting Standard 29 of the above contingent assets and liabilities which is as follows:-

    • Contingent asset

    A contingent asset is a possible asset that arises from past events the existence of which will be confirmed only by the occurrence or non-occurrence of one or more uncertain future events.
    Not wholly within the control of the enterprise.

    It usually arises from unplanned or unexpected events that give rise to the possibility of an inflow of economic benefits to the enterprise.

    • Contingent liability

    A possible obligation that arises from past events the existence of which will be confirmed only by the occurrence or non-occurrence of one or more uncertain future events.
    Not wholly within the control of the enterprise.

    A present obligation that arises from past events but is not recognized because it is not probable that the outflow of resources embodying economic benefits will be required to settle the obligation or,
    A reliable estimate of the amount of obligation cannot be made.

    Recognition In Financial Statements

    Contingent assets and liabilities are recognized as follows:-

    • Contingent Assets

    As per the prudence concept s well as present accounting standards, an enterprise should not recognize a contingent asset.

    It is possible that the recognition of contingent assets may result in the recognition of income that may never be realized.

    However, when the realization of income is virtually certain, the related asset no longer remains contingent.

    • Contingent liability

    As per the rules, it is not recognized by an enterprise.

    When recognized?

    Contingent assets are assessed continually and if it has become virtuality an outflow of economic benefits will arise.

    The assets and the related income are recognized in the financial statements of the period in which the change occurs.

    Contingent liability is assessed continually to determine whether an outflow of resources embodying economic benefits has become probable.

    And if it becomes probable that an outflow or future economic benefits will require for an item previously dealt with as a contingent liability.

    A provision is recognized in financial statements of the period in which the change probability occurs except in extremely rare circumstances where no reliable estimate can be made.

    Disclosure

    Now we will see how contingent assets and liability are disclosed which is mentioned below:-

    • Contingent asset

    These contingent assets are not disclosed in financial statements.
    A contingent asset is usually disclosed in the report of the approving authority ( ie.e., Board Of Directors in the case of a company, and the corresponding approving authority in case of any enterprise), if ab inflow of economic benefits is probable.

    • Contingent Assets

    A contingent liability is required to be disclosed by way of a note to the balance sheet unless the possibility of an outflow of a resource embodying economic benefit is remote.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Financial Statements

What is debit side of trading account?

  • 1 Answer
  • 0 Followers
Answer
  1. Kajal
    Added an answer on September 20, 2023 at 4:41 pm
    This answer was edited.

    Trading A/c is a nominal account which follows the rule "Debit all expenses and losses, Credit all incomes and gains". So, all expenses relating to the purchase or manufacturing of goods are shown on the debit side of the Trading A/c. It includes Opening Stock, Purchases, Wages, Carriage Inward, ManRead more

    Trading A/c is a nominal account which follows the rule “Debit all expenses and losses, Credit all incomes and gains”.

    So, all expenses relating to the purchase or manufacturing of goods are shown on the debit side of the Trading A/c. It includes Opening Stock, Purchases, Wages, Carriage Inward, Manufacturing Expenses, Dock charges, and other direct expenses that are directly related to the manufacturing or purchase.


    TRADING ACCOUNT

    Trading A/c is prepared for calculating the Gross Profit or Gross Loss arising from the trading activities of a business.

    Trading activities are mostly related to buying and selling of goods. However, in between buying and selling, a lot of activities are involved like transportation, warehousing, etc. So, all the expenses that are directly related to manufacturing or purchase of goods are also recorded in the Trading A/c.


    DEBIT SIDE OF TRADING A/C

    The items shown on the Dr. side are,

    OPENING STOCK – Stock is nothing but goods that are either obtained for resale or manufactured for sale and are yet unsold on any particular date.

    The value of stock at the beginning of an accounting year is called Opening stock while the value of the stock at the end of an accounting year is called closing stock.

    The closing stock of the last year becomes the opening stock of the current year.

    Opening stock includes,

    1. Opening Stock of Raw materials
    2. Opening Stock of Semi-finished goods
    3. Opening Stock of Finished goods

    For example – Suppose you are in the business of manufacturing and trading shirts. On 31st March 2023, there was unused raw material worth $10,000 and shirts worth $50,000 remained unsold.

    So, we have Closing Stock of Raw material – $10,000

    Closing Stock of Finished Goods – $50,000

    This closing stock of last year becomes your opening stock during the current year i.e. on 1st April 2023, we have

    Opening Stock of raw material – $10,000

    Opening Stock of Finished Goods – $50,000

    PURCHASES – Goods that have been bought for resale or raw materials purchased for manufacturing the product are terms as Purchases. These goods must be related to the business you are doing.

    It includes cash as well as credit Purchases.

    Continuing with the above example, suppose you bought raw material worth $ 1,00,000 for manufacturing and shirts worth $50,000 for resale (and not for personal consumption) then both these will be termed as purchases for you. So, your purchases will be $1,50,000 ($1,00,000 + $50,000)

    PURCHASES RETURN – When goods bought are returned to the suppliers due to any reason. This is known as Purchase return. Purchase return is deducted from the Purchases.

    In the above example, you bought shirts worth $50,000 for resale. Out of which shirts worth $20,000 were defective. So, you returned them to the supplier. This return of $20,000 is your purchase return or return outwards (as goods are going out)

    WAGES – Wages are paid to the workers who are directly engaged in the loading, unloading and production of goods.

    For example – Paid $10,000 to workers for manufacturing shirts.

    However, it would be included in Trading A/c only if the wages are paid for work which is directly related to the manufacturing or purchase of goods otherwise it will be shown in P&L A/c.

    Suppose you hired a manager to take care of your business and paid him $20,000 as salary. This salary is indeed an expense for the business but is not directly related to the manufacturing of goods. Since it is an indirect expense, it can only be recorded in P&L  A/c and not in the Trading A/c.

    CARRIAGE or CARRIAGE INWARDS or FREIGHT – It refers to the cost of transporting goods from the supplier.

    Suppose, you ordered raw material in bulk which was transported to you by a van and you paid its fare. This fare is nothing but your carriage inwards.

    However, if carriage or freight is paid on bringing an asset, the amount should be added to the asset account and must not be debited to the trading account.

    MANUFACTURING EXPENSES – All expenses incurred in the manufacture of goods such as  Coal, Gas, Fuel, Water, Power, Factory rent, Factory lighting etc.

    DOCK CHARGES – These are charged by port authorities when unloading goods at a dock or wharf. Such charges paid in connection with goods purchased are considered direct expenses and are debited to Trading a/c.

    IMPORT DUTY or CUSTOM DUTY – It is a tax collected on imports and specific exports by a country’s customs authorities. If import duty is paid on the import of goods, then they are shown on the Dr. side of the Trading A/c.

    For example –  Paid $15,000 as import duty for importing shirts for resale.

    ROYALTY – Royalty refers to the amount paid for the use of assets belonging to another person. It includes royalty for the use of intangible assets, such as copyrights, trademarks, or franchisee agreements. It is also paid for the use of natural resources, such as mining leases.

    Royalty is charged to the Trading A/c as it increases the cost of production.

    GROSS PROFIT – When sales exceed the amount of purchases and the expenses directly connected with such purchases i.e. when Credit side> Debit side.


    CREDIT SIDE OF TRADING A/C

    SALES – When goods are sold to earn a profit, it is called sales. It can be cash sales or credit sales.

    SALES RETURN – When the goods sold are returned by the customer, it is known as a sales return. Sales return is deducted from the sales.

    CLOSING STOCK – The goods remaining unsold at the end of the year are termed as closing stock. It is valued at cost price or market price whichever is less.

    GROSS LOSS – If purchases and direct expenses exceed sales, then it is a Gross loss. In other words, when Debit side > Credit side.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SAMKV
SAMKVCurious
In: 1. Financial Accounting > Journal Entries

PASS THE JOURNAL ENTRIES (WHICH SHOULD HAVE AT LEAST 20 TRANSACTIONS WITH GST) POST THEM INTO THE LEDGER, PREPARE A TRIAL BALANCE BY BALANCE METHOD-

  • 0 Answers
  • 0 Followers
Answer
Aditi
Aditi
In: 1. Financial Accounting > Miscellaneous

How are Research & Development costs treated in financial statements?

  • 1 Answer
  • 0 Followers
Answer
  1. Mehak
    Added an answer on January 14, 2025 at 4:30 am
    This answer was edited.

    Every business requires research and development to create innovative products for consumers. More innovative and creative products and services are more popular among customers, leading to increased revenue and profits for the business. Creating new products or designing changes and testing existinRead more

    Every business requires research and development to create innovative products for consumers. More innovative and creative products and services are more popular among customers, leading to increased revenue and profits for the business.

    Creating new products or designing changes and testing existing products also forms a part of research and development.

    Examples of Research and Development costs are –

    1. Salaries of employees
    2. Cost of making prototypes
    3. Cost of raw material
    4. Overhead expenses

    Let us now understand how research and development costs are treated in Financial Statements.

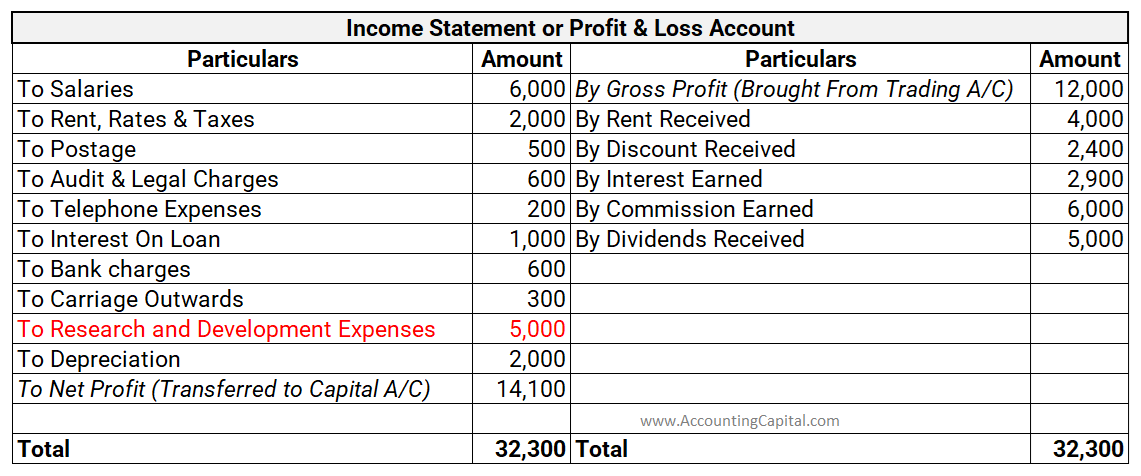
    Research and Development Costs are generally shown as an expense in the Income Statement.

    IAS-38

    IAS-38 majorly governs the accounting of research and development costs. There are two phases in R&D:

    • Research: During this phase, costs are incurred for understanding or designing the product. These costs are expensed as incurred costs as there is an uncertainty of a future benefit.
    •  Development: Economic value can be ascertained during this phase and hence, the costs incurred can be capitalized as Intangible assets. To be recognised as intangible assets, the following conditions shall be satisfied:

    1. it is developed with the intention of putting it to use in the future

    2.  the asset shall hold an economic value

    3. the costs can be measured reliably

    Treatment of R&D costs in the Financial statements:

      1. Income statement: Research costs are shown as expenses in the income statement. However, development costs if capitalized as intangible assets can be amortised over time.
      2. Balance Sheet: Capitalised development costs are shown as intangible assets under the Assets head of the Balance Sheet.

    Conclusion

    The above discussion can be summarised as follows:

    1. Research and development is essential for creating innovative and creative products and services.
    2. Accounting standard IAS-38 governs the accounting for Research and Development.
    3. Research costs are usually shown as an expense in the Income statement of the business.
    4.  Development costs when capitalised can be shown as Intangible assets in the Balance Sheet.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.