

A contra account is a general ledger account that is used to reduce the value of the account related to it. Basically, a contra account is the opposite of its associated account. If the associated account has a debit balance, then the contra account would have a credit balance. They are used to mainRead more
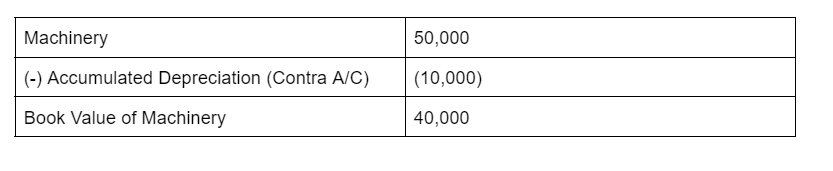
A contra account is a general ledger account that is used to reduce the value of the account related to it. Basically, a contra account is the opposite of its associated account. If the associated account has a debit balance, then the contra account would have a credit balance. They are used to maintain the historical value of the main account while all the deductions are recorded in the contra account, which when clubbed together show the net book value.
For example
if the cost of machinery was Rs. 50,000 and the company wants to preserve its original cost, then the accumulated depreciation of such machinery is recorded separately. Let’s say Rs 10,000 was the accumulated depreciation. Then such amount is recorded in the contra account named accumulated depreciation account. This makes the net value of the machinery Rs 40,000.
Types
There are various types of contra accounts such as contra asset, contra equity, contra revenue, and contra liability.
- Contra asset: these accounts have credit balances and are used to reduce the balance of an asset. Eg, Accumulated depreciation.
- Contra Liability: These accounts have debit balances and are used to reduce the balance of liabilities. Eg, discount on notes.
- Contra equity: These accounts have a credit balance and are used to reduce the number of shares outstanding which in turn reduces equity. Eg treasury stock.
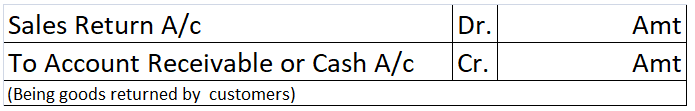
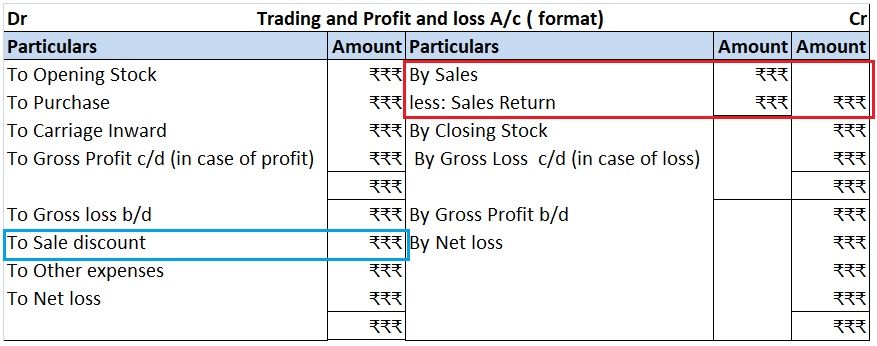
- Contra revenue: These accounts have a debit balance. They reduce gross revenue which results in net revenue. Eg sales return.
Accountants make use of contra accounts instead of reducing the value of the actual account to keep the financial statements clean.
See less










The terms outstanding expenses and accrued expenses are two accounting terms which are often used interchangeably. However, these two terms are not the same and have different meanings. The difference between these two terms is given below: What are Outstanding expenses? As the name suggests, outstaRead more
The terms outstanding expenses and accrued expenses are two accounting terms which are often used interchangeably. However, these two terms are not the same and have different meanings. The difference between these two terms is given below:
What are Outstanding expenses?
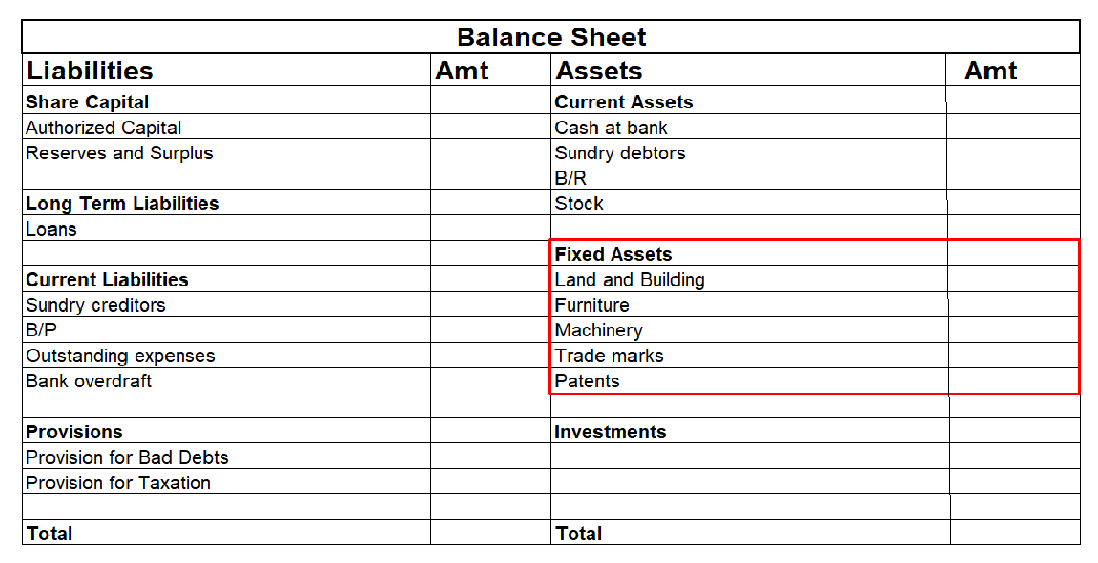
As the name suggests, outstanding expenses are the expenses that are due but have not been paid yet. It means that the business is supposed to pay the amount due but it has not paid the same at the end of the accounting period.
Outstanding expenses are recognized as a current liability because the business is liable to pay such expenses. These expenses are recorded in the books of accounts but the payment is still pending.
Some examples of outstanding expenses are:
What are Accrued expenses?
Accrued expenses are the expenses that a business has incurred during the accounting period but they have not yet been recorded in the books of accounts because the bill has not yet been received or the payment is not due yet.
The concept of Accrued expenses helps in complying with the accrual basis of accounting which says that the expense shall be recognised at the time it occurs regardless of the fact that payment is received or not.
Examples of accrued expenses are:
Key differences between outstanding expenses and accrued expenses
To summarise the above discussion, the key differences between outstanding expenses and accrued expenses are given in the table below:
See less