

Miscellaneous expenditure in the balance sheet The expenses that are written off in the current financial year are shown on the debit side of the profit and loss account. However, those that are not written off during the current financial year are shown in the balance sheet on the Assets Side as MiRead more
Miscellaneous expenditure in the balance sheet
The expenses that are written off in the current financial year are shown on the debit side of the profit and loss account. However, those that are not written off during the current financial year are shown in the balance sheet on the Assets Side as Miscellaneous expenditure.
Miscellaneous expenditure are those expenses that are not categorized as Operating expenses i.e. these are not classified as manufacturing, selling, and administrative expenses.
For example, BlackRock has spent 5,00,000 which will be written of in 5 consecutive years as an Advertisement expense. During the current financial year, only 1,00,000 will be written off and the rest will be carried to the next year and year thereafter.
Treatment in the first year:
- 1,00,000 which is written off during the current financial year will be shown on the debit side of the Profit and Loss account.
- 4,00,000 which is carried forward will be shown on the assets side of the balance sheet as miscellaneous expenditure because all assets and expenses have a debit balance.
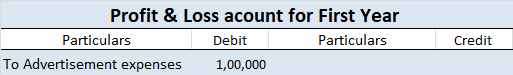
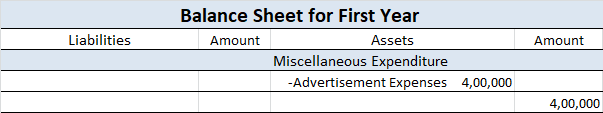
Treatment in the second year:
- 1,00,000 which is written off during the current financial year will be shown on the debit side of the Profit and Loss account.
- 4,00,000 which is carried forward will be shown in the assets side of the balance sheet as a miscellaneous expenditure.
The same will be done in the third, fourth, and fifth years.
Conclusion
Deferred revenue expenditure is also a long-term expenditure the benefit of which cannot be derived within the same year. So the amount that is written off during the current year is shown on the debit side of the profit and loss account and the amount which is not written off during the current financial year is shown on the assets side under the head Miscellaneous expenditure.
See less








Definition Bad debts are a debt owed to an enterprise that is considered to be irrecoverable or we can say that it is owed to the business that is written off because it is irrecoverable. Bad debts will be treated in the following ways : On the debit side of the profit and loss account. In the curreRead more
Definition
Bad debts are a debt owed to an enterprise that is considered to be irrecoverable or we can say that it is owed to the business that is written off because it is irrecoverable.
Bad debts will be treated in the following ways :
On the debit side of the profit and loss account.
In the current assets side of the balance sheet, these are deducted from sundry debtors.
For example loans from banks are declared as bad debt, sales made on credit and amounts not received from customers, etc.
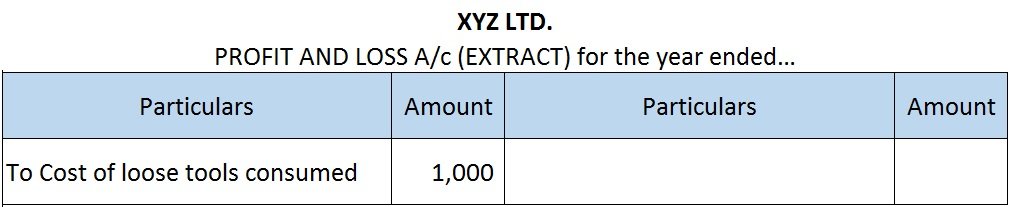
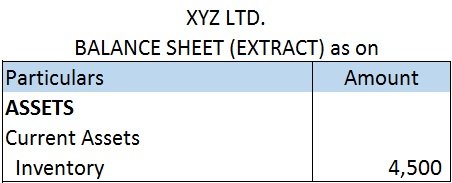
Now I will show you an extract of the profit and loss account and balance sheet
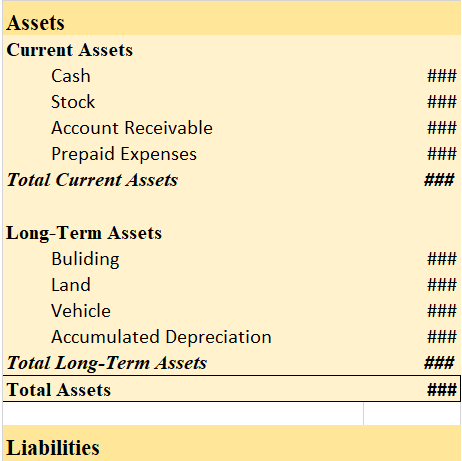
Current assets are defined as cash and other assets that are expected to be converted into cash or consumed in the production of goods or the rendering of services in the ordinary course of business.
For example, debtors exist to convert them into cash i.e., receive the amount from them, bills receivable exist again for receiving cash against it, etc.
Current liabilities are defined as liabilities that are payable normally within 12 months from the end of the accounting period or in other words which fall due for payment in a relatively short period.
For example bills payable, short-term loans, etc.
Accounting treatment
Now let me try to explain to you the accounting treatment for bad debts which is as follows :
Reasons for bad debts
There are several reasons why businesses may have bad debts some of them are as follows:-
Accounting methods
There are two methods for accounting for bad debts which are mentioned below:-
Related terms
So there are a few related terms whose meanings you should know
See less