Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

Is accrual the same as provision?

  • 2 Answers
  • 0 Followers
Answer
  1. Saurav
    Added an answer on October 5, 2023 at 7:07 am

    Accruals are not the same as provisions both are totally different from each other. Accruals and provision both are vital parts of accounts but work differently   Accrual Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irreRead more

    Accruals are not the same as provisions both are totally different from each other. Accruals and provision both are vital parts of accounts but work differently


    Accrual

    Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irrespective of the fact when such an amount has been paid.

    An accrual of the expenditure which is not paid will be listed in the books of accounts. These accruals can be further divided into two parts


    Accrual Expense

    Accrual Expense means any transaction that takes place in a particular period but the amount for it will be paid on a later period.

    For example- 10,000 for the month of March was paid in April month then this rent will be accounted for in the books in March

    These are the following accrued expense

    • Accrual Rent– Accrual rent means the amount for using the land of the landlord is paid at a later period than the period when it is put into use.
    • Insurance– Accrual insurance means the amount paid as a premium to the insurance company paid on a later period than the period when it is due
    • Expense- Acrrual expense means the amount for any expense paid on a later period then the period when it pertains to be paid
    • Wages- Accrual wages means the amount which is paid to employees on a later period than the period when the wages get due


    Accrual Revenue

    Accrual Revenue means any transaction that takes place in a particular period but the amount for it will be received on later period. For example- If interest of 10,000 on bonds for the period of March is received in April months then this amount will be accounted for in March. These are the following accrued revenue

    • Accrual Rent– Accrual rent means the amount for using the land of an entity by another party is received on a later period than the period when it was put into use.
    • Accrued Interest– Accrued interest means the amount of interest received on a later period than the period when it pertains to receive


    PROVISIONS

    Provision refers to making a provision/allowance against any probable future expense that the company might incur in the near future. This amount is uncertain and difficult to predict its surety.

    However, as per the prudence concept of accounting a company needs to anticipate the losses that will incur in the near future due to which provision is made.

    For example- A company has debtors of 10,000 but as per the company’s previous records company anticipates that 1% of debtors will become bad debts. So in this case company will make a provision of 1% that is 100 on it.

    There are various types of provisions which are-

    • Provision on Depreciation– Provision for Depreciation means a provision for future depletion of assets has been already created
    • Provision for Doubtful Debts– Provision for Doubtful Debts means a provision created against debtors that doesn’t seem to be recovered in the near future
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Miscellaneous

What are some examples of deferred revenue expenses?

  • 2 Answers
  • 0 Followers
Answer
  1. Kajal
    Added an answer on November 22, 2023 at 7:33 am

    All expenses whose benefits are received over the years or the expenses or losses that are to be written off over the years are classified as Deferred revenue expenses. It includes fictitious expenses like preliminary expenses, loss on issue of debentures, advertising expenses, loss due to unusual oRead more

    All expenses whose benefits are received over the years or the expenses or losses that are to be written off over the years are classified as Deferred revenue expenses. It includes fictitious expenses like preliminary expenses, loss on issue of debentures, advertising expenses, loss due to unusual occurrences like loss due to fire, theft, and research and development expenses, etc. 


    DEFERRED REVENUE EXPENSES

    There are certain expenses which are revenue in nature (i.e. expenses incurred to maintain the earning capacity of the firm and generate revenue) but whose benefits are received over a period of years generally between 3 to 7 years. It means its benefit is received not only in the current accounting period but over a few consecutive accounting periods.

    CHARACTERISTICS

    • Revenue in nature
    • Benefits received for more than one accounting period.
    • Huge expenditure (large amount is involved)
    • Affects the profitability of the business (since a large amount is involved if charged in the same accounting period, then it will decrease the profitability for the year)
    • Written off over the years either partially or entirely.
    • Fictitious asset It doesn’t result in the creation of any asset but is shown as an asset (fictitious asset) on the Balance Sheet till fully written off.


    EXAMPLES


    ADVERTISING EXPENSES refers to the expenses incurred for promoting the goods or services of the firm through various channels like TV, Social media, Hoardings, etc.

    As the benefit of advertising is not received not only in the period when such expenses were incurred but also in the coming few years, it is classified as Deferred revenue expense.

    For example – Suppose the company incurred $10 lakh on advertising to introduce a new product in the market and estimated that its benefit will last for 4 years. In this case, $250,000 will be written off every year, for 4 consecutive years.


    EXCEPTIONAL LOSSES are losses that are incurred because of some unusual event and don’t happen regularly like loss from fire, theft, earthquake, flood or any other natural disaster, confiscation of property, etc.

    Since these losses can’t be written off in the year they occurred they are also treated as Deferred revenue expenditure and are written off over the years.


    RESEARCH AND DEVELOPMENT EXPENSES are expenses incurred on researching and developing new products or improving the existing ones. Its benefits are received for many years and thus are classified as Deferred revenue expenses.

    For example – Expenses incurred on the creation of intangible assets like patents, copyrights, etc.


    PRELIMINARY EXPENSES are those expenses which are incurred before the incorporation and commencement of the business. It includes legal fees, registration fees, stamp duty, printing expenses, etc.

    These expenses are fictitious assets and are written off over the years.


    TREATMENT

    It is debited to the P&L amount (amount written off that year) and the remaining amount on the Aeest side of the Balance Sheet.

    In the above example of advertising expenses, in Year 1, $250,000 will be debited in the P&L A/c and the remaining amount of $750,000 is shown on the Asset side of the Balance Sheet.

    In Year 2, $250,00 in P&L A/c and the remaining $500,000 in Balance Sheet.

    In Year 3, $250,000 in P&L A/c and the remaining $250,000 in the Balance Sheet and in the last Year 4, only the remaining amount of $250,000 in P&L A/c and nothing in the Balance Sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Miscellaneous

Is Land a Current Asset?

Current Assets
  • 2 Answers
  • 0 Followers
Answer
  1. Bonnie Curious MBA (Finance)
    Added an answer on June 27, 2021 at 5:34 am
    This answer was edited.

    Similarly, someone asked Are loose tools current assets

    Similarly, someone asked Are loose tools current assets

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

Prepaid expenses is current assets or current liabilities?

  • 2 Answers
  • 0 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on January 5, 2023 at 8:58 am
    This answer was edited.

    Definition Prepaid expenses are those expenses whose payments are done in advance which can be for the goods or services whose benefit will accrue in the subsequent accounting period. A prepaid expense is a current asset. prepaid expenses are classified under the head current assets in the balance sRead more

    Definition

    Prepaid expenses are those expenses whose payments are done in advance which can be for the goods or services whose benefit will accrue in the subsequent accounting period.

    A prepaid expense is a current asset. prepaid expenses are classified under the head current assets in the balance sheet.

    This is because they provide future economic benefits to the company. As such, they are assets that can be used to generate revenue in the future.

    For example prepaid rent, prepaid insurance, etc.


    Current assets are defined as cash and other assets that are expected to be converted into cash or consumed in the production of goods or rendering of services in the normal course of business.

    Or in other words, we can say that the expected realization period is less than the operating cycle period although it is more than the period of 12 months from the date of the balance sheet.

    For example, goods are purchased with the purpose to resell and earn a profit, debtors exist to convert them into cash i.e., receive the amount from them, bills receivable exist again for receiving cash against it, etc.


    Current liabilities are liabilities that are payable generally within 12 months from the end of the accounting period or in other words which fall due for payment in a relatively short period.

    For example bills payable, short-term loans, etc.


    Why current assets and not a  current liability?

    Now let me try to explain to you that prepaid expenses are classified as current assets  and not as a current liability which is as follows :

      • we can say that the expected realization period is less than the operating cycle period although it is more than the period of 12 months from the date of the balance sheet.
      • expected to be converted into cash or consumed in the production of goods or rendering of services in the normal course of business.
      • In the business prepaid expense are treated as an asset which we can see on the asset side of the balance sheet.
      • Or in other words, we can say that it is initially recorded as a prepaid expense as an asset in the balance sheet and subsequently its value is expensed over time in the profit and loss account.


    Example

    Now let us take an example for explaining prepaid expenses which are mentioned below.

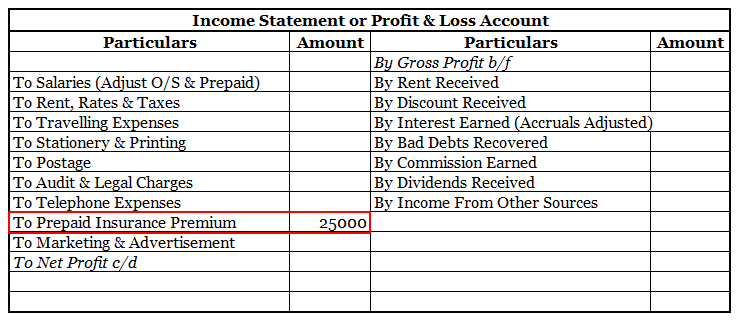
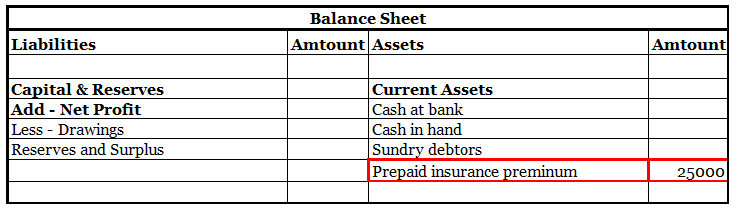
    An insurance premium of Rs 50000 has been paid for one year beginning (previous year). The financial year ends on 31st  march YYYY.

    It means the premium for 6 months i.e., 1st April, YYYY(current year) to 30th September, YYYY(current year) amounting to Rs 25000 is paid in advance.

    Thus, of premium paid in advance (Rs 25000)  is a Prepaid Expense. It will be accounted as an expense in the financial year ending  31st  march next year. In the balance sheet as of 31st march YYYY ( current year ) it will be shown as Current Asset.

    Here is an extract of the profit /loss account and balance sheet of the above example:


    Key points

    There are a few things to keep in mind when dealing with prepaid expenses.

    • First, is that the expenses are actually prepaid. This means that the expenses were paid for before they were used.


    • Second, it is essential to track the number of prepaid expenses that have been used. That is to make sure that the prepaid expenses are not overstated on the company’s financial statements. This can happen if the company pays for more goods or services than it actually


    • Last but not least it is important to keep in mind that changes in the value of prepaid expenses can impact the company’s net income. For example, if the company’s prepaid insurance increases in value, this will increase the company’s net income.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Vijay
VijayCurious
In: 1. Financial Accounting > Miscellaneous

What is useful life of assets as per the Companies Act?

Companies Act
  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on July 5, 2021 at 6:54 pm
    This answer was edited.

    Simply explaining the meaning of the useful life of an asset, it is nothing but the number of years the asset would remain in the business for purpose of revenue generation, making it more simple, the amount of time an asset is expected to be functional and fit for use.  It is also called economic lRead more

    Simply explaining the meaning of the useful life of an asset, it is nothing but the number of years the asset would remain in the business for purpose of revenue generation, making it more simple, the amount of time an asset is expected to be functional and fit for use.  It is also called economic life or service life

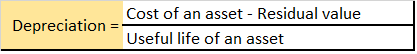
    It is a useful concept in accounting as it is used to work out depreciation. By knowing this useful life of an asset an entity can easily analyze how to allot the initial cost of an asset across the relevant accounting period rather than doing it unfairly manner.

    How do we calculate the useful life of an asset?

    The useful life of an asset is not an accounting policy, but an accounting estimate. calculating useful life is not an exact phenomenon but an estimate that is done because it directly impacts how much an asset is to expense every year.

    Factors affecting “how long an asset is expected to be useful” depends on some stated points as below:

    1. Usage, the more the assets are used, the more quickly it will deteriorate.
    2. Whether the asset is new at the time of purchase or reused model.
    3. Change in technology.

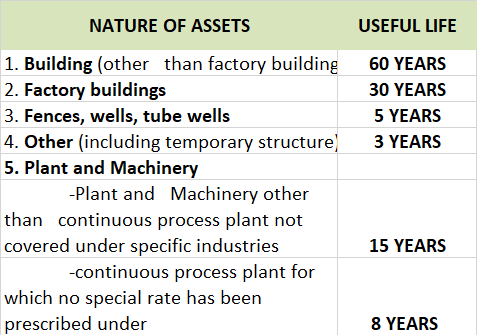
    As per the companies act 2013, some of the useful life of assets are stated below

    To know more about the different categories of assets you can follow the given link useful life of assets.

    POINT TO BE NOTED:- There lies a huge difference in the useful life v/s the physical life of an asset. It is very important to note that amount of time an asset is used in a business is not always be same as an asset’s entire life span.


    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Miscellaneous

Is capital work in progress a tangible asset?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on December 7, 2021 at 4:37 pm
    This answer was edited.

    Yes, Capital Work in Progress is Tangible Asset. To attain an understanding of the same, we first need to understand what are tangible assets. Assets that have a physical existence, that is they can be seen, touched are called Tangible Assets. Capital work in progress is the cost incurred on fixed aRead more

    Yes, Capital Work in Progress is Tangible Asset.

    To attain an understanding of the same, we first need to understand what are tangible assets. Assets that have a physical existence, that is they can be seen, touched are called Tangible Assets.

    Capital work in progress is the cost incurred on fixed assets that are under construction as on the balance sheet date. Since the asset cannot be used for operation it cannot be classified as a Fixed Asset.

    For example:

    If an asset takes 1.5 years to be constructed as on 1.4.2020 then on the balance sheet date 31.3.2021, the cost incurred on the asset will be classified as Capital Work in Progress.

    Common examples of Capital Work in Progress include immovable assets like Plant and Machinery, Buildings.

    It is shown under the head Non-Current Assets in the balance sheet. Examples of cost included in Capital Work in Progress can be:

    • Advance payment to the contractor
    • Material used/purchased
    • Cost of labor incurred, etc.

    Since the assets under the head Capital Work in Progress are in the process of completion and not completed, hence they are not depreciable until completed. Once the asset is completed it is moved under the head Fixed Assets.

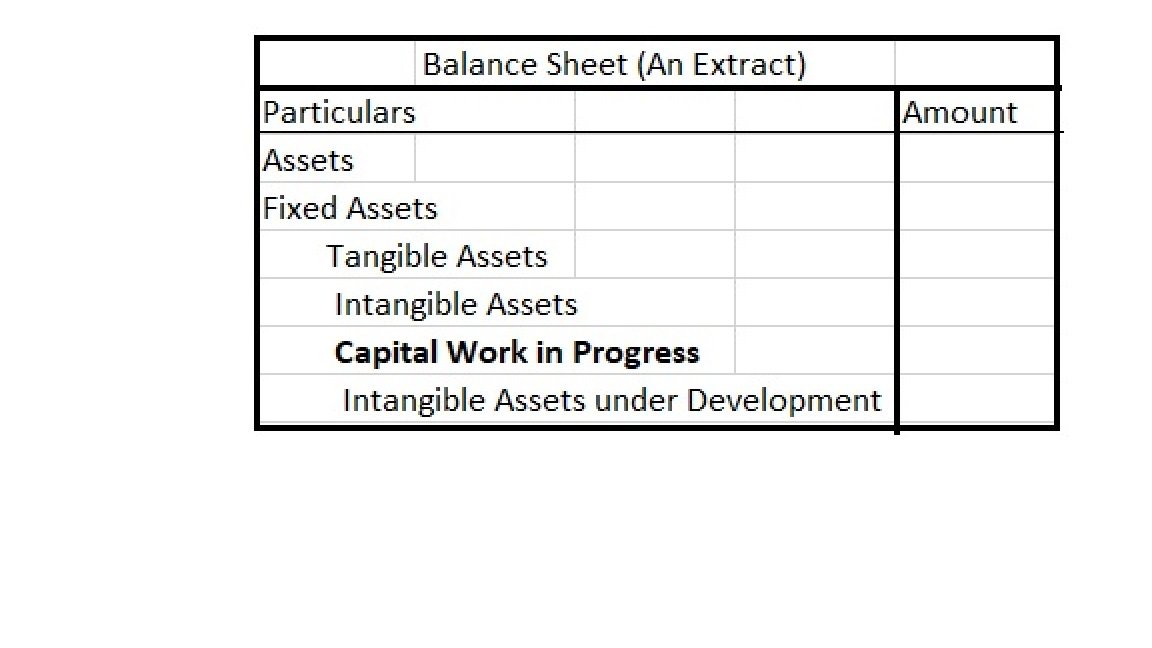
    Capital Work in Progress is shown in the Balance Sheet as:


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Miscellaneous

What is the difference between ledger and subledger?

  • 1 Answer
  • 7 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition A ledger may be defined as a book that contains, in a summarized and classified form, a permanent record of all transactions. Or in other words, we can say a group of accounts with different characteristics. It is also called the Principal Book of accounts. For example:- salary account, aRead more

    Definition

    A ledger may be defined as a book that contains, in a summarized and classified form, a permanent record of all transactions.

    Or in other words, we can say a group of accounts with different characteristics.

    It is also called the Principal Book of accounts.

    For example:– salary account, and debtor account.

    Sub- ledger it is defined as a group of accounts with common characteristics. And is a part of ledger accounts.

    For example:- customer account, vendor account, etc.

    The difference between a ledger and a sub-ledger is that ledger accounts control sub-ledger accounts whereas a sub-ledger is a part of the ledger account.

    Features Of Ledger

    • Ledger is prepared from the journal.
    • Ledger is a master record of all the accounts of the business.
    • The Ledger account shows the current balances of all accounts.
    • Ledger accounts summarize the effect of transactions upon assets, liabilities, capital, incomes, and expenditures.

    Features Of Sub-Ledger

    • Sub-ledger in accounting provides up-to-date information about the daily activities of the business.
    • It keeps individual track of all balances.
    • Help locate errors in individual accounts.
    • A sub-ledger is a collection of different ledgers used in an account.


    Utilities of ledger

    The main utilities of a ledger are summarized as follows :

    • Provides complete information about a particular account: Complete information relating to a particular account is available in one place in the ledger.

    • Information on income and expenses: In the ledger, a separate account is maintained for each income and expense. The amount of total income and total expenses are known from the ledger accounts.

    • Preparation of trial balance: Ledger helps in preparing trial balances which ensure arithmetical accuracy of the transaction recorded in the books of account.

    • Helps in preparing final accounts: After preparing the trial balance, final accounts are prepared to know the profitability and financial position of the business.

    Utilities of sub-ledger

    The utilities of the sub-ledger are as follows :

    • Track customer information: If a client has an outstanding credit debt or needs money refunded, a company can use a sub-ledger to verify the information quickly.

    • Protect financial information: A sub-ledger allows a financial supervisor to isolate certain records so that employees can view only parts of the company’s financial information. This added level of security is important for large corporations.

    • Create separate databases: Large companies usually process large amounts of financial data that may be too big for one database. Software programs organize this data into isolated files to calculate financial information in the general ledger of a business.

    Conclusion

    So here I conclude that a ledger is compulsory in the recording process whereas a sub-ledger is optional.

    The ledger is used for preparing trial balance but the sub-ledger is not used for the same.
    Sub ledger is controlled by the ledger.

    The sub-ledger supports the transaction of each specific account indicated on the ledger.

    See less
    • 4
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jayesh Gupta
Jayesh GuptaCurious
In: 1. Financial Accounting > Miscellaneous

How to treat cheque issued but not presented for payment?

  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on August 22, 2021 at 6:01 am
    This answer was edited.

    A cheque that has been issued but yet not presented to the bank for payment is known as an unpresented cheque Generally what happens is when a cheque is issued to a party or say, creditor, the business immediately records them in the bank column of the cash book but the creditor might not present thRead more

    A cheque that has been issued but yet not presented to the bank for payment is known as an unpresented cheque

    Generally what happens is when a cheque is issued to a party or say, creditor, the business immediately records them in the bank column of the cash book but the creditor might not present them immediately to the bank for payment on the same date. The bank will only debit the account when it will be presented to it, therefore as long as the cheque remains unpresented there will be a difference in both the books i.e cash book and passbook.

    Let me give you a short example of the above treatment

    Suppose on 27th January, in the books of Mr. Shyam, the balance of the bank column as per the cash book is Rs 10,000. He received a cheque of Rs 5,000 from Mr. Hari, one of his debtors, which was sent to the bank for collection. The amount of the cheque was not collected by the bank until 31st January. Due to this, there arises a difference of Rs 5,000 in the cash book and pass book of Mr. Shyam.

    Following will be the entry in Mr. Shyam cash book and passbook

    In the books of Mr. Shaym

    Cash book (bank column only)

    Date Particulars Bank (Rs) Date Particulars Bank (Rs)
    27th Jan To balance b/d 10,000
    27th Jan To Hari 5,000
    31st Jan By balance c/d 15,000
    15000 15000

      Mr. Shyam

       Bank Statement

    Date Particulars Debit (Withdraw) Credit (Deposite) Debit or Credit Balance
    31st Jan To balance b/d credit 10,000

    How it is treated in the bank reconciliation statement?

    There lies a temporary difference in both the books as the represented cheques will eventually be presented. Therefore we will not alter the cash book. The bank statement shows the greater amount of Rs 5,000 as compared to the cashbook, therefore we will debit the amount of unpresented cheque which will eventually make it balance to the level of bank statement.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

The term current assets does not include?

Cash Stock in trade Furniture Advance Payment

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 6, 2022 at 3:49 pm
    This answer was edited.

    The correct option is 3.) The term current assets do not include furniture. Explanation A current asset is any asset that can reasonably be expected to be sold, consumed, or exhausted through the normal operations of a business within one accounting year. Thus, current assets don't have life for morRead more

    The correct option is 3.)

    The term current assets do not include furniture.

    Explanation

    A current asset is any asset that can reasonably be expected to be sold, consumed, or exhausted through the normal operations of a business within one accounting year. Thus, current assets don’t have life for more than a year.

    Example: Cash and cash equivalent, stock, liquid assets, etc.

    Furniture is expected to have a useful life for more than a year and they are bought for a long term by a company.

    Cash is a more liquid asset of a company making it a more “current” asset. It requires no conversion and is spendable as it is. Thus, making it a vital current asset.

    Stock in trade is a current asset because it can be converted into cash within one year and all the stock in trade of a company is expected to be sold within one accounting period and should not stick for a longer period.

    Advance payment, on the other hand, is an amount paid to an employee, essentially a short-term loan by the employer. It’s recorded on the asset side of the balance sheet and as these assets are used, they are expended and recorded on the income statement for the period in which they are incurred, making it a short-term asset ending within an accounting year.

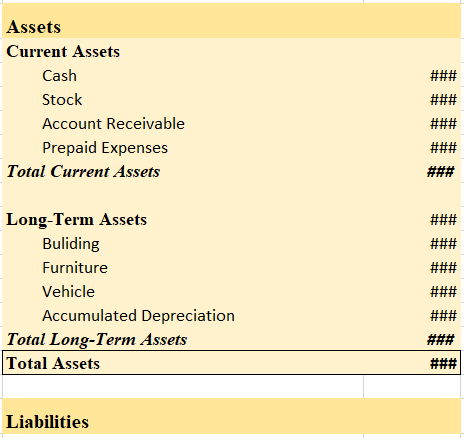
    Thus, on the asset side of the balance sheet, we can clearly see which current assets are and which are not included in the current asset

    Balance Sheet (As at…..)

    Therefore, (3) Furniture, won’t be included in current assets.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What is a workmen compensation reserve?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 18, 2021 at 7:51 am
    This answer was edited.

    Workmen Compensation Reserve as the name suggests is a reserve created by the company to compensate its employees in the event of any uncertainty in future. It is created to protect the interest of workers in the company. Workmen Compensation Reserve Account is generally given effect in case of admiRead more

    Workmen Compensation Reserve as the name suggests is a reserve created by the company to compensate its employees in the event of any uncertainty in future. It is created to protect the interest of workers in the company.

    Workmen Compensation Reserve Account is generally given effect in case of admission, retirement of partners or dissolution of firm.

    If there is a change in the estimated value of reserve it is given effect during the revaluation of assets and liabilities.

    Journal entry if the existing reserve is less than the new estimated amount:

    Revaluation A/c (Dr)

    To Workmen Compensation Reserve A/c

    The reserve is credited because we need to create more than the existing reserve, since the new estimated liability is more than the existing.

    Journal entry if the existing reserve is more than the new estimated amount:

    Workmen Compensation Reserve A/c (Dr)

    To Revaluation A/c

    The reserve is debited because we need to decrease the existing reserve, since the new estimated liability is less than the existing.

    If a worker claims compensation, it is said to be a liability against the reserve. In case of dissolution, any such liability against workmen compensation reserve takes priority to be paid off according to the law.

    Journal entry in case of claim against reserve is:

    Workmen Compensation Reserve A/c (Dr)

    To Workmen Compensation Claim

    The amount is transferred from the reserve to a new liability, hence the reserve is debited and the claim is credited.

    If there are not sufficient funds in the firm to pay the liability, partners will have to bring funds from their personal assets to pay the workers.

    Journal entry when partner’s have to bring funds:

    Partner’s Capital Account (Dr)

    To Workmen Compensation Reserve A/c

    Partner’s need to bring funds to fulfill the liability, hence there account is debited and since the reserve is increased, hence it is credited.

    If there is no liability against the Workmen Compensation Reserve then it is distributed amongst the partners in their existing profit-sharing ratio.

    Journal entry for distribution of reserve is:

    Workmen Compensation Reserve A/c (Dr)

    To Partner’s Capital Account

    Since, reserve is more than required it is distributed among partners, hence their account is credited and as the reserve decreases, it is debited.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.