

Outstanding expenses are those expenses that have been incurred during the accounting period but are yet to be paid. Basically, any expense which has become due for payment but is not paid will be called an outstanding expense. Outstanding expenses are treated as a liability as the business is yet tRead more
Outstanding expenses are those expenses that have been incurred during the accounting period but are yet to be paid. Basically, any expense which has become due for payment but is not paid will be called an outstanding expense.
Outstanding expenses are treated as a liability as the business is yet to make payment against them. Examples of outstanding expenses include outstanding rent, salary, wages, etc.
At the end of the accounting year, outstanding expenses have to be accounted for in the book of accounts so that the financial statements reflect the accurate profit/loss of the business.
Journal entry for recording outstanding expenses:
| Expense A/c | Debit |
| To Outstanding Expenses A/c | Credit |
| (Being expenses outstanding at the end of the year) |
The concerned expense A/c is debited as there is an increase in expenses. Outstanding expenses are a liability, hence they are credited.
Let me give you a simple example,
Max, a sole proprietor pays 1,00,000 as salary for his employees at the end of every month. Due to the Covid-19 lockdown, he could not pay his employees’ salaries for March month. So the salary for March (1,00,000) will be treated as an outstanding expense. The following entry is made to record outstanding salaries for the year.
| Salary A/c | 1,00,000 |
| To Outstanding Salaries A/c | 1,00,000 |
| (Being salaries outstanding at the end of the year) |
At the end of the year, outstanding salary will be adjusted in the P&L A/c and it will be shown as a Current Liability in the Balance Sheet.
See less









Introduction Internal reconstruction refers to the process of restructuring a sick company’s balance sheet by certain methods to turn it financially healthy, thus saving it from potential liquidation. Explanation When a company has been making losses for many years, it has a huge amount of accumulatRead more
Introduction
Internal reconstruction refers to the process of restructuring a sick company’s balance sheet by certain methods to turn it financially healthy, thus saving it from potential liquidation.
Explanation
When a company has been making losses for many years, it has a huge amount of accumulated losses due to which the reserve and surplus appear at a very low or negative amount in the balance sheet.
Also, such a company is said to be overcapitalised as it is not able to generate enough returns to its capital.
As the company is overcapitalised, the assets are also overvalued. The balance sheet also contains many fictitious assets and unrepresented intangible assets.
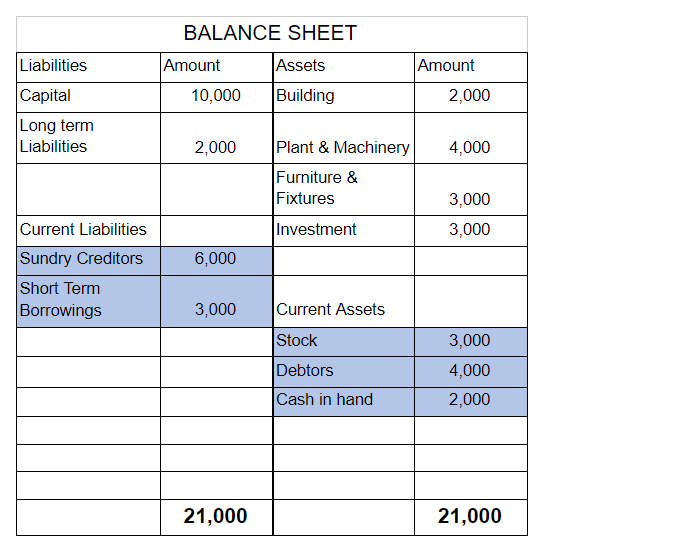
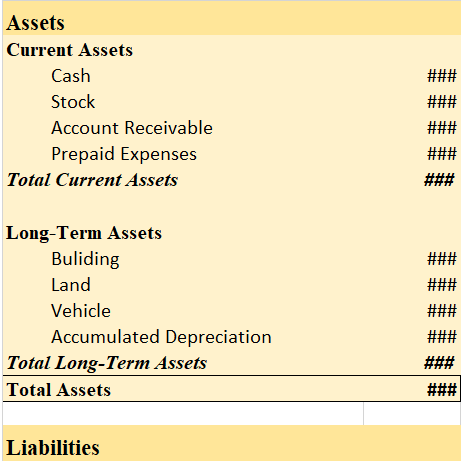
The balance sheet of such a ‘sick’ company looks like the following:
Hence, to save the company from liquidation,
In this way, its balance sheet gets rid of all undesirable elements and the company gets a new life without being liquidated. This process is known as internal reconstruction.
Legal compliance
The internal reconstruction of a company is governed by the provisions of the Companies Act, 2013.
See less