

Meaning We know that an account in ledger format has two amount columns i.e. debit and credit amount columns. Now, most of the time, the total of debit and credit sides do not match. The difference between their totals is called the balance of the account and it is posted on the shorter side. ThisRead more
Meaning
We know that an account in ledger format has two amount columns i.e. debit and credit amount columns. Now, most of the time, the total of debit and credit sides do not match. The difference between their totals is called the balance of the account and it is posted on the shorter side. This result in equalling the total of both sides, hence this act is called ‘balancing an account.
Types of balances
Balancing an account is a very usual practice so that the balance of an account can be known. An account can have two types of balances:
- Debit balance, where the debit side total is more than the credit side total.
- Credit balance, where the credit side is more than the debit side total.
The balance of an account is posted on the shorter side. It means:
- The debit balance will be shown on the credit side as the credit side total is shorter. (posted as ‘By Balance c/d’)
- The credit balance will be shown on the debit side as the debit side total is shorter (posted as ‘To Balance c/d’)
Example
The following is a cash account that is not balanced:
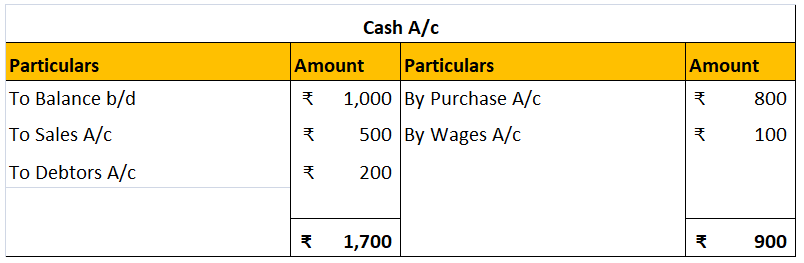
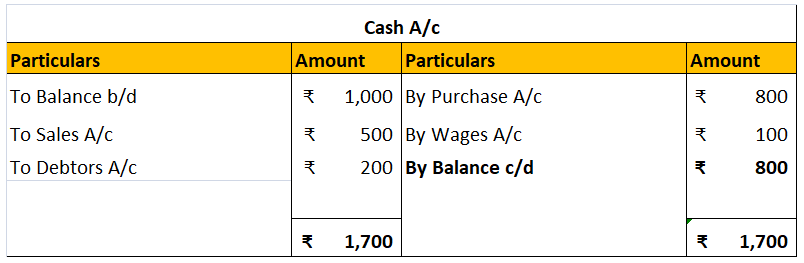
We can see the debit side is ₹800 more than the credit side. It means there is a debit balance. It will be posted on the credit side as ‘By balance c/d’ to balance the account.
Exceptions
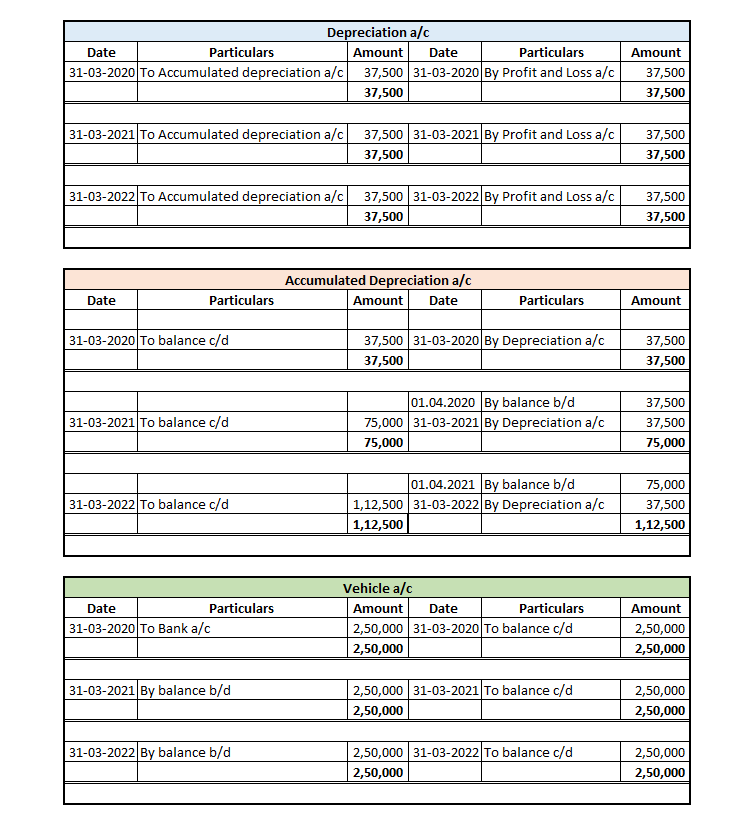
Balance of the income and the expense accounts (nominal accounts)are not computed. Instead, they are closed to trading account or profit and loss account to balance their amount totals. For example, the salaries account and sales accounts
Only the balance of the following types of accounts are computed and carried forwarded to successive accounting years:
- Assets
- Liabilities
- Capital
The balance of these accounts is shown on the trial balance and balance sheet as well.
See less







The term ‘contra’ means 'opposite'. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance. The purpose of the contra revenue account is to ascertain the actuaRead more
The term ‘contra’ means ‘opposite’. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance.
The purpose of the contra revenue account is to ascertain the actual amount of sales and record the items which have reduced the sales.
These are the contra revenue accounts commonly seen in businesses:
The total sales return is deducted from the sales in the balance sheet. Though being opposite of the sales account, the sale return account is not an expense account. It is considered an indirect loss as it reduces sales.
Sales discount is an expense hence it is debited to the profit and loss account.
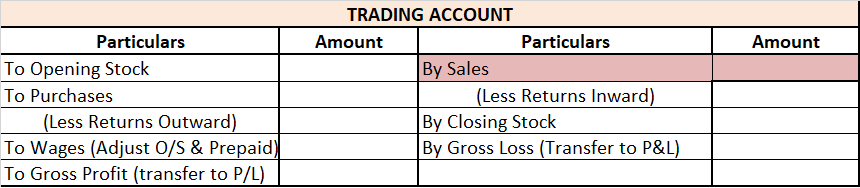
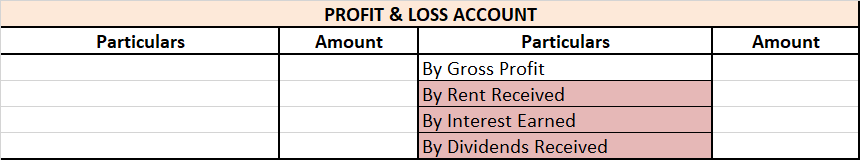
Sales returns and sales discounts are shown in the trading and profit and loss account in the following manner:

See less