

Meaning Capital assets mean the assets which are used in the business operations to generate revenue. The benefit from these assets is expected to flow to the enterprise beyond the time span of one year. Capital assets are commonly called fixed assets. Examples of capital assets are plant, machineryRead more
Meaning
Capital assets mean the assets which are used in the business operations to generate revenue. The benefit from these assets is expected to flow to the enterprise beyond the time span of one year. Capital assets are commonly called fixed assets.
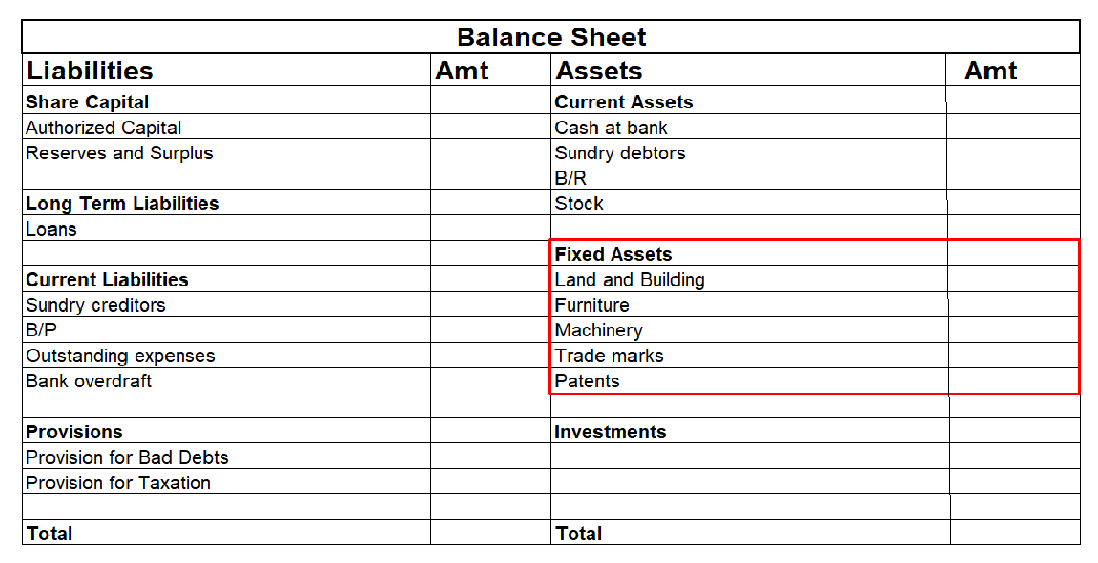
Examples of capital assets are plant, machinery, land, building, vehicles etc.
To expense the capital assets for the economic benefits they provide, they are depreciated over their useful life on some equitable basis.
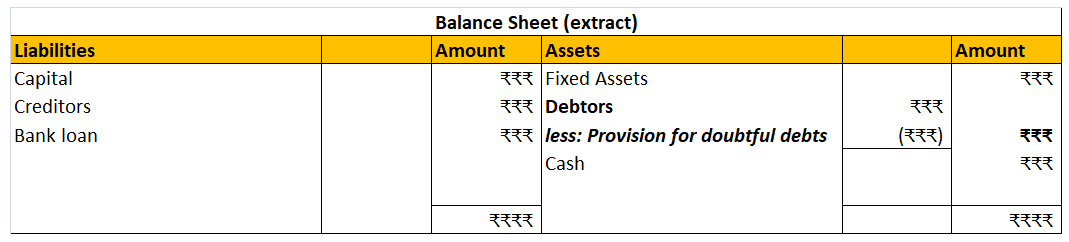
When capital assets are sold, the gain on sale is credited to the capital reserve account. On loss, it is simply debited to the profit and loss account. Capital assets are shown under the heading ‘Plant, Property and Equipment’ under the asset head of the balance sheet.
Assets that do not qualify as capital assets
The assets which provide economic benefits for less than a year do not qualify as capital assets. Such as inventories, accounts receivables etc. are not capital assets.
Also, those assets which are not intended to be held for more than 1 year are not capital assets even if such assets are capable of providing economic benefits for more than 1 year. Such assets will be considered current assets.
For example, if a plot of land is purchased by a business but the intention is to sell it after 2 months then such land will not be considered a capital asset.
See less








Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders. Therefore the cost of retained earnings is similar to theRead more
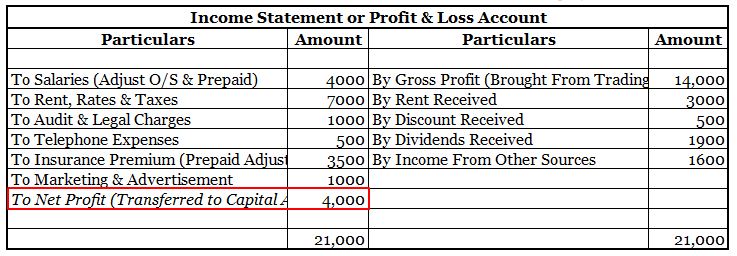
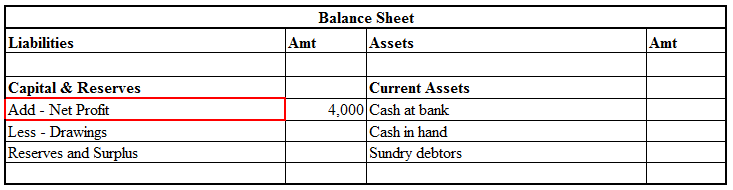
Retained earnings are kept with the company for growth instead of distributing dividends to the shareholders. Therefore the cost of retained earnings refers to its opportunity cost which is the cost of foregoing dividends by the shareholders.
Therefore the cost of retained earnings is similar to the cost of equity without tax and flotation cost. Hence, it can be calculated as
Kr = Ke (1 – t) (1 – f),
Kr = Cost of retained earnings
Ke = Cost of equity
t = tax rate
f = flotation cost
Here, flotation cost means the cost of issuing shares.
EXAMPLE
If cost of equity of a company was 10%, tax rate was 30% and flotation cost was 5%, then
cost of retained earnings = 10% x (1 – 0.30)(1 – 0.05) = 6.65%.
From the above example and formula, it is clear that the cost of retained earnings would always be less than or equal to the cost of equity since retained earnings do not involve flotation costs or tax.
A company usually acquires funds from various sources of finance rather than a single source. Therefore the cost of capital of the company will be the weighted average cost of capital (WACC) of each individual source of finance. The cost of retained earnings is thus an important factor in calculating the overall cost of capital.
Another important factor of WACC is the cost of equity. The cost of equity is sometimes interchanged with the cost of retained earnings. However, they are not the same.
See less