

Definition Section 43 of the companies act 2013 prescribes that the share capital of a company broadly can be of two types or classes : Preference shares Equity shares Preference shares Preference shares are the shares that carry the following two preferential rights : Preferential rights to receivRead more
Definition
Section 43 of the companies act 2013 prescribes that the share capital of a company broadly can be of two types or classes :
- Preference shares
- Equity shares
Preference shares
Preference shares are the shares that carry the following two preferential rights :
- Preferential rights to receive dividends, to be paid as a fixed amount or an amount calculated at a fixed rate, which may either be free of or subject to income tax before it is paid to equity shareholders, and
- Return of capital on the winding up of the company before that of equity shares.
Classes of preference shares
Preference shares are broadly classified as follows :
- With reference to the dividend
- Participation in surplus profit
- Convertibility
- Redemption
With reference to the dividend
Cumulative preference shares are those preference shares that carry the right to receive arrears of dividends before the dividend is paid to the equity shareholders.
Non-cumulative preference shares are those that do not carry the right to receive arrears of dividends.
Participation in surplus profit
Participating preference shares of the company may provide that after the dividend has been paid to the equity shareholders, the holders of preference shares will also have a right to participate in the remaining profits.
Non-participating preference shares are those preference shares that do not carry the right to participate in the remaining profits after the equity shareholders have paid the dividend.
Convertibility
Convertible preference shares are those preference shares that carry the right to be converted into equity shares.
Non-convertible preference shares are those that do not carry the right to be converted into equity shares.
Redemption
Redeemable preference shares are those preference shares that are redeemed by the company at the time specified for the repayment or earlier.
Irredeemable preference shares are preference shares the amount of which can be returned by the company to the holders of such shares when the company is wound up.
Equity shares
Equity shares are those shares that are not preference shares.
Equity shares are the most commonly issued class of shares that carry the maximum ‘risk and reward ‘ of the business the risks of losing part or all the value of the shares if the business incurs losses.
The rewards are the payment of higher dividends and appreciation in the market value.
See less







To understand why we do not record self-generated goodwill in accounting, let us first understand what goodwill is and its accounting treatment. What is Goodwill? Goodwill is an intangible asset of a business. It represents the reputation and brand value of a business built over time. It is a valueRead more
To understand why we do not record self-generated goodwill in accounting, let us first understand what goodwill is and its accounting treatment.
What is Goodwill?
Goodwill is an intangible asset of a business. It represents the reputation and brand value of a business built over time. It is a value over and above the tangible assets of the business.
Goodwill often arises when a business purchases another business and pays a premium, which means a price higher than the fair value of the business.
Characteristics of Goodwill
Goodwill has the following characteristics:
Example of Goodwill
Let us take an example to understand the concept of goodwill better.
Suppose there is a company ABC Ltd. It is planning to acquire XYZ Ltd. The fair value of the assets of XYZ is calculated to be 600,000. However, ABC has agreed to pay a sum of 650,000 to acquire the company. This difference of 50,000 is goodwill.
Impact on Financial Statements
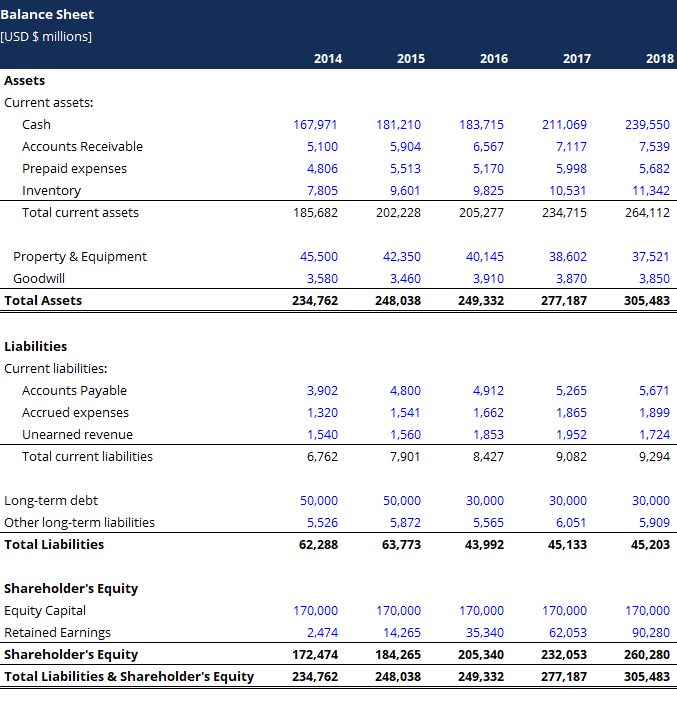
Goodwill is shown under the assets side of the Balance Sheet.
What is self-generated goodwill?
Self-generated goodwill in simple words means the positive reputation or trust that a business earns over time through their own hard work and decisions. It’s not something bought or inherited but something built from scratch internally, like a brand’s reputation, loyal customers, strong relationships, or unique ideas.
For example, a small business that goes the extra mile to offer great customer service or always delivers high-quality products over the years will naturally build goodwill.
It is also known as internally generated goodwill.
Why do we not record sef-generated goodwill?
Self-generated goodwill is not recorded in the financial statements because of the following reasons:
Conclusion
On a concluding note, self-generated goodwill is something that adds real value to a business, but it’s not something that can easily be measured or captured in financial statements. Accounting is all about providing clear, reliable information, and including goodwill would make things murky and open to manipulation. Even though it doesn’t show up on the books, you can still see its effects in a company’s reputation and success. Maybe in the future, businesses will find a way to highlight it better, but for now, leaving it out helps keep financial reports honest and straightforward.
See less