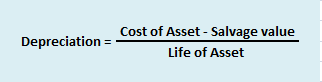
Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Bonnie
BonnieCurious
In: 1. Financial Accounting > Not for Profit Organizations

From the following receipts and payments account and additional information given below prepare income and expenditure account and balance sheet of rural literacy society as on 31st March 2019?

Receipts and Payments Account for the year ended 31st March 2019 Receipts Amt Payments Amt To Balance b/d By General Expenses 32,000 Cash in Hand 40,000 By Newspapers 18,500 Cash at Bank 155,500 By Electricity 30,000 To Subscription By Fixed Deposits with Bank 180,000       2017-18                         12,000      (On 30 ...

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on August 31, 2021 at 10:30 am
    This answer was edited.

    In the books of Rural Literacy Society Income & Expenditure A/c for the year ended 31 March 2019 Expenditure Amt Amt Income Amt Amt To General Expenses 32,000 By Subscription (W.N.1) 2,72,000 To Newspapers 18,500 By Legacy 12,500 To Electricity 30,000 By Government Grant 1,20,000 To Rent 65,000Read more

    In the books of Rural Literacy Society

    Income & Expenditure A/c for the year ended 31 March 2019

    Expenditure Amt Amt Income Amt Amt
    To General Expenses 32,000 By Subscription (W.N.1) 2,72,000
    To Newspapers 18,500 By Legacy 12,500
    To Electricity 30,000 By Government Grant 1,20,000
    To Rent 65,000 By Interest Received on Fixed Deposit 9,000
    Less: Prepaid Rent (65,000/13) -5,000 60,000     (1,80,000*10%*6/12)
    To Salary 36,000
    Add: Outstanding Salary 6,000 42,000
    To Postage Charges 3,000
    To Loss on Sale of Furniture (W.N.2) 13,000
    To Surplus (excess of income over expenditure) 2,15,000
    4,13,500 4,13,500


    Balance Sheet as on 31 March 2019

    Liabilities Amt Amt Assets Amt Amt
    Capital Fund (W.N.3) 3,85,500 Fixed Deposit 1,80,000
    Add: Surplus 2,15,000
    Advance Subscription 5,000 Books 50,000
    Outstanding Salaries 6,000 Add: Purchased 70,000 1,20,000
    Furniture 1,20,000
    Add: Purchased 1,05,000
    Less: Sold -50,000 1,75,000
    Outstanding Subscription 15,000
    Prepaid Rent 5,000
    Cash in Hand 30,000
    Cash at Bank 82,000
    Accrued Interest (W.N.4) 4,500
    6,11,500 6,11,500


    Working Notes:

    W.N.1: Calculation of Subscription

    Subscription for 2018-19 2,65,000
    Add: Outstanding Subscription (31 March 2019) 15,000
    Less: Outstanding Subscription (2017-18) -8,000
                     Total Subscription 2,72,000

    In the above calculation, for the year 2017-18 subscription amount was 12,000, and in the adjustment at the end of the year subscription was 20,000 so the difference of 8,000 is the amount of subscription that was outstanding.


    W.N.2: Calculation of loss on sale of furniture

    Book Value of Furniture 50,000
    Less: Sold -37,000
                    Loss on Sale of Furniture 13,000


    W.N.3: Calculation of Capital Fund

    Balance Sheet as on 31 March 2018

    Liabilities  Amt  Assets Amt
    Capital Fund (Balancing Figure) 3,85,500 Books 50,000
    Furniture 1,20,000
    Outstanding Subscription 20,000
    Cash in Hand 40,000
    Cash at Bank 1,55,500
    3,85,500 3,85,500


    W.N.4: Calculation of Accrued Interest

    Interest as of 30 September 2018 9,000
    Less: Interest as of 31 March 2019 -4,500
                   Accrued Interest 4,500
    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Financial Statements

How to show format of balance sheet as per companies act 2013?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 14, 2021 at 7:08 pm
    This answer was edited.

    A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnershiRead more

    A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnership where the horizontal format is used.

    COMPONENTS OF A BALANCE SHEET

    The three main components of a balance sheet are Assets, Liabilities and Shareholders’ equity.

    • Assets: They are divided into two main categories that are current assets and non-current assets. If an asset is expected to be realised within 12 months or is primarily held for being traded, or is cash or cash equivalent, then those assets are termed as current assets. All assets that are not current assets are grouped under non-current assets. They are normally realised after 12 months.
    • Liabilities: They are categorised as current liabilities and non-current liabilities. If the amount owed by the company to an outside party is due to be settled in 12 months, then it can be termed as a current liability. The rest of the liabilities are referred to as non-current liability.
    • Shareholders’ Equity: This is the money owed to the owners of the company, that is shareholders. It is also called net assets since it is equal to the difference between total assets and total liabilities. Their main categories are Shareholders’ Capital and Reserves and Surplus.

    FORMAT OF BALANCE SHEET

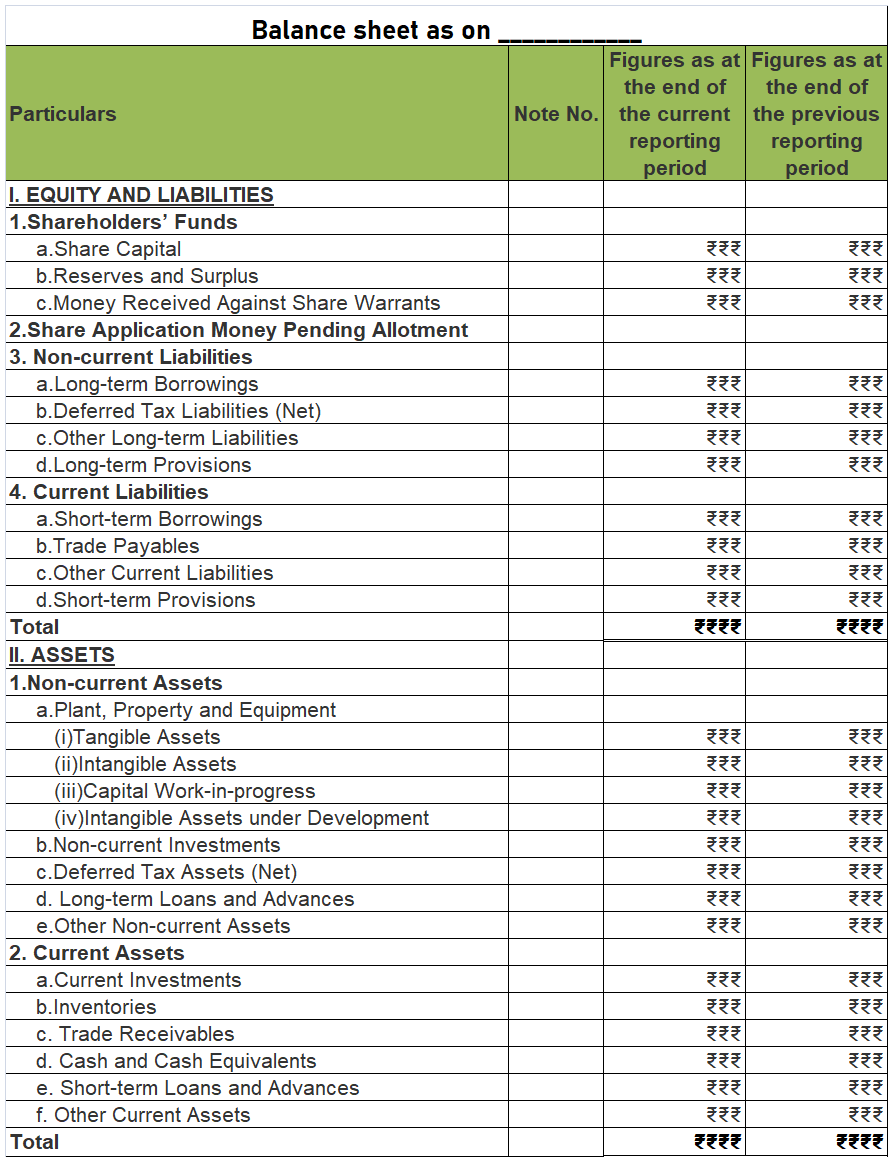
    As per the Companies Act 2013, the following format should be used for preparing a balance sheet.
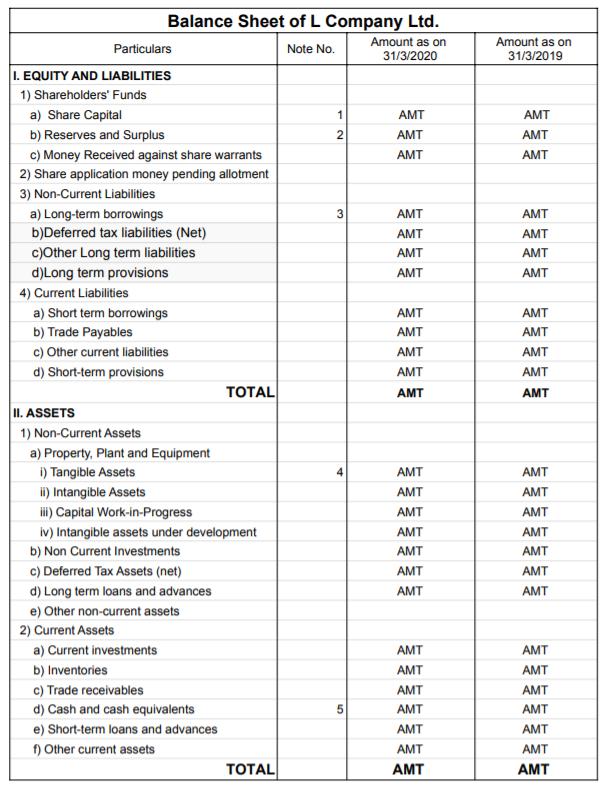
    From the above Balance sheet, we should get:

    Assets = Liabilities + Shareholders’ Equity

    Relevant notes for each component should also be prepared when necessary.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Depreciation & Amortization

Difference between Amortization & Impairment?

AmortizationDifference BetweenImpairment
  • 1 Answer
  • 0 Followers
Answer
  1. Astha Leader Pursuing CA, BCom (Hons.)
    Added an answer on June 12, 2021 at 2:49 pm
    This answer was edited.

    Let us first understand the concepts of Amortization and Impairment. Amortization refers to the expense recorded on the decline of the value of intangible assets of a company. Intangible assets include goodwill, patents, copyrights, etc. It reflects the reduction in the value of Intangible assets ovRead more

    Let us first understand the concepts of Amortization and Impairment.

    Amortization refers to the expense recorded on the decline of the value of intangible assets of a company. Intangible assets include goodwill, patents, copyrights, etc. It reflects the reduction in the value of Intangible assets over its life span.

    Amortization is similar to Depreciation, however, while depreciation is over tangible assets amortization is over Intangible assets of the company.

    For example, Cipla Ltd. acquired a patent over a new drug for a period of 10 years. The cost of creating the new drug was 80,000 and the company must record its patent at 80,000. However, the company must amortize this cost by dividing the cost over the patent’s life, i.e., the amortization cost would be 8,000 (80,000/10) p.a. for the next 10 years.

    Impairment means a decline in the value of fixed assets due to unforeseen circumstances. Assets are impaired when the carrying value of assets increases its market value or “realizable value” and such increase is recorded as an impairment loss.

    Now suppose, Cipla Ltd. had existing machinery which suffered physical damage and is recorded at 50,000 in the books but the realizable value of the asset would only be 20,000. Hence, the asset would be written down to 20,000 and an impairment loss of 30,000 will be recorded.

    Impairment Vs Amortization

    Differences between the two can be shown as follows:

    Amortization Impairment
    Amortization is a reduction in the value of Intangible Assets over their useful life. Impairment is a reduction in the value of assets due to unforeseen circumstances.
    Amortization is a continuous process and the value of an asset reduces over time. Value of asset reduces drastically, creating a need to write down the value to its fair market value.
    Amortization is charged annually. Impairment is not an annual charge.
    Amortization is shown as an amortization expense. Impairment is shown as an impairment loss.
    Reasons for amortization includes consumption, obsolescence, etc. Reasons for impairment include damage to the asset, change in preferences, etc.
    Amortization is charged on Intangible assets Impairment is charged on fixed assets whether tangible or intangible.

    Suppose Unilever Ltd. has a patent over one of its products for a period of 5 years. The cost of the patent was 1,00,000. Then after 2 years one of its rivals, say ITC Ltd., launches a new product which is more preferred by the consumers over the one produced by Unilever Ltd. and the fair market value of the patent of Unilever Ltd. changes to 10,000.

    Now in this scenario, Unilever Ltd. would have amortized the patent (costing 1,00,000) at 20,000 (1,00,000/5) p.a. for 2 years and the book value at the end of the 2nd year is 60,000 (1,00,000 – 40,000). Now due to the new launch by ITC Ltd. the drastic change in the value of the asset from the book value of 60,000 to the realizable value of 10,000 will be recorded as an Impairment loss. Hence Impairment loss would be recorded at 50,000 (60,000 – 10,000).

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Ledger & Trial Balance

How to post a compound entry in ledger account?

Compound EntryLedger
  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on June 17, 2021 at 2:40 pm
    This answer was edited.

    When in a single transaction two or more accounts are involved, such kinds of transactions are termed as Compound entries. Example 1, Johnson Co. purchased goods worth 5,000, and half of the amount was paid in cash and the other half by cheque. So here three accounts are involved: Purchase account-Read more

    When in a single transaction two or more accounts are involved, such kinds of transactions are termed as Compound entries.

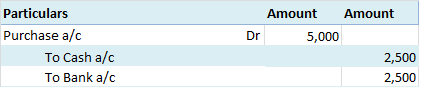
    Example 1, Johnson Co. purchased goods worth 5,000, and half of the amount was paid in cash and the other half by cheque.

    So here three accounts are involved:

    Purchase account- That is to be debited.

    Cash account- That is to be credited.

    Bank account- That is to be credited.

    Journal entry:

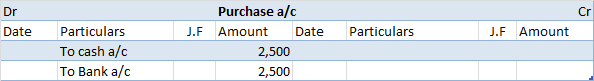
    Now posting the above journal entry in a ledger account.

    In the Journal, the Purchase account has been debited. So in the ledger, the purchase account will also be debited. Since the purchase account is debited in the ledger, the corresponding two credit accounts of this entry i.e. the cash and the bank will be written on the debit side in the particulars column. So while posting, the amount to be considered would be the amount individually paid in cash and bank as shown in the journal entry.

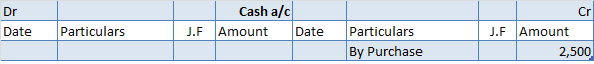
    Cash a/c is credited with the purchase account.  In the ledger, purchase a/c will be posted on the credit side. So while posting, the amount to be considered would be the amount individually paid in cash.

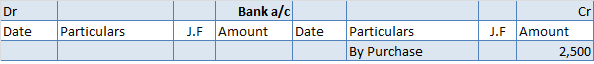
    Bank a/c is credited with the purchase account. In the ledger, purchase a/c will be posted on the credit side. So while posting, the amount to be considered would be the amount individually paid in Bank a/c.

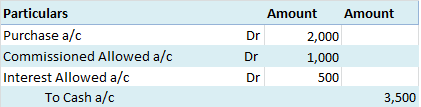
    Example 2,  Johnson Co purchased goods and made payment in cash 2,000. Along with it, it also paid commission and interest of 1,000 and 500 respectively.

    So here four accounts are involved:

    Purchase account- That is to be debited.

    The commission allowed account- That is to be debited.

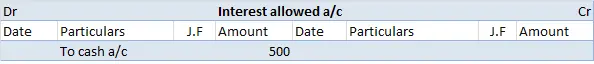
    Interest allowed account- That is to be debited.

    Cash account- That is to be credited.

    Journal Entry:

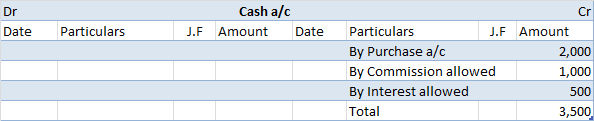
    Now posting the above journal entry in a ledger account.

    In the journal entry, the cash account has been credited. So in the ledger, the cash account will also be credited. Since the cash account is credited in the ledger, the corresponding three accounts will also be credited in the particulars column. As in the journal entry the three debit accounts viz. Purchase, the commission allowed, and interest allowed, the amounts written against them shall be entered in the respective accounts in the amount column on the credit side of the cash account.

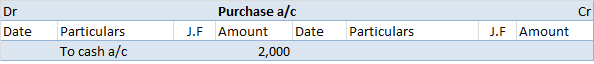
    Purchase a/c is debited with a cash account.  In the ledger, Cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in the Purchase account.

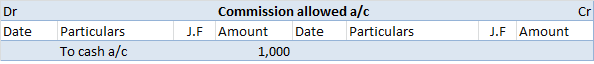
    The commission allowed a/c is debited with a cash account.  In the ledger, cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in Commission allowed a/c.

    Interest allowed a/c is debited with a cash account.  In the ledger, cash a/c will be posted on the debit side. So while posting, the amount to be considered would be the amount individually paid in Interest allowed a/c.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Financial Statements

Can you show a format of balance sheet?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 27, 2021 at 11:25 am
    This answer was edited.

    A balance sheet is a financial statement that reports the position or value of assets, liabilities and equity at a particular date, which is usually the closing date of a financial year. Formats of balance sheet A balance sheet may be presented in two formats: T-form or Horizontal format This formatRead more

    A balance sheet is a financial statement that reports the position or value of assets, liabilities and equity at a particular date, which is usually the closing date of a financial year.

    Formats of balance sheet

    A balance sheet may be presented in two formats:

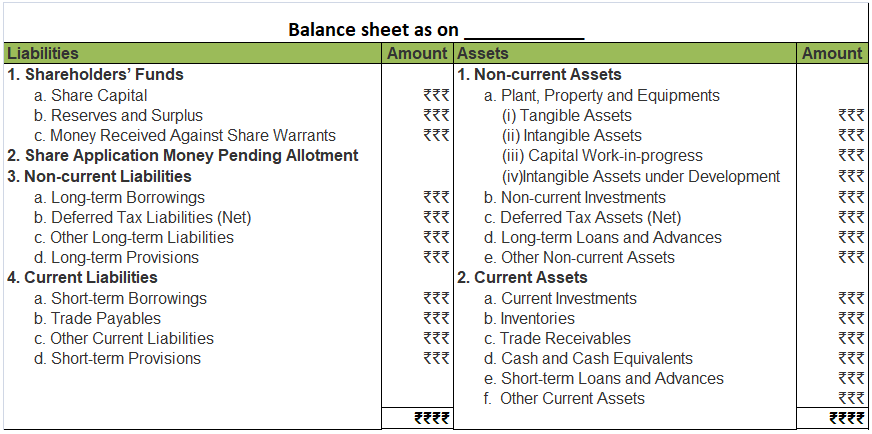
    T-form or Horizontal format

    This format is the same as the format of ledger accounts. There are two columns with the headings ‘Liabilities’ for the left column and ‘Assets’ for the right column and columns adjacent to both columns for amounts. The liabilities and equity (capital) are shown on the liabilities side because they both have credit balance and assets are shown on the asset side. Most of the non-corporates prepare their balance as per this format. The T-form balance sheet looks as given below:

    Vertical format

    The vertical format of the balance sheet is mostly prepared by corporate entities. Here, the liabilities and assets are shown in the same column as compared to two separate columns in the horizontal format. This results in having a longer shape. Hence, it is called a ‘vertical’ balance sheet. Generally, companies prepare their balance sheet as per this format.

    Also, many times, there are two columns for the amount in this format presenting the amount of both the current year and the previous year. This format looks like as given below:

    Grouping and marshalling

    Beside the structure of the balance sheet i.e. horizontal and vertical, the grouping and marshalling of the items inside the balance sheet are also very important.

    Grouping refers to the presenting of similar items under a heading or group. This is done in order to present the balance sheet in a concise manner. This is very important to do. For example, a business can have numerous creditors, but they are all presented under one ‘Creditors’ heading or two or more heading specifying different types of creditors.

    The assets of a business are grouped under the heading such as Plant, Property and equipment, Current assets, Non-current investments etc.

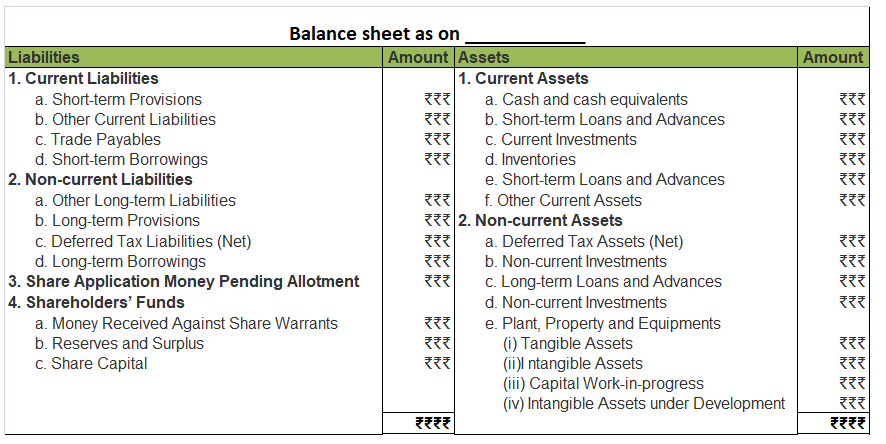
    Marshalling means the arranging of items as per a particular order. We know that a balance sheet consists of many items and to make the statement more useful and easy to comprehend, the items are arranged in one of the following orders:

    • Order of Liquidity: The items which are more liquid i.e which can be easily converted into cash are kept at the top. Like in assets, cash is the most liquid asset and requires no conversion. Then items like current investment, inventories (in case of fast-moving goods) are placed under and so on. At the near bottom, items that require a long time of conversion into cash are placed such as land, plant and machinery.

    In case of liabilities, the items which are due for repayment soon are kept at the top, like bank overdraft etc. The items which are due for repayment after a long time or at the time of winding capital are kept at the bottom, like long term loans and capital funds. Given below is a format of horizontal balance sheet in which the items are marshalled in order of liquidity:

    • Order of permanence: This type of arrangement is just the opposite of the order of liquidity. Here the items which are least liquid are placed at the top and the more liquid items are placed at the bottom. Like in the case of assets, cash appears at the bottom and non-current assets at the top. On the liabilities side, equity and non-current liabilities are at the top while current liabilities are at the bottom. Mostly all balance sheets are marshalled in order of permanence.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Journal Entries

Received cash for a bad debt written off last year journal entry?

  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 23, 2021 at 4:35 am
    This answer was edited.

    The debts that have a higher chance of not being paid are called doubtful debts. They are a part of the regular dealing of the company and may arise due to disputes or treachery on the part of debtors. Bad debts refer to the doubtful debts that no longer seem to be recoverable from the business. WriRead more

    The debts that have a higher chance of not being paid are called doubtful debts. They are a part of the regular dealing of the company and may arise due to disputes or treachery on the part of debtors.

    Bad debts refer to the doubtful debts that no longer seem to be recoverable from the business.

    Written off means an expense, income, asset, liability is no more recorded in the books of accounts because they no longer hold relevance for the business.

    When doubtful debts turn into bad debt, they are written off from the books after a stipulated time as they no longer seem recoverable.

    If any cash is received against such bad debts that were written off, it is known as cash received against bad debts written off. Cash is received against bad debts usually when the debtor is declared insolvent and money is recovered from its estate.

    Bad debts recovered are considered an income for the company as they were previously written off as a loss and any cash received against it is considered as income.

    Journal entry for such situation is:

    Cash or Bank A/c (Dr.)

    To Bad Debts Recovered A/c

    We debit the increase in assets, and since cash is coming into the business it is debited.

    We credit the income, and since bad debts recovered is an income to the business it is credited.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Journal Entries

What is the journal entry for loan to employee?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on August 4, 2021 at 6:41 pm
    This answer was edited.

    The journal entry for a loan to an employee is as follows: Loans to employee A/c                                            …..Dr xxx             To Bank/Cash A/c xxx (Being loan given to employee) From the above journal entry, we see that there are two accounts-first one is "Loan to employee accounRead more

    The journal entry for a loan to an employee is as follows:

    Loans to employee A/c                                            …..Dr xxx
                To Bank/Cash A/c xxx
    (Being loan given to employee)

    From the above journal entry, we see that there are two accounts-first one is “Loan to employee account” and the second one is “Bank/cash account“. Both are assets for the company.

    Loan to employees is considered an asset because they are expected to be returned by the employee within the stipulated time period. If the loan is repaid within one year it will be shown under the current asset and if it is not expected to be collected within a year or in short might be repaid after a year then it will be shown under long-term assets.

    Also, we all know Bank/cash is an asset for the company.

    Why loan to employee A/c is debited and Bank/cash A/c is credited?

    As per the modern rule:

    ASSETS
    Increase Debit
    Decrease Credit

    Connecting the above-stated entry with the modern rule “loan to an employee” is debited as money comes back into the business hence there is an increase in an asset therefore debited. While in the second case “bank/cash account” is credited as the money goes out of the business, there is a decrease in assets of the company therefore credited.

    Loan to employee The inflow of cash in a future date Increase in an asset Debit
    Bank/ cash The outflow of cash Decrease in an asset Credit

    We notice that in this entry there is an increase in one asset while a decrease of another asset. Therefore the impact on the balance sheet is Nil.

    Let me give you a simple illustration of the above entry

    Mr. Ross was an employee of Maxwell Pvt ltd. Mr. Ross was lent Rs 2,00,000 by the company for some emergency purpose. So as per modern rules the accounting entry in the books of the company will be as follows:

    Loans to Mr. Ross A/c                                            …..Dr 2,00,000
                To Bank/Cash A/c 2,00,000
    (Being loan given to Mr. Ross)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
prashant06
prashant06
In: 1. Financial Accounting > Journal Entries

What is the Journal Entry for Opening Stock?

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on August 4, 2021 at 5:55 pm
    This answer was edited.

    The journal entry for the opening stock will be: Particulars Amt Amt Trading A/c INR              To Opening Stock A/c INR (Being opening stock transferred to Trading A/c) Opening stock is the value of inventory that is available with the company for sale at the beginning of the accounting period. ORead more

    The journal entry for the opening stock will be:

    Particulars Amt Amt
    Trading A/c INR
                 To Opening Stock A/c INR
    (Being opening stock transferred to Trading A/c)

    Opening stock is the value of inventory that is available with the company for sale at the beginning of the accounting period. Opening stock may include stock of raw material, semi-finished goods, and finished goods. It is a part of the cost of sales.

    Closing stock is the value of unsold inventory left with the company at the end of the year. The previous year’s closing stock is the current year’s opening stock.

    Trading Account is a nominal account. According to the golden rules of accounting, the nominal account is the account where “Debit” all expenses and losses, and “Credit” all income and gains.

    In the above journal entry, the opening stock account is credited because it is the balance that is carried forward from the previous year and carried forward with the aim of selling it and gaining profit from it. The trading account here is debited as opening stock is carried forward to the next year from the trading account only.

    According to modern rules of accounting, “Debit entry” increases assets and expenses, and decreases liability and revenue, a “Credit entry” increases liability and revenues, and decreases assets and expenses.

    Here, Trading A/c is debited because an expense is incurred while bringing stock into the business. Opening Stock A/c is credited because indirectly it is creating a source of income for the business.

    The formula for calculating opening stock is as follows:

    Opening Stock = Cost of Goods Sold + Closing Stock – Purchases

    For example, AB Ltd. started a new accounting period for dairy products and introduced opening stock worth Rs.1,00,000 in the business.

    Here, the journal entry will be,

    Particulars Amt Amt
    Trading A/c 1,00,000
                 To Opening Stock A/c 1,00,000
    (Being opening stock transferred to Trading A/c)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Sandy
Sandy
In: 1. Financial Accounting > Depreciation & Amortization

What are the different methods of charging depreciation?

Depreciation
  • 1 Answer
  • 0 Followers
Answer
  1. Nistha Pursuing B.COM H (B&F) and CMA
    Added an answer on June 27, 2021 at 3:14 pm
    This answer was edited.

    Depreciation refers to that portion of the value of an asset that is written off over the useful life of the asset due to wear and tear. Now, when we talk about depreciation, there are multiple methods to calculate depreciation such as: Straight Line Depreciation Method Diminishing Balance Method OrRead more

    Depreciation refers to that portion of the value of an asset that is written off over the useful life of the asset due to wear and tear.

    Now, when we talk about depreciation, there are multiple methods to calculate depreciation such as:

    • Straight Line Depreciation Method
    • Diminishing Balance Method Or Written Down Value Method
    • Sum of Years’ Digits Method
    • Double Declining Balance Method
    • Sinking Fund Method
    • Annuity Method
    • Insurance Policy Method
    • Discounted Cash Flow Method
    • Use Based Methods
      • Output Method
      • Working Hours Method
      • Mileage Method
    • Other Methods
      • Depletion Method
      • Revaluation Method
      • Group or Composite Method

    The most commonly used methods are discussed below:

    1. Straight Line Depreciation Method: This is the simplest method for calculating depreciation where a fixed amount of depreciation is charged over the useful life of the asset.

    Formula:

    Suppose a company Bear Ltd purchases machinery costing 8,00,000 with useful life of 10 years and salvage value 1,00,000. Then depreciation charged to the machinery each year would be:

    Depreciation = (8,00,000 – 1,00,000)/10 = 7,00,000/10 = 7,000 p.a.

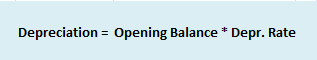
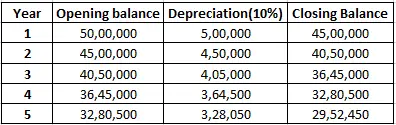
    2. Diminishing Balance Method Or Written Down Value Method: Under this method, a fixed rate of depreciation is charged every year on the opening balance of the asset which is the difference between the previous year’s opening balance and the previous year’s depreciation. Here the book value of asset reduces every year and so does the depreciation amount.

    Formula:

    Suppose a company Moon ltd purchases a building for 50,00,000 with a useful life of 5 years and decides to depreciate it @ 10% p.a. on Diminishing Balance Method. Then depreciation charged to the machinery would be:

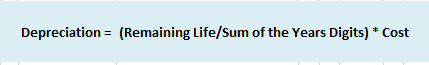
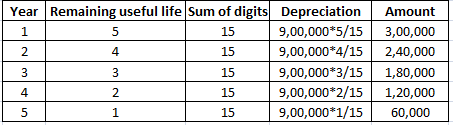
    3. Sum of Years’ Digits Method: In this method, the life of asset is divided by the sum of years and multiplied by the cost of the asset to determine the depreciating expense. This method allocates higher depreciation expense in the early years of the life of the asset and lower depreciation expense in the latter years.

    Formula:

    Suppose a company Caps Ltd purchases machinery costing 9,00,000 having a useful life of 5 years. Then the depreciation cost would be:

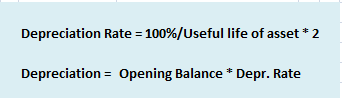
    4. Double Declining Balance method: This method is a mixture of straight-line method and diminishing balance method. A fixed rate of depreciation is charged on the reduced value of the asset at the beginning of the year. This rate is double the rate charged under straight-line method.

    Formula:

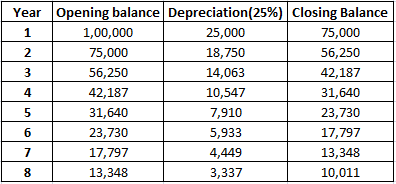
    Suppose a company Paper Ltd purchases machinery for 1,00,000 with an estimated useful life of 8 years. Then the depreciation rate would be:

    Straight line = 100%/8 = 12.5%

    Double declining method = 2*12.5% = 25%

    5. Sinking Fund Method: Under this method, the amount of depreciation keeps on accumulating till the asset is completely worn out. Depreciation is the same every year. Profits equal to the amount of depreciation is invested each year outside the company. At the time of replacement of the asset the investments and sold and the proceeds thereof are used to purchase the new asset.

    6. Annuity Method: This method calculates depreciation by calculating its internal rate of return (IRR). Depreciation is calculated by multiplying the IRR with an initial book value of the asset, and the result is subtracted from the cash flow for the period.

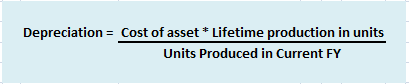
    7. Use Based Methods: Depreciation, under these methods, is based on the total estimated machine hours or total estimated units produced during the life of the machine. It is calculated by dividing the cost of the machine by the estimated total machine hours or estimated lifetime production in units and multiplying by the units produced or machine hours worked.

    Formula:

    Suppose a company Box Ltd purchases machinery for 25,000 (estimated life 5 years) whose estimated life production is 5,000 units. If it produces 700 units in the first year of operation then depreciation cost would be:

    Depreciation = 25,000/5,000*700 = 3,500

    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Ledger & Trial Balance

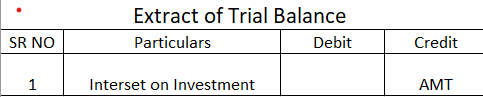
How to show interest on investment in trial balance?

Interest on investmentTrial Balance
  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on November 11, 2021 at 3:59 pm
    This answer was edited.

    Interest on Investment is to be shown on the Credit side of a Trial Balance. Interest on investment refers to the income received on investment in securities. These securities can be shares, debentures etc. of another company. When one invests in securities, they are expected to receive a return onRead more

    Interest on Investment is to be shown on the Credit side of a Trial Balance.

    Interest on investment refers to the income received on investment in securities. These securities can be shares, debentures etc. of another company. When one invests in securities, they are expected to receive a return on investment (ROI).

    Since interest on investment is an income, it is shown on the credit side of the Trial Balance. This is based on the accounting rule that all increase in incomes are credited and all increase in expenses are debited. A Trial Balance is a worksheet where the balances of all assets, expenses and drawings are shown on the debit side while the balances of all liabilities, incomes and capital are shown on the credit side.

    For example, if Jack bought Corporate Bonds of Amazon, worth $50,000 with a 10% interest on investment, then the accounting treatment for interest on investment would be

    Cash/Bank A/C Dr     5,000
    To Interest on Investment in Corporate Bonds (Amazon) 5,000

    As per the above entry, since interest on investment is credited, it will show a credit balance and hence be shown on the credit side of the Trial Balance. Interest on investment account is not to be confused with an Investment account. Investment is an asset whereas interest on investment is an income.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.