


A Cash Flow Statement analyzes the effect of various activities in the company on cash and, that is, it shows the inflow and outflow of cash and cash equivalents. A Fund Flow Statement analyzes the financial position of a company by the inflow and outflow of funds. Both the statements are financialRead more
A Cash Flow Statement analyzes the effect of various activities in the company on cash and, that is, it shows the inflow and outflow of cash and cash equivalents.
A Fund Flow Statement analyzes the financial position of a company by the inflow and outflow of funds.
Both the statements are financial statements and are used to analyze the financial performance of the company of two different reporting periods. Both the statements record the inflow and outflow of cash or funds, as the case may be.
The primary objective of preparing a Cash Flow Statement is to gain an understanding of the changes in the net working capital of the company and to classify the activities in the company under three different heads which helps in better analysis of Financial Statements for management, outsiders, and investors.
The primary objective of preparing a Fund Flow Statement is to track the movements of funds in the company, as the extent of use of long-term and short-term borrowings, frequency of their procurement, its application, etc.
The components of the Cash Flow Statement are:
- Cash Flow from Operating Activities- activities concerning the regular business operations and working capital are classified under this head.
- Cash Flow from Investing Activities- investment in long-term assets or sale of such assets are considered under this head.
- Cash Flow from Financing Activities- borrowings that a company makes to fund its operations, their interest payment, and repayment are covered under this head.
The components of the Fund Flow Statement are:
Sources of Funds:
- Owners
- Outsiders
Application of Funds:
- Funds deployed in Fixed Assets
- Funds deployed in Current Assets
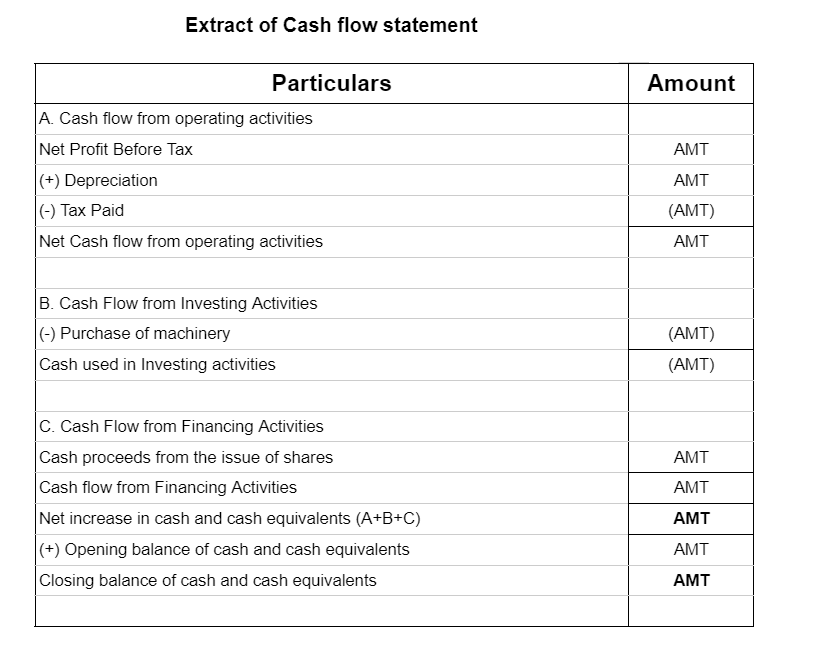
A sample format of the Cash Flow Statement will be:
| Particulars | Amount |
| Cash Flow from Operating Activities | XXX |
| Cash Flow from Investing Activities | XXX |
| Cash Flow from Financing Activities | XXX |
| Net Increase (Decrease) in Cash and Cash Equivalents | XXX |
| Cash and Cash Equivalents at the beginning | XXX |
| Cash and Cash Equivalents at the end | XXX |
A sample format of the Fund Flow Statement will be:
| Particulars | Amount |
| Sources of Funds | XXX |
| Funds from Operations | XXX |
| Sale of Fixed Assets | XXX |
| Issue of Shares | XXX |
| Issue of Debentures | XXX |
| Long Term Borrowings | XXX |
| Total (A) | XXX |
| Application of Funds | XXX |
| Loss from Operations | XXX |
| Payment of Tax | XXX |
| Repayment of Loan | XXX |
| Redemption of Debentures | XXX |
| Redemption of Preference Shares | XXX |
| Total (B) | XXX |
| Net Increase (Decrease) in Working Capital | XXX |
To conclude the difference between Fund Flow and Cash Flow Statement will be:
| Cash Flow Statement | Fund Flow Statement |
| Record of inflow and outflow of cash. | Record of sources and application of funds. |
| Prepared to analyze cash used in various activities. | Prepared to track the movement of funds and their applications. |
Components include:
|
Components include:
· Sources of Funds · Application of Funds |
See less







A profit and loss account is a financial statement which shows the net profit or net loss of an enterprise for an accounting period. It reports all the indirect expenses and indirect income including gross profit or loss derived from trading accounts for an accounting period. When the total revenueRead more
A profit and loss account is a financial statement which shows the net profit or net loss of an enterprise for an accounting period. It reports all the indirect expenses and indirect income including gross profit or loss derived from trading accounts for an accounting period.
When the total revenue i.e. credit side of profit and loss a/c is more than the total of expenses i.e. the debit side of profit and loss a/c, it results in net profit whereas when the total revenue is less than the total of expenses, it results in a net loss.
The debit balance of the profit and loss account is the net loss incurred during the accounting period by an enterprise. It is transferred to a capital account thereby reducing the capital or can be shown as a debit balance on the asset side.
Accounting entry for loss transferred is as follows :
Capital A/c …Dr.
To Profit & Loss A/c
(being net loss transferred to capital account)
Example
A Business has a total income of $50,000 in an accounting year and has expenses amounting to $60,000 in that particular year. The profit and loss account will show a net loss of $10,000 ($60,000-50,000). Net loss will be transferred to capital A/c. Capital of the business will be reduced by $10,000. This loss can also be shown on the asset side of the balance sheet.
Extract of a Profit and loss a/c showing net loss is as under:
Profit and loss A/c for the year ended …..
The debit balance for a non-corporate entity is shown as a reduction from the capital account
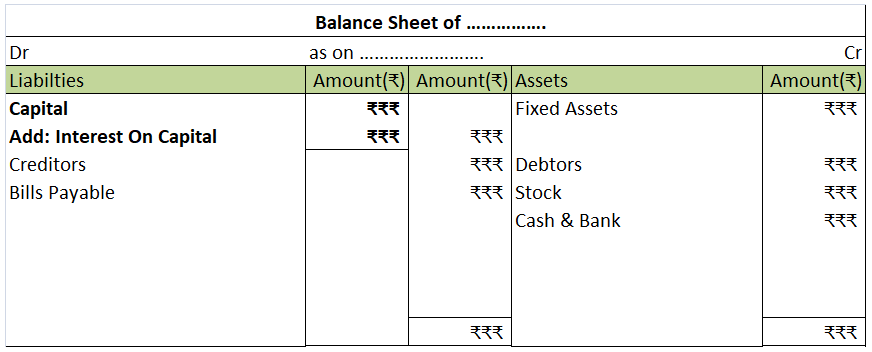
Extract of the Balance sheet showing the debit balance of Profit & Loss A/c is as under :
Balance Sheet as on…
Less: Profit & Loss A/c
While the Debit balance of profit and Loss A/c of a corporate entity is shown as a reduction in Reserves and surplus. If the business doesn’t have reserves then the debit balance is shown on the asset side.
Extract of the Balance sheet showing the debit balance of Profit & Loss A/c is as under :
Balance Sheet as on..
Less: Profit & Loss A/c
Conclusion: Debit balance of profit and loss a/c represents that expenses are more than the income of a business in an accounting period. Debit balance of profit and loss a/c indicates that company need to increase its income or cut down on unnecessary expenses.
The business needs to find out the reason of excessive expenses because accumulated losses are not good for the health of the company.
See less