

Realisation account A realisation account is a nominal account prepared at the time of dissolution of a business. All the assets and liabilities except cash and bank balance are transferred to the realisation account. A realisation account is prepared to calculate the profit or loss on the dissoluRead more
Realisation account
A realisation account is a nominal account prepared at the time of dissolution of a business. All the assets and liabilities except cash and bank balance are transferred to the realisation account. A realisation account is prepared to calculate the profit or loss on the dissolution or closing of the firm.
All the assets are transferred to the debit of the realisation account and all the liabilities are transferred to the credit of the realisation account. When assets are sold, Cash A/c is debited and Reliastion A/c is credited and when liabilities are paid off, Cash A/c is credited and Realisation A/c is credited.
If the credit side exceeds the debit side of the realisation account, it results in profit. In contrast, if the debit side exceeds the credit side of the realisation account, it results in a loss. in case of profit, the Capital account is credited and in case of loss, the Capital account is debited.
Credit side of realisation account
- Liabilities: All the liabilities including sundry creditors, outstanding expenses, bills payable, loans and advances, bank overdrafts and cash credit are transferred to the credit side of the realisation account. Capital account of partners, profit and loss balance and loans from partners are not transferred.
- Accounting entry for this is as follows:
Liabilities A/c Dr…..
To Realisation A/c …..
(All the liabilities transferred to realisation account)
- Provisions: All the provisions including provision for doubtful debts and provision for taxation are transferred to the credit side of the realisation account.
- Accounting entry for this is as follows:
Provision A/c Dr…..
To Realisation A/c …..
(All the provisions transferred to the realisation account)
- Cash and bank A/c: Sale proceeds of all the assets including Land and building, Plant and machinery, furniture, stock, debtor and investment are transferred to the credit side of the Realisation account.
-
- Accounting entry for this is as follows:
Bank A/c Dr…..
To Realisation A/c …..
(Asset sold for cash)
- Loss on realisation: If the debit side of the realisation account exceeds the credit side, it results in loss then the capital account is debited.
-
- Accounting entry for this is as follows:
Capital A/c Dr…..
To Realisation A/c …..
(Being loss transferred to the capital account)
The debit side of the realisation account
All the assets including Land and building, Plant and machinery, furniture, stock, debtor and investment are transferred to the debit of the realisation account and payment of outside liabilities is also recorded on the debit side of the realisation account. Payment made for dissolution expenses is also recorded on the debit side of the realisation account.
Format for realisation Account is as under:
| Realisation A/c | |||
| Particulars | Amount | Particulars | Amount |
| To Land & Building | By Provision for Doubtful Debts A/c | ||
| To Plant & Machinery | By Sundry Creditors A/c | ||
| To Furniture | By Bills Payable A/c | ||
| To Debtors | By Outstanding Expenses A/c | ||
| To Goodwill A/c | By Bank Loan, Overdraft, Cash Credit A/c | ||
| To Investment A/c | By Bank/ Cash A/c (Assets realized): | ||
| To Bank/ Cash A/c (Liabilities Paid): | Land and Building | ||
| Sundry Creditors | Plant and Machinery | ||
| Bill Payable | Furniture | ||
| Outstanding Expenses | Stock | ||
| Bank Loan, | Debtors | ||
| Overdraft, | Bad Debts recovered | ||
| Cash Credit | Investment | ||
| To Bank/ Cash A/c | By Partner’s Capital A/cs | ||
| (Realisation Expenses) | (assets taken over) | ||
| To Partner’s Capital A/c | By Partner’s Capital A/cs | ||
| (Realisation Expenses) | (Loss on Realisation) | ||
| To Partner’s Capital A/cs | |||
| (Profit on Realisation) | |||
| Total | Total |
See less


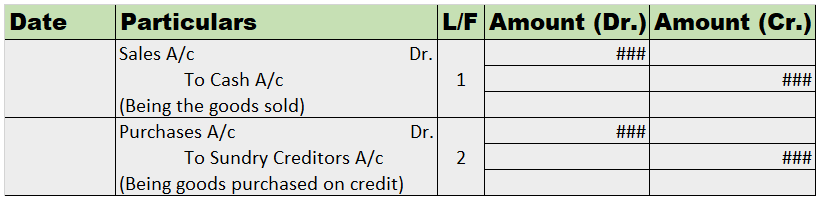






Journal Entry Prepaid Rent A/c Dr. To Cash A/C (Being rent paid in advance) "Prepaid Account" is treated as an asset and as per the modern rules debit the increase in the asset. "Cash Account" is an asset and as per the accounting rules credit the decrease in the asset. Adjustment entry: TheRead more
Journal Entry
Prepaid Rent A/c Dr.
To Cash A/C
(Being rent paid in advance)
“Prepaid Account” is treated as an asset and as per the modern rules debit the increase in the asset.
“Cash Account” is an asset and as per the accounting rules credit the decrease in the asset.
Adjustment entry: The prepaid rent entry has an adjustment entry when the rent expense account is due. The journal entry for that is
Rent Expense A/c
To Prepaid Rent A/c
(Being the rent expense due and adjusted from the prepaid expense)
Example: ABC.Ltd signs a one-year lease on an office floor for Rs 10,000 a month. The landlord requires that the Company pays the annual amount Rs 120,000 at the beginning of the year.
The journal entry for Company would be as follows:
At the beginning
Prepaid Rent A/c – 1,20,000
To Cash A/c – 1,20,000
(Being rent paid in advance for the year)
At the time rent was due (Month 1)
Rent Expense A/c – 10,000
To Prepaid Rent A/c – 10,000
(Being the rent expense due and adjusted from the prepaid expense)
The same entry done in month 1 will be repeated in the next 11 months.
See less