Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

What are biological assets? What is their accounting treatment?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 12, 2025 at 7:40 am

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture. IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity. Agricultural Activity- It is the management of biological transformatRead more

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture.

    IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity.

    • Agricultural Activity- It is the management of biological transformation by an entity and measuring the change in the quality and quantity of biological assets.
    • Biological Transformation- It comprises the process of growth, degeneration, production and procreation that cause qualitative or quantitative changes in a biological asset
    • Biological Asset – They are living plants or animals owned by an entity
    • Agricultural Produce- It is the harvested / detached product of the entity’s biological asset.

    IAS 41 does not apply to

    • Agricultural land
    • Intangible assets related to agricultural activity
    • Products that are the result of processing after the point of harvest, for example, yarn, carpet, rubber, wine, etc
    • The land on which the biological assets grow, regenerate, degenerate.


    Biological Assets

    Definition

    Biological assets are living plants or animals that go through biological transformation, owned by an entity to prepare agricultural produce for the purpose of agricultural activities only.

    Living plants include plants that are consumable within 1 year and are harvested. It also includes plants that are used for lumbering and wood-cutting activities.

    Examples

    Examples of biological assets are:

    Sheep, pigs, poultry, beef cattle, fish, dairy cows, plants for harvest etc

    Importance

    • Farming: They are key to agriculture and food production.
    • Income: They generate substantial income for businesses in industries such as vineyards, livestock, silviculture, etc.
    • Sustainability: Properly managing them helps the environment.


    Accounting & Presentation

    Recognition

    Under IAS 41 biological assets are recognised when

    • The business must have ownership over them from a past event.
    • The future economic benefits are expected to flow to the business from their ownership.
    • The cost or fair value of the asset can be measured reliably.

    Agricultural produce is recognised

    • It is recognised at the point of harvest or detachment.

    Agricultural produce is derecognised when

    • They enter the trading.
    • Enters the production process.

    Measurement

    • Biological assets are measured on initial recognition and at each balance sheet date at their fair value less costs to sell.
    • Costs to sell are incremental costs incurred in selling the asset.
    • Agricultural produce is measured at the point of harvest, at fair value less costs to sell at the point of harvest.
    • Agricultural produce after the point of harvest/ detachment is transferred and treated under the IAS 2 Inventory

    Gains & Losses

    • Gains and losses arising from the initial recognition of biological assets are reported in the statement of profit and loss.
    • The change in fair value less costs to sell of a biological asset between balance sheet dates is reported as gain or loss in the statement of profit and loss.
    • A gain or loss arising on initial recognition of agricultural produce at fair value less selling costs is included in profit or loss for the period in which it arises.

    Treatment

    • The sale of agricultural produce is treated as revenue in the statement of profit and loss.
    • Agricultural produce to be harvested for more than 12 months, livestock to be held for more than 12 months and trees cultivated for lumber are recorded as Biological assets under the Non-current assets head in the balance sheet.
    • Agricultural produce to be harvested within 12 months, livestock to be slaughtered within 12 months and annual crops like wheat, and maize are recorded as Biological assets under the head Current assets in the balance sheet.
    • Inventories produced from agricultural produce are presented as Inventory under the head Current assets in the balance sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is a contra revenue account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 7, 2021 at 7:55 pm
    This answer was edited.

    The term ‘contra’ means  'opposite'. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance. The purpose of the contra revenue account is to ascertain the actuaRead more

    The term ‘contra’ means  ‘opposite’. Therefore, a contra revenue account is an account that is opposite of the revenue accounts of a business i.e. sales account. It has the opposite balance of the revenue account i.e. debit balance.

    The purpose of the contra revenue account is to ascertain the actual amount of sales and record the items which have reduced the sales.

    These are the contra revenue accounts commonly seen in businesses:

    • Sales return account: This account records the amount of goods sold returned by customers. The journal entry for recording sale return is as follow:
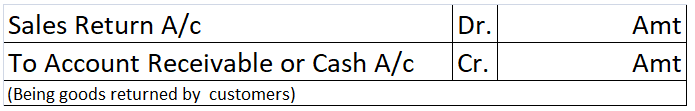
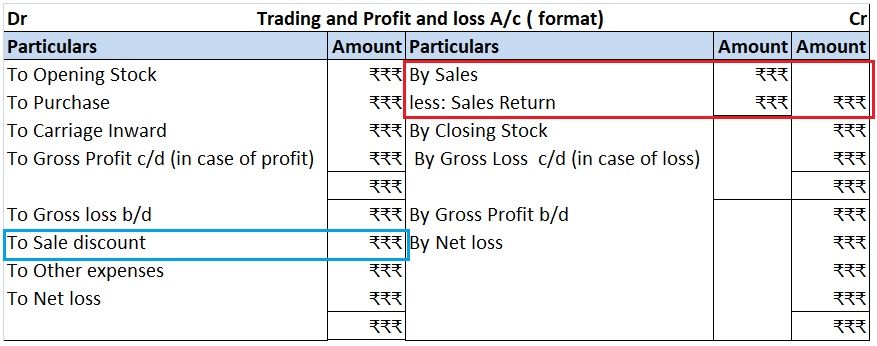
    The total sales return is deducted from the sales in the balance sheet. Though being opposite of the sales account, the sale return account is not an expense account. It is considered an indirect loss as it reduces sales.

    • Sale Discount account: This account records the amount of discount allowed to customers. The journal entry for recording sale discounts is as follows:
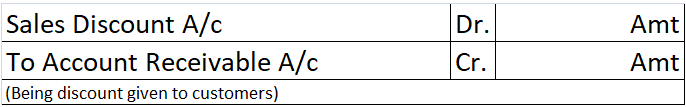
    Sales discount is an expense hence it is debited to the profit and loss account.

    Sales returns and sales discounts are shown in the trading and profit and loss account in the following manner:
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Journal Entries

What are 10 examples of journal entries?

  • 1 Answer
  • 0 Followers
Answer
  1. A_Team (MBA - Finance Student) ISB College
    Added an answer on December 13, 2022 at 5:05 am
    This answer was edited.

    Here are 10 examples of accounting entries: A company purchases $500 worth of office supplies on credit from a supplier. Office supplies expense account would be debited Accounts payable would be credited   A firm receives $1,000 in cash from a customer for services rendered. In this case, CashRead more

    Here are 10 examples of accounting entries:

    • A company purchases $500 worth of office supplies on credit from a supplier.
      • Office supplies expense account would be debited
      • Accounts payable would be credited


    • A firm receives $1,000 in cash from a customer for services rendered. In this case,
      • Cash account would be debited
      • Service revenue account would be credited


    • A business pays $250 in salaries to its employees.
      • A debit would be made to the salaries expense account
      • A credit would be made to the cash account


    • A business borrows $5,000 from a bank and receives the funds as a loan. The entry would be,
      • A debit to the bank account
      • A credit to the loan payable account


    • A company sells $800 worth of inventory to a customer for cash.
      • The entry would be a debit to the cash account
      • A credit to the sales revenue account


    • A firm purchases $3,000 worth of equipment on credit from a supplier.
      • The entry would be a debit to the equipment account
      • A credit to the supplier’s account


    • A company incurs $500 in advertising expenses for a new marketing campaign (cash).
      • The entry would be a debit to the advertising expense account
      • A credit to the cash account


    • A firm collects $1,200 from a customer. The entry would be,
      • A debit to the cash account
      • A credit to the customer’s account


    • A business pays $700 in rent for its office space. The entry would be,
      • A debit to the rent expense account
      • A credit to the cash account


    • An organization pays off a $2,000 loan to the bank. The entry would be,
      • A debit to the loan payable account
      • A credit the cash account


    I also found a long list of example journal entries and a free PDF to download here.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Miscellaneous

What are some examples of revenue receipts and capital receipts?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 3, 2021 at 2:41 pm
    This answer was edited.

    Firstly, let’s understand the meaning of both terms. Revenue receipts:  The term 'revenue' suggests these are the amounts received by a business due to its operating activities. These receipts arise in a recurring manner in a business. Such receipts don’t affect the balance sheet. They are shown inRead more

    Firstly, let’s understand the meaning of both terms.

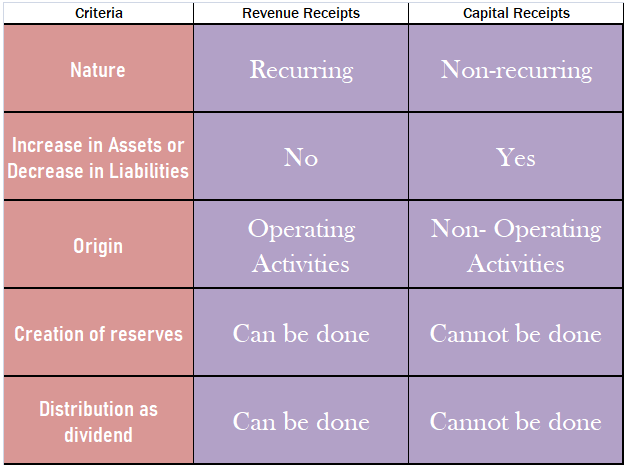
    Revenue receipts:  The term ‘revenue‘ suggests these are the amounts received by a business due to its operating activities. These receipts arise in a recurring manner in a business. Such receipts don’t affect the balance sheet. They are shown in the statement of profit or loss. Such receipts are essential for the survival of the business.

    Examples of revenue receipts are as follows:

    • Proceeds from the sale of goods.
    • Proceeds from the provision of services
    • Rent received
    • Interest received from deposits in banks or financial institutions
    • Discount received from creditors (shown in the debit side of P/L A/c)

    Capital receipts: The term ‘capital’ that such receipts are do not arise due to operating activities, hence not shown in the Profit and loss statement.  These are the money received by a business when they sell any asset or undertake any liability. These receipts do not arise in a  recurring manner in a business.  They don’t affect the profit or loss of the business. They are not essential for the survival of the business.

    Examples of capital receipts are as follows:

    • Loan from a bank or financial institution. (Increase in liabilities)
    • Proceeds from the sale of an asset. (decrease in assets)
    • Proceeds from sale of  investments. (decrease in assets)
    • Proceeds from the issue of equity shares. (Increase in liabilities)
    • Proceeds from issue of debentures. (Increase in liabilities)

    I have given a table below for more understanding:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Accounting Terms & Basics

What is the meaning of sundry creditors?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on August 13, 2022 at 7:47 am
    This answer was edited.

    Meaning The term ‘Sundry creditors’ consist of two words:  ‘Sundry’ and ‘creditors’.  The word ‘sundry’ means the items which are not significant enough to be named separately. It also refers to a collection of miscellaneous items. Creditors are the person from whom money is borrowed or goods are puRead more

    Meaning

    The term ‘Sundry creditors’ consist of two words:  ‘Sundry’ and ‘creditors’. 

    The word ‘sundry’ means the items which are not significant enough to be named separately. It also refers to a collection of miscellaneous items.

    Creditors are the person from whom money is borrowed or goods are purchased on credit by a business or a non-business entity. They have to be repaid after a period of time which is usually less than or up to one year.

    By combining the meaning of both words, ’sundry’ and ‘creditor’, the term ‘sundry creditor’ will refer to the collection of insignificant creditors of an entity.

    Back in the days when accounting records were maintained on paper, only the records of those creditors were maintained separately, from whom goods are purchased regularly and in large amounts. 

    But there used to be numerous other creditors with whom the transactions were occasional and insignificant. To reduce the paperwork, records of all such creditors were maintained on a single page or book under the head ‘Sundry Creditors’

    Nowadays, as accounting records are maintained digitally, hence maintaining records of each and every creditor is not a problem. 

    Hence, every creditor whether small or big, is grouped under the head ‘Sundry creditor’ or ‘Trade Creditor’.


    Accounting Treatment 

    Sundry creditors are the persons to whom a business owes money. 

    Hence, as per golden rules of accounting, Sundry creditor is a personal account and the golden rule for personal account is, ‘Debit the receiver and credit the giver’ 

    We know sundry creditors are liabilities, hence, as per modern rule of accounting, sundry creditors are credited in case of increase and debited in case of decrease.

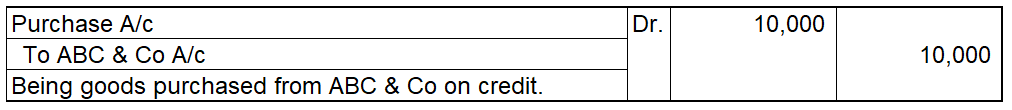
    Example, a business purchased goods for Rs. 10,000 from ABC & Co. The journal entry will as follows:

    Here, ABC & Co is the creditor. It is credited as it is a personal account and the creditor has given the goods to the business, hence the giver is credited.

    From point of view of modern rules of accounting, ABC & Co. is a creditor, a liability. On purchase of goods on credit, a liability is created. Hence, ABC & Co A/c is credited.


    Balance sheet

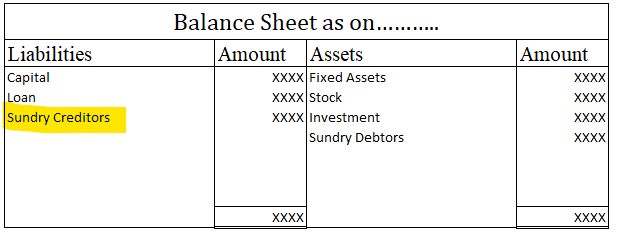
    Sundry creditor is a current liability, so it is shown on the liabilities side of a balance sheet. Trade payable and accounts payable mean sundry creditors only.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is a valuation account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on January 11, 2022 at 7:07 pm
    This answer was edited.

    Meaning A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value. The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the mainRead more

    Meaning

    A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value.

    The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the main ledger account.  This is a conservative approach to use valuation accounts to present the value of the concerned asset or liability at a reduced value.

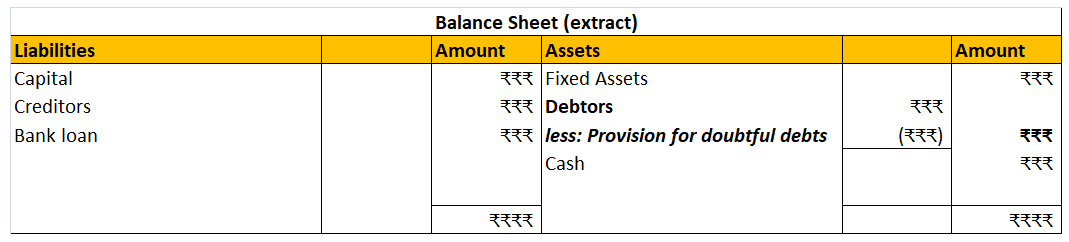
    The most common example of a valuation account is the ‘Provision for doubtful debts account’. It appears in the balance sheet as a reduction from the debtors’ accounts. Also when the amount is transferred to this provision, it appears in the statement of profit and loss account. But it doesn’t appear in the debtors’ account ledger.

    Treatment

    A valuation account appears only in the balance sheet. Sometimes, it also appears in the profit and loss account when any amount is transferred to it.

    Valuation accounts are only used in accrual accounting. They cannot be used in cash-based accounting as there is no flow of cash related to valuation accounts.

    They have a balance opposite of their paired accounts i.e. if their paired account is an asset then they will have a credit balance and if it is a liability then they will have a debit balance.

    Other Examples of valuation accounts are as follows:

    1. Provision for doubtful debts (offsets the account receivables or debtors’ account)
    2. Accumulated depreciation (report the assets net of depreciation)
    3. Discount on bonds payable (reduces the reporting balance of bond payable account)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is interest on partner’s capital?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on December 6, 2021 at 4:57 pm
    This answer was edited.

    A Capital Account is an account that shows the owner's equity in the firm and a Partner's Capital Account is an account that shows the partner's equity in a partnership firm. Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are: CapitalRead more

    A Capital Account is an account that shows the owner’s equity in the firm and a Partner’s Capital Account is an account that shows the partner’s equity in a partnership firm.

    Partner’s Capital Account includes transactions between the partners and the firm. Examples of such transactions are:

    • Capital introduced in the firm
    • Capital withdrawn
    • Interest on Capital
    • Interest on Drawings
    • Profit or loss in the financial year, etc.

    When partners are given interest on their capital contribution in the firm, it is called on Interest on Capital.

    In case the partnership firm does not have a Partnership Deed, the Partnership Act does not include a provision for Interest on Capital. However, if the partners want they can mutually decide the rate of Interest on Capital.

    Interest on Capital is calculated on the opening capital of the partners and is only allowed when the firm makes a profit, that is, in case a firm incurs losses, it cannot allow Interest on Capital to its partners.

    Example:

    In a partnership firm, there are two partners A and B, and their capital contribution is Rs 10,000 and 20,000 respectively. Interest on capital is @ 10% p.a. The Interest on Capital for both the partners is:

    Partner A- 10,000 * 10/100 = 1,000

    Partner B- 20,000 * 10/100 = 2,000

    The journal entry for Interest on Capital is an adjusting entry and is shown as:

    Interest on Capital A/c                                                          Dr. 3,000
                                         To A’s Capital a/c 1,000
                                         To B’s Capital A/c 2,000
    • Partner’s Capital Account is credited because it is credit in nature and interest on capital is an addition to the account.
    • Interest on Capital Account is debited because it is an expense account.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What are fictitious assets and intangible assets?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on September 18, 2021 at 3:21 am
    This answer was edited.

    Fictitious assets On seeing or hearing ‘fictitious’, the words which come to our mind are ‘not true, ‘fake’ or ‘fantasy’. So, fictitious assets are those items that appear on the assets side of the balance sheet but are actually not assets. In substance, fictitious assets are the expenses and lossesRead more

    Fictitious assets

    On seeing or hearing ‘fictitious’, the words which come to our mind are ‘not true, ‘fake’ or ‘fantasy’. So, fictitious assets are those items that appear on the assets side of the balance sheet but are actually not assets.

    In substance, fictitious assets are the expenses and losses that are not completely written off in a financial year and are required to be carried forward to the next financial year.

    The examples of fictitious assets are as follows:

    1. Deferred Advertisement expense
    2. Loss on the issue of debentures.
    3. Debit balance of Profit and Loss account ( Net loss )*
    4. Preliminary expenses.

    Fictitious assets appear on the asset side of the balance sheet as expenses and losses have a debit balance.

    *when the balance sheet is prepared as per Schedule III of Companies Act, the Net loss is shown as a negative figure under the head Reserve and Surplus.

    Intangible Assets

    Intangible assets mean the assets which don’t have any physical existence. They cannot be seen or touched but are assets because they do provide future economic benefits to the business. Like tangible assets (like machinery and building), they can be also created, purchased or sold.

    Like tangible assets are depreciated, intangible assets are gradually written over by amortization over their useful lifespan to account for the economic benefits provided by them.

    Following are the examples of intangible assets:

    1. Goodwill
    2. Brand name
    3. Trademark
    4. Patents
    5. Copyrights

    Intangible assets which are created by the business-like goodwill or brand recognition do not appear in the balance sheet.

    Only acquired intangible assets can be shown in the balance sheet. Like purchased goodwill, patents, trademarks etc.

    Intangible assets also face impairment if their fair value is less than their carrying value after deducting amortization expense. The difference between carrying value and fair value is shown in the Profit and loss A/c as impairment charge and the asset is valued at fair value in the balance sheet.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Journal Entries

What is the journal entry for bad debts?

  • 1 Answer
  • 0 Followers
Answer
  1. Karan B.com and Pursuing ACCA
    Added an answer on August 9, 2021 at 10:24 am
    This answer was edited.

    Bad Debt is the amount that is irrecoverable from the debtors. It is the portion of the receivables. It includes two accounts “Bad Debts A/c” and “Debtors A/c or Accounts Receivable A/c”. The amount cannot be recovered by the debtor for reasons like the debtor is no longer in the position to pay offRead more

    Bad Debt is the amount that is irrecoverable from the debtors. It is the portion of the receivables. It includes two accounts “Bad Debts A/c” and “Debtors A/c or Accounts Receivable A/c”.

    The amount cannot be recovered by the debtor for reasons like the debtor is no longer in the position to pay off the debt or has become insolvent.

    There are two methods to write off bad debts:

    1. Direct Method
    2. Allowance for Doubtful Debts


    1. Direct Method: In this method, the amount of bad debts is directly deducted from the total receivables and the second effect is transferred to the debit side of Profit and Loss A/c as an expense.

    The journal entry for bad debts as per modern rules of accounting is as follows:

    Bad Debts A/c Debit Increase in expenses
          To Accounts Receivable A/c Credit Decrease in assets
    (Being bad debts written off )


    Journal entry for transferring bad debts to profit and loss account:

    Profit and Loss A/c Debit
          To Bad Debts A/c Credit
    (Being bad debts transferred to profit and loss a/c )


    For example, A Ltd had a total receivable of Rs.2,50,000 and bad debts for the period amounted to Rs.10,000.

    Here, the journal entries will be:

    Bad Debts A/c Debit 10,000
          To Accounts Receivable A/c Credit 10,000
    (Being bad debts written off )


    Profit and Loss A/c Debit 10,000
          To Bad Debts A/c Credit 10,000
    (Being bad debts transferred to profit and loss a/c )


     2. Allowance for Doubtful Debts:  In this method allowance is the estimation of the debts which is doubtful to be paid. The company creates a reserve for such debts which are uncollectible.

    Firstly, the company will create a reserve which will be based on the accounts receivable. The journal entry will be:

    Bad Debts A/c Debit
          To Allowance for Doubtful Debts A/c Credit
    (Being allowance for doubtful debts created)


    When a specific receivable is uncollectible it will be charged as an expense, and Allowance for Doubtful Debts will be “Debited” and Accounts Receivable will be “Credited”.

    Allowance for Doubtful Debts A/c Debit
                  To Accounts Receivable A/c Credit
    (Being bad debts written off)

    For example, Mr.B sold goods worth Rs.15,000 to Mr.D. He creates an allowance of Rs.15,000 in case Mr.D fails to pay the amount. At the end of the period, Mr.D defaults and does not pay the debt.

    In this case, Mr.B will first record the journal entry for allowance and then will write off Mr.D’s account.

    Bad Debts A/c 15,000
          To Allowance for Doubtful Debts A/c 15,000
    (Being allowance of Rs.10,000 created for doubtful debts)


    Allowance for Doubtful Debts A/c 15,000
                  To Mr.D’s A/c 15,000
    (Being Mr.D’s account written off)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Miscellaneous

What is the difference between cash discount & trade discount?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on August 18, 2021 at 4:41 pm

    A cash discount is a discount allowed to customers when they make payments for the items they purchased. This type of discount is generally based on time. The early the payment is made by the debtors, the more discount they earn. To be more precise cash discount is given to simulate or encourage earRead more

    A cash discount is a discount allowed to customers when they make payments for the items they purchased. This type of discount is generally based on time. The early the payment is made by the debtors, the more discount they earn. To be more precise cash discount is given to simulate or encourage early payment by the debtors.

    Trade discount is a discount allowed by traders on the list price of the goods to the customer at specified rate. Unlike cash discount, trade discount is based on number of sale i.e, more the sale more the discount earned. This is mainly given on bulk orders by the customers.

    To understand trade discount and cash discount let me give you simple example

    Mr. X purchased goods from Mr. Y of list price Rs 10,000. Mr. Y allowed a 10% discount to Mr.X on the list price for purchasing goods in bulk quantity. Further, he was provided with cash discount of Rs 500 for making an immediate payment. Therefore the entry for the above transaction in the books of Mr. X would be

    Purchase A/c                                                        ……Dr 9,000
               To Cash A/c 8,500
               To Discount received 500
    (Being goods purchased from Mr. Y worth Rs. 10,000@ 10% trade discount and cash discount of Rs. 500)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.