

Accrual Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irrespective of the fact when such amount has been paid. An accrual of the expenditure which is not paid will be listed in the books of accounts. These accruals can be furtRead more
Accrual
Accrual expense means the transaction that takes place in a particular period must be accounted for in that period only irrespective of the fact when such amount has been paid.
An accrual of the expenditure which is not paid will be listed in the books of accounts. These accruals can be further divided into two parts
Accrual Expense-
Accrual Expense means any transaction that takes place in a particular period but the amount for it will be paid on a later period.
For example- If rent of 10,000 for the month of March was paid in April month then this rent will be accounted for in the books in March
For example- Interest of 1,000 for the month of March of the loan amount of 10,000 paid in April then will be accounted for in the books in March
These are the following accrued expense
- Accrual Rent– Accrual rent means the amount for using the land of the landlord is paid at a later period than the period when it is put into use.
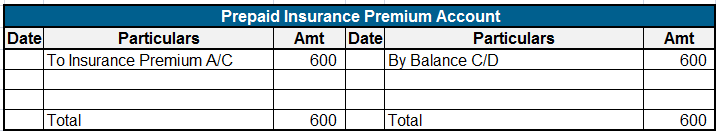
- Accrual Insurance– Accrual insurance means the amount paid as a premium to the insurance company paid on a later period than the period when it is due
- Accrual Expense- Acrrual expense means the amount for any expense paid on a later period than the period when it pertains to be paid
- Accrual Wages- Accrual wages means the amount which is paid to employees on a later period than the period when the wages get due
- Accrual Loan Interest– Loan Interest means the amount of interest on a loan which is paid on a later period than the period when it is due on
Accrual Revenue-
Accrual Revenue means any transaction that takes place in a particular period but the amount for it will be received in the later period.
For example- If interest of 10,000 on bonds for the period of March is received in April months then this amount will be accounted for in March. These are the following accrued revenue
For example- Rent of 10,000 for the month of March received in April month then this rent will be accounted for in the books in March
- Accrual Income- Acrrual expense means the amount for any income received on a later period than the period when it pertains to be received
- Accrual Rent– Accrual rent means the amount for using the land of the entity by the other party is received at a later period than the period when it is put into use.
- Accrued Interest– Accrued interest means the amount of interest received on a later period than the period when it pertains to receive








Definition Not-for-profit organizations are also known as non-profit organizations set up to further cultural, educational, religious, professional, or public service objectives. Its aim is not to earn profit Accounting done by non-profit organizations is fund based. Type of accounting Non-pRead more
Definition
Not-for-profit organizations are also known as non-profit organizations set up to further cultural, educational, religious, professional, or public service objectives. Its aim is not to earn profit
Accounting done by non-profit organizations is fund based.
Type of accounting
Non-profit organizations do Fund Based Accounting.
Donations received or funds set aside for specific purposes are credited to a separate fund account and are shown on the liabilities side of the balance sheet.
The income from or donations for these funds are credited to the respective fund account. On the other hand, expenses or payments out of these funds are debited.
Accounting when done on this basis is known as Fund Based Accounting.
Let me explain to you with an example :
The sports fund has a balance of Rs 100000 which is invested as a fixed deposit in a bank earning 8% interest. A further donation of Rs 10000 is received towards it. Expenses incurred towards prizes are Rs 7000; Rs 3000 towards trophies and Rs 4000 distribution of cash prizes. The accounts are shown as follows :
Categories of funds
In the case of non-profit organizations, funds may be classified under the following heads :
Unrestricted fund :
The unrestricted fund does not carry any restriction with respect to its use. In other words, management can use the amounts in the funds as it deems appropriate, but to carry out the purpose for which the organization exists.
This is known as the general fund or the capital fund to which the surplus for the year is added and in case of deficit, deducted.
Restricted fund :
A restricted fund is a fund, the use of which is restricted either by the management or by the donor for a specific purpose.
Examples of such funds are endowment funds, annuity funds, loan funds, prize funds, sports funds, etc.
- Prize funds: it is a fund set up to use for distribution as prizes say for achievements or contributions to the welfare of society.
See less